

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
👀 Today’s Stories at a Glance
💼 Payrolls with odds at 30%: September jobs land at 1:30pm UK / 8:30am ET, with about 90,000 expected and October hike odds near 30%.
👟 Nike guided to a deeper drop: sales should fall high-single digits this year, China fell 26%, and shares were down about 10% pre-market.
🇬🇧 Gilts broke 6%: the 30-year yield topped 6% for the first time since 1998, and the FTSE 100 had its worst day since May.
🛢️ Oil fell on stockpile talk: Brent dropped about 3% below $100 after France proposed releasing 50 million barrels each of diesel and crude.
💻 Accenture’s AI-fear relief: shares jumped as much as 24% on record big deals, then closed up 15.78% at $212.30.
🇪🇺 Eurozone inflation hit 3.8%: September’s flash reading beat the 3.6% forecast, the highest since 2023, with energy prices up 18.8% on the year.
🪙 Bitcoin back above $86,000: the price rose about 3.5% overnight, and spot funds took in $102.7 million on Thursday after Wednesday’s outflow.
🏛️ Crypto Mom leaves the SEC: Hester Peirce’s last day leaves a 2-member commission, with no successor named and the CLARITY Act still stalled.
📱 Meta’s $40 billion ask: New Mexico wants up to $40 billion in penalties after a jury found 43 million consumer-law violations.
🔍 The 4.1% Question Cheat Sheet: hiring ran near 50,000 a month for a year and unemployment still fell, so the jobless rate decides October.
📈 Zoom back above its trend: Chart of the Day covers $100, the $107.25 and $123.98 lines, and Sensei’s Deep Trend at $89.87.
🧠 One Big Thing
At 1:30pm UK, 8:30am in New York, the US publishes September’s jobs report, the last one the Fed sees before it decides on 28 October. About 90,000 new jobs are expected, with unemployment at 4.1%. Futures put the chance of an October rate rise at about 30%, down from about 70% on Monday. Fed Vice Chair Philip Jefferson said on Thursday that the next judgment “may take more time”. A strong number with unemployment holding at 4.1% is the result that would bring October back into play.
⚖️ Fear & Greed
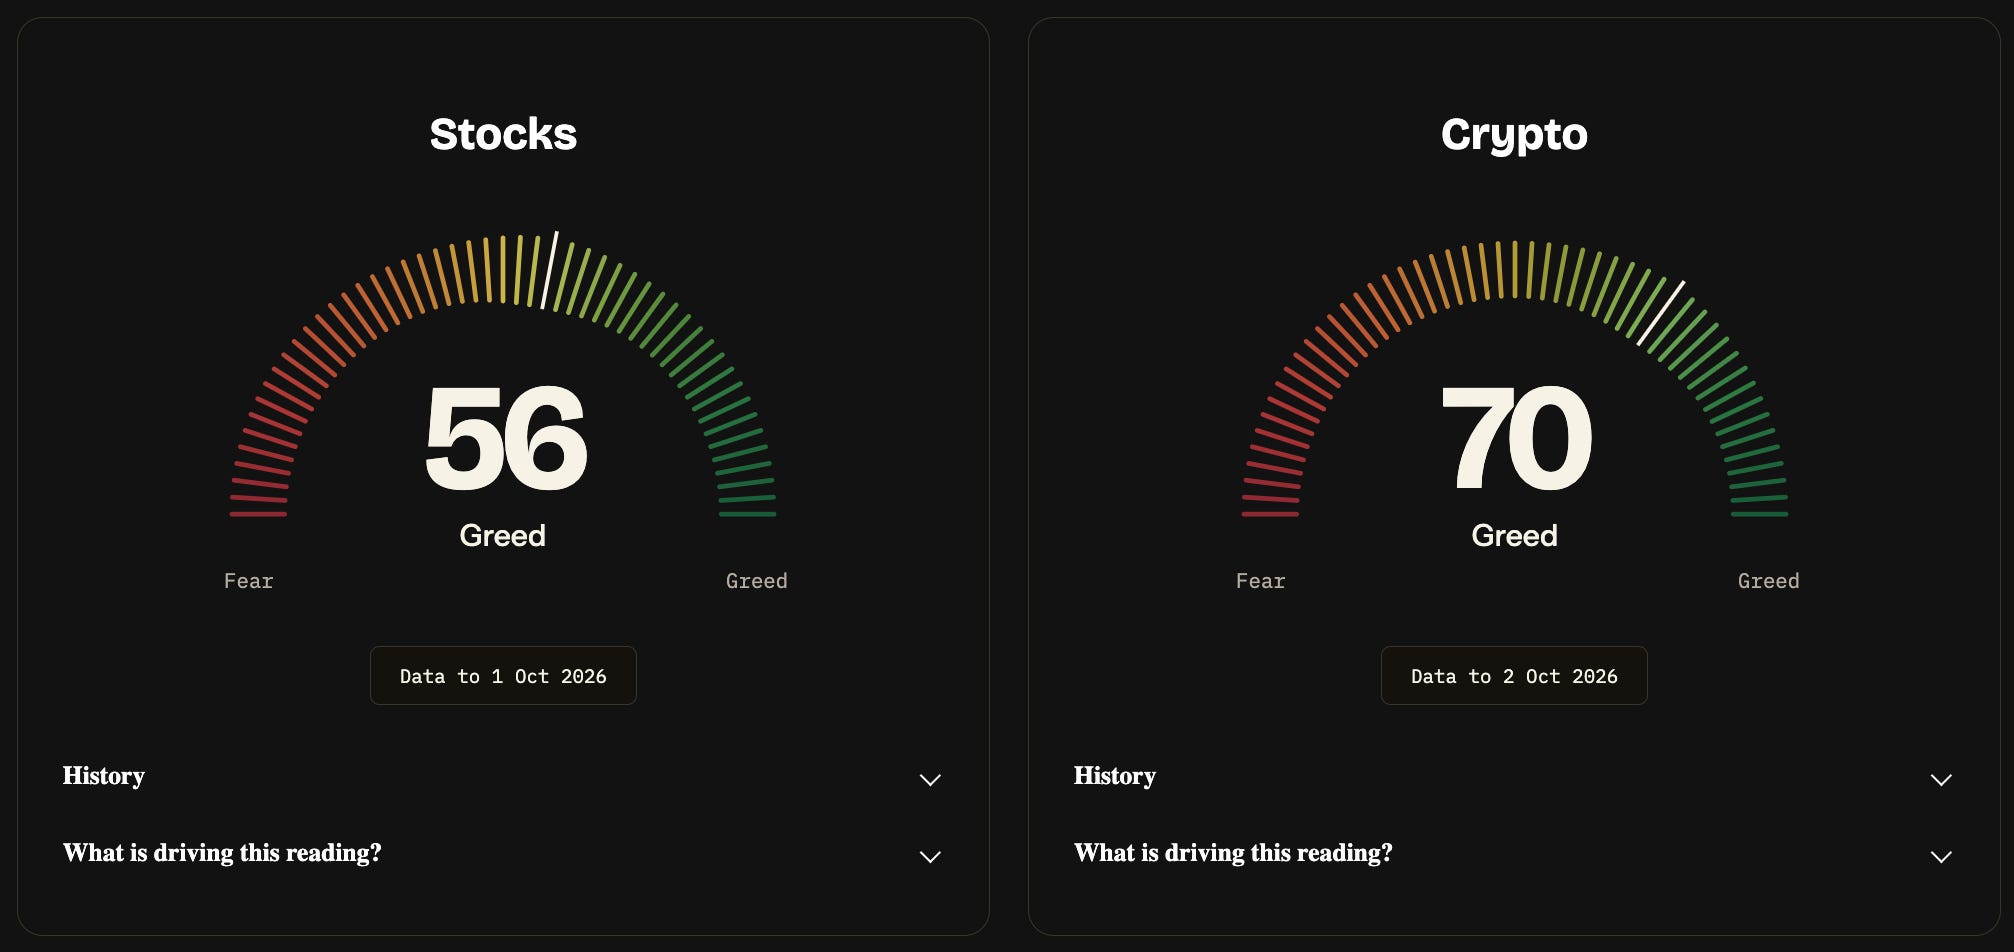
📉 The Number That Matters
77.9
The prices American factories pay jumped to 77.9 in September from 71.1, the ISM survey showed on Thursday. Any reading above 50 means more firms are paying more. September’s jobs report lands on top of that.
⚔️ Winners vs Losers
🟢 Top Gainers
SYNA 0.00%↑ : +15.17% Synaptics Incorporated shares jumped after ON Semiconductor changed its takeover to an all-cash deal at USD 123 per share, beating off an unsolicited rival bidder. The stock is now trading just below the cash offer price.
🔴 Top Losers
NKE 0.00%↑ : -10.10% Nike, Inc. shares fell after fiscal first-quarter revenue dropped 4% to USD 11.21 billion and missed estimates, dragged down by a 26% slide in Greater China. Full-year adjusted earnings guidance of USD 1.15 to 1.35 per share came in well below the USD 1.61 consensus.
STX 0.00%↑ : -5.05% Seagate Technology Holdings plc shares slipped as traders took profits after a 16.70% run over the past month and a 2.52% gain in Thursday’s session.
📊 Market Snapshot
Cryptocurrencies:
Bitcoin (BTC): $86,268 (▲ 1.70%)
Ethereum (ETH): $2,743 (▲ 1.41%)
XRP: $1.54 (▲ 3.03%)
Equity Indices (Futures):
S&P 500: 7,761 (▲ 0.47%)
NASDAQ 100: 30,983 (▲ 0.72%)
FTSE 100: 10,472 (▲ 0.12%)
Commodities & Bonds:
10-Year US Treasury Yield: 5.23% (▼ 0.25%)
Oil (WTI): $89 (▼ 3.80%)
Gold: $4,183 (▲ 0.12%)
Silver: $61.05 (▲ 0.17%)
Data as of: UK: 12:00 BST / US: 07:00 EDT / Asia (Tokyo): 20:00 JST
✅ 5 Things to Know
💼 Jobs report lands with October hike odds near 30%
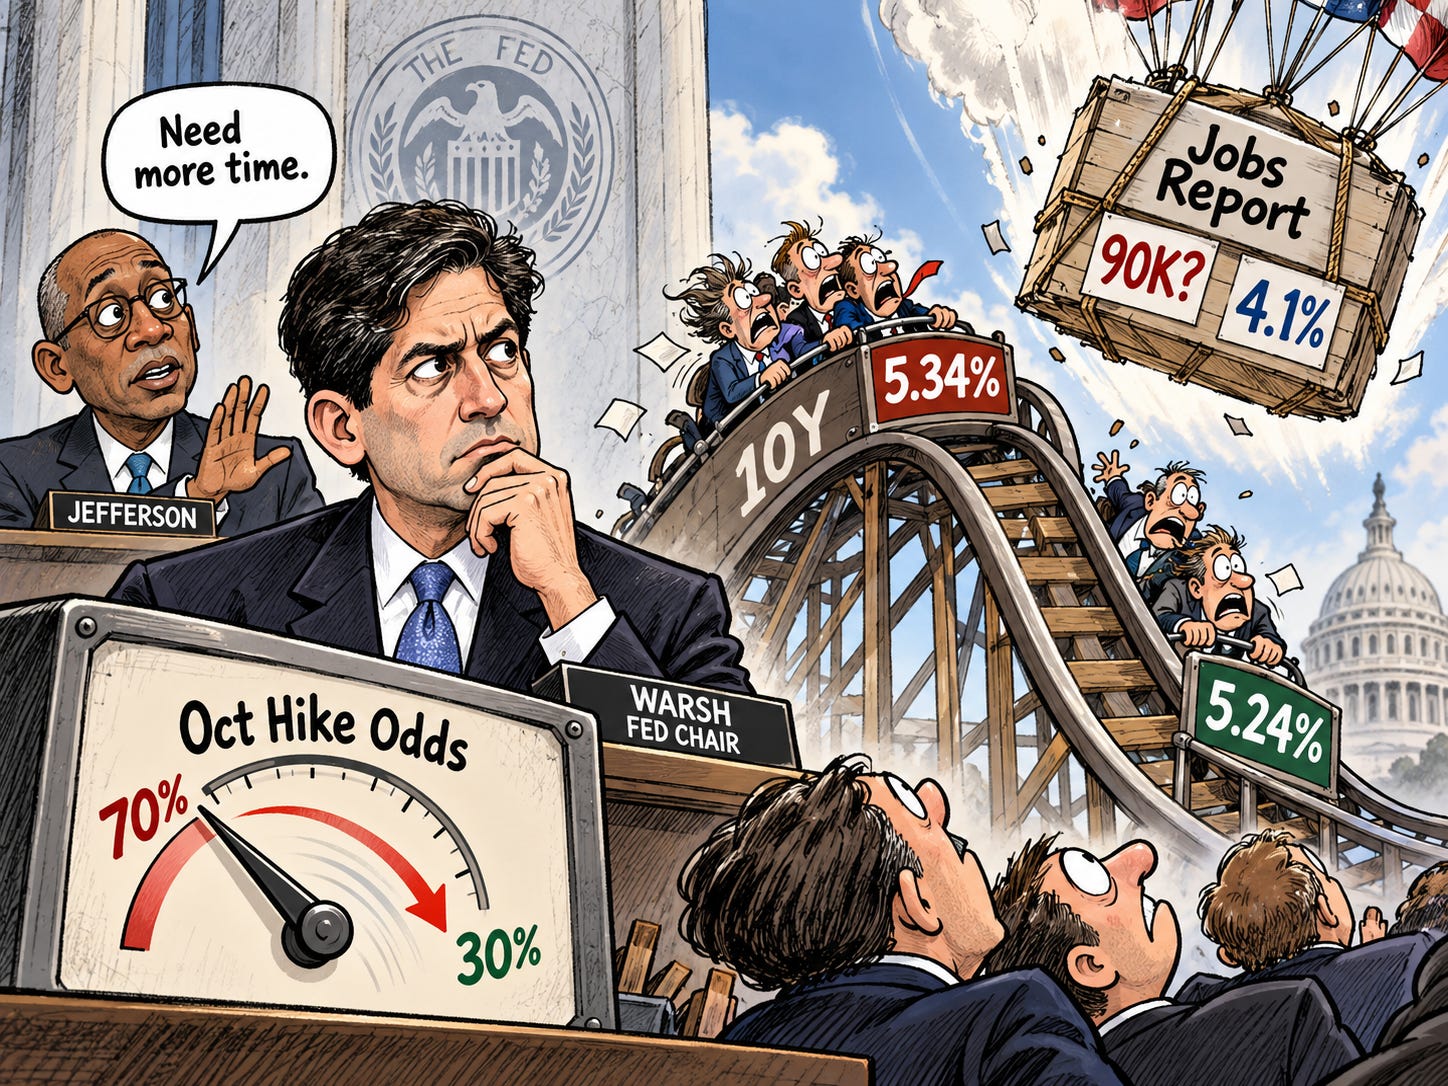
“My colleagues and I will need to come to our own judgment, which may take more time.” Fed Vice Chair Philip Jefferson said that at the University of Virginia on Thursday. The bond market had already started to move. The 10-year Treasury yield touched 5.34% on Thursday morning, its highest since 2002, and closed at 5.24%. Futures put the chance of a rate rise on 28 October at about 30% before Friday’s open, down from about 70% on Monday. Investing.com Yahoo Finance
September’s payrolls arrive at 1:30pm UK, which is 8:30am in New York. Economists expect about 90,000 new jobs, after 162,000 in August and 21,000 in July. Forecasts run from 35,000 to 180,000. Unemployment is expected to hold at 4.1%, and average hourly pay is seen up 0.3% on the month and 3.2% on the year. investingLive
Does September usually surprise? Analysts at BMO counted that the September headline has come in below estimates 64% of the time. It has also beaten estimates in each of the last 4 years.
The other side of the ledger landed on Thursday. The ISM survey showed the prices American factories pay jumped to 77.9 from 71.1, while overall activity eased to 54.5. That leaves the unemployment rate as the number most likely to settle October. TD Securities expects only about 50,000 jobs and a rise to 4.2%.
Sensei’s Insight: The bond market moved before the number did. A 10-year that went from 5.34% to 5.24% in one session tells me traders took Jefferson at his word. What I am watching at 1:30pm UK, 8:30am in New York, is the unemployment rate first and the headline second.
👟 Nike’s weaker year knocked 10% off the shares
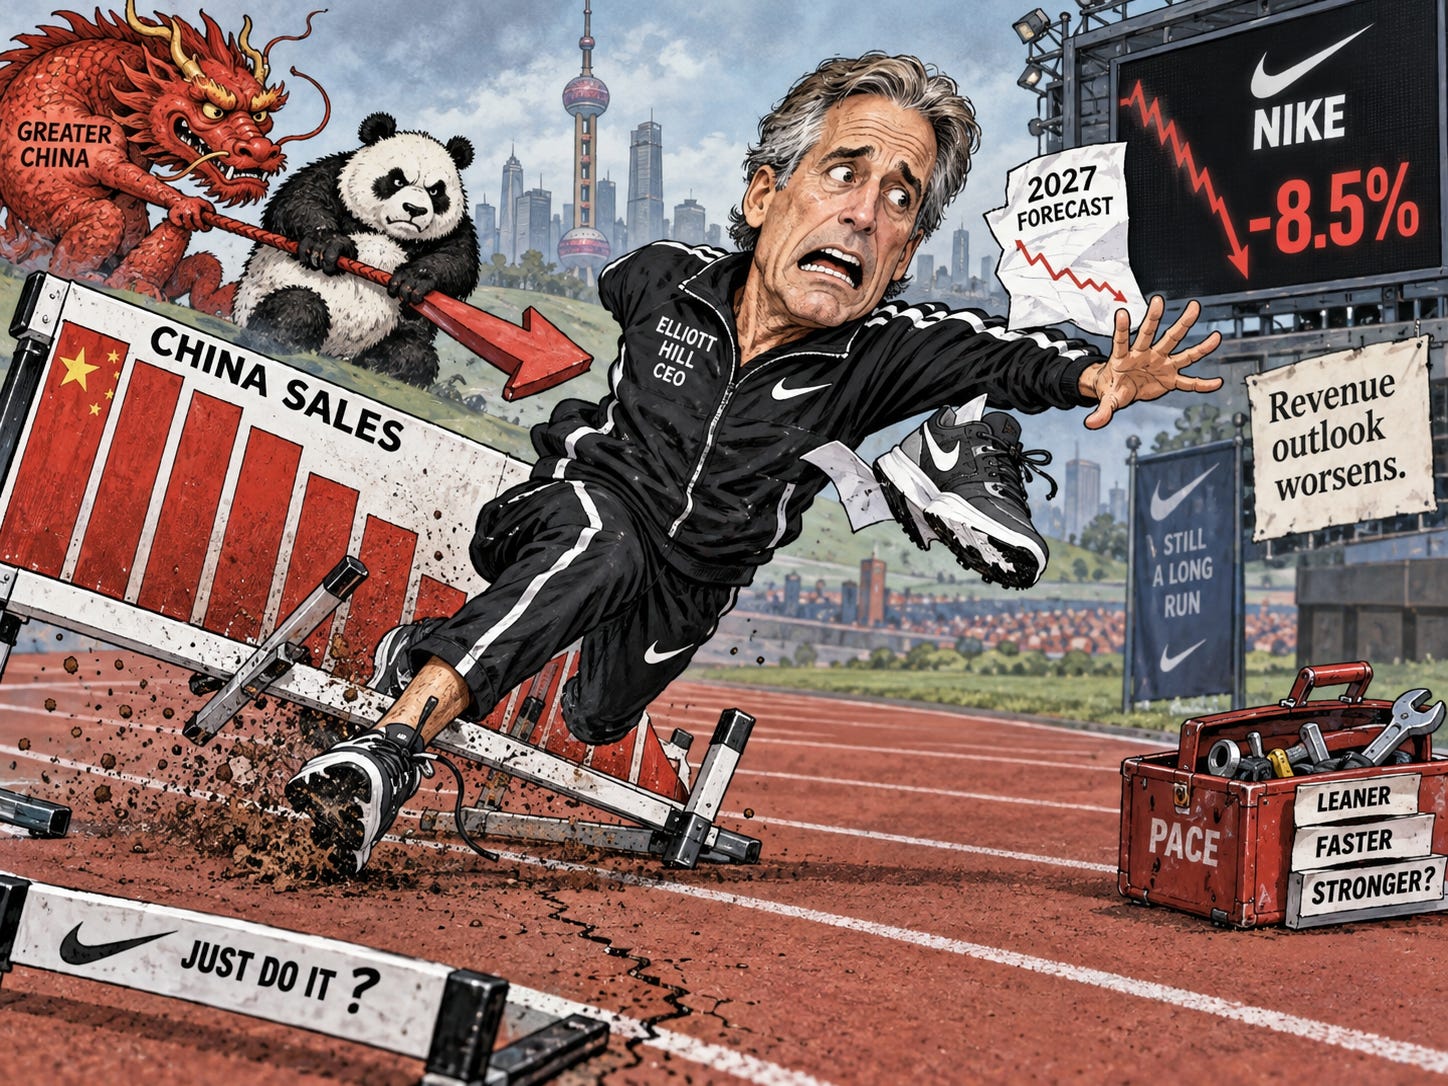
High single digits. That is how far Nike now expects revenue to fall in the year to May 2027, worse than the roughly 2% decline analysts had pencilled in. First-quarter revenue fell 4% to $11.21 billion, against $11.32 billion expected, while earnings of 48 cents a share beat the 43 cents forecast. The shares were down about 10% in pre-market trading on Friday. Grafa
Thursday’s edition named the gross margin as the number to watch. It rose 0.6 percentage points to 42.8%, and Nike credited lower warehousing and logistics costs. The release did not mention tariffs.
China did the damage. Greater China revenue fell 26% on a currency-neutral basis to $1.18 billion, which accounts for about two-thirds of the company’s total decline. Sales through Nike’s own stores and website fell 8%, and wholesale slipped 1%. Nike also launched a restructuring programme called Pace, aiming for $2.5 billion of savings by fiscal 2031, with job cuts and about $300 million of charges this year. Chief executive Elliott Hill said: “We have more work to do in NIKE Sportswear, Jordan Brand and Greater China, and we’re taking deliberate actions.” Yahoo Finance
Nike declined to give second-quarter guidance and will set out its next growth plan at an investor day on 16 and 17 November.
Sensei’s Insight: The margin did what Thursday’s edition asked of it, and the shares still fell, because the full-year guide got worse. China is now two-thirds of the problem. What I am watching is the November investor day, and whether it puts a number on China.
🇬🇧 Britain paid 6% to borrow for 30 years
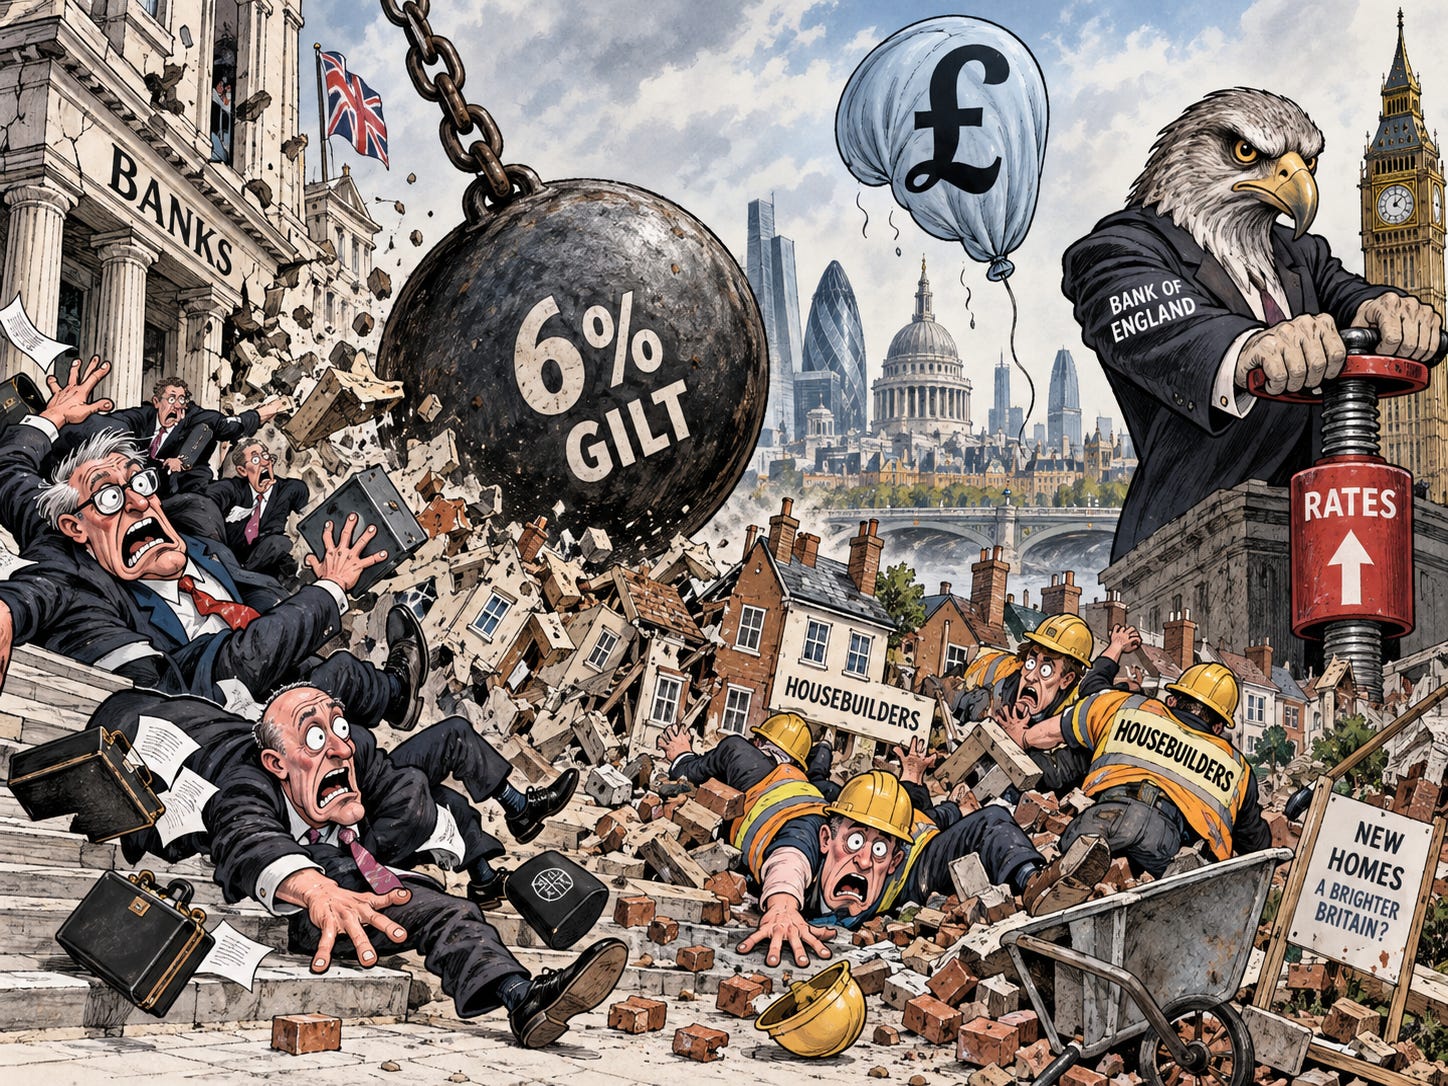
When did a British government last pay 6% to borrow for 30 years? February 1998. The 30-year gilt yield rose above 6% on Thursday and settled around 5.97%. The 10-year moved above 5.50% during the day, its highest since 2007. The FTSE 100 fell 177.73 points, or 1.68%, to 10,428.27, its steepest one-day fall since May. Share Talk Yahoo Finance
So who took the hit? Housebuilders and banks. Taylor Wimpey fell 5.5%, NatWest 5.4%, Bellway 5.3% and Persimmon 5.1%. Lloyds lost 4.5%, with traders worried about new taxes on banks in the 28 October Budget.
The pound fell below $1.32, its lowest since late June. A currency usually rises when its bond yields do. This time sterling and gilts were sold together, which points to investors pricing in more inflation risk. Bank of England policymaker Catherine Mann argued on Thursday for higher interest rates. Bank Rate sits at 3.75%, and the next decision is on 5 November.
The FTSE 100 opened 0.1% higher at 10,440.53 on Friday.
Sensei’s Insight: The US 10-year hit its highest since 2002 on the same day, so this was a global move. Britain’s version landed hardest on banks and housebuilders. What I am watching is the 30-year gilt yield, and any word on bank taxes before the 28 October Budget.
🛢️ Oil slipped below $100 on Europe’s diesel release talk
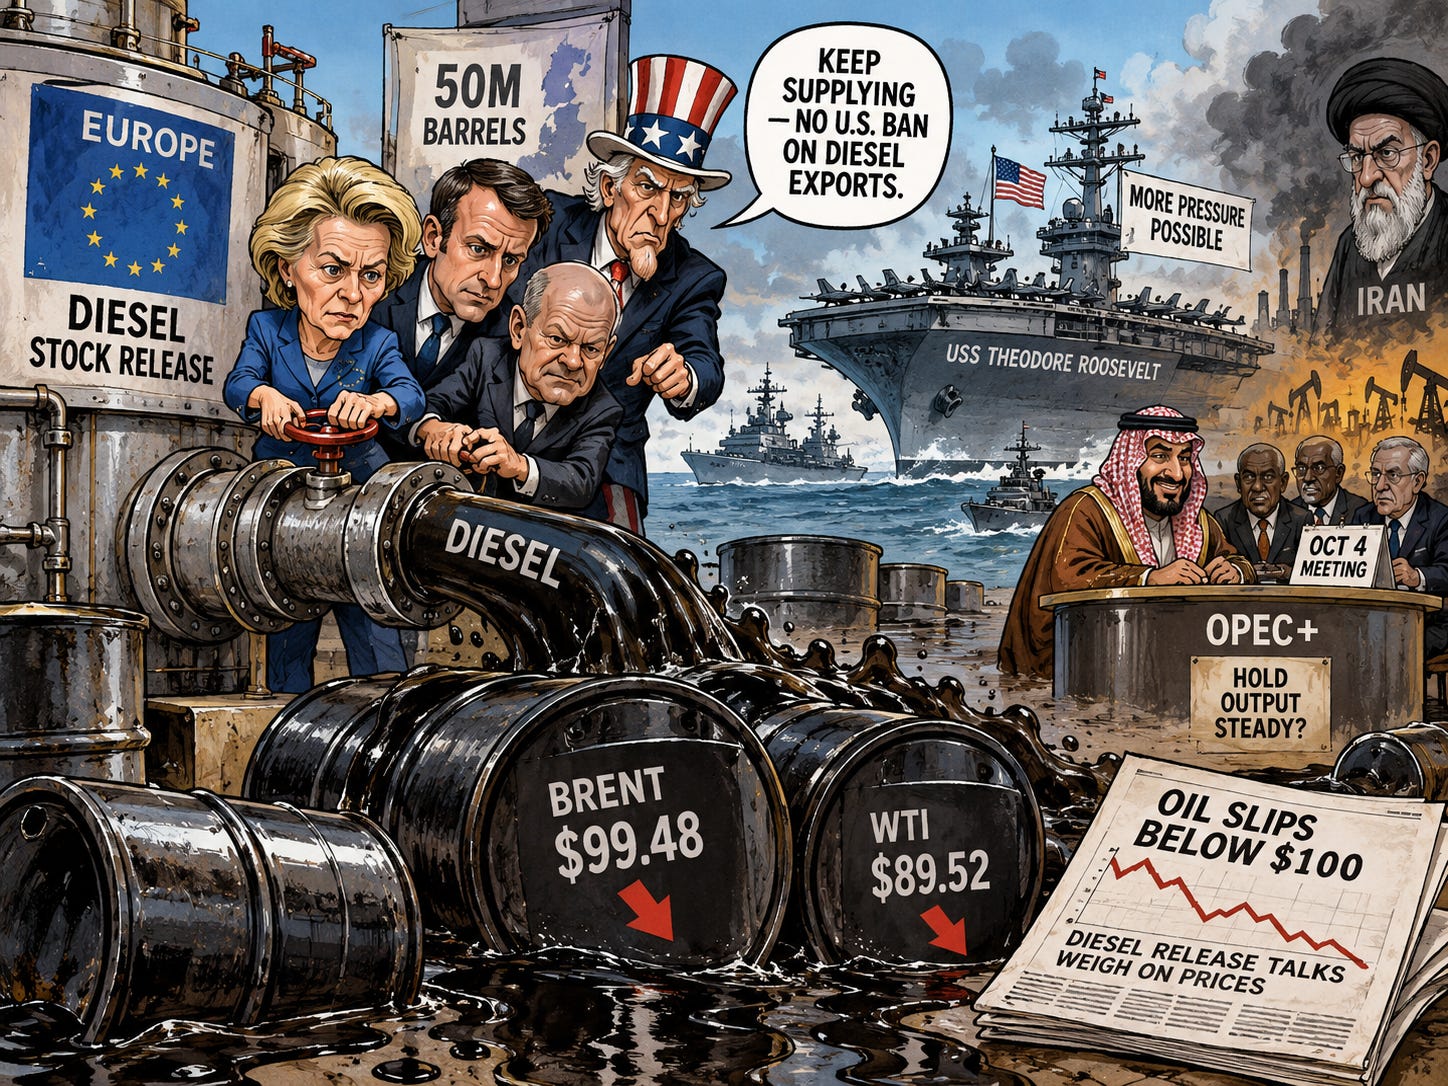
Brent crude fell 2.8% to $99.48 a barrel at 9:42am UK time on Friday, 4:42am in New York, and West Texas crude lost 3.6% to $89.52. Reuters reported that France had proposed releasing 50 million barrels of diesel across Europe and 50 million barrels of crude across members of the International Energy Agency. The talks followed pressure from Washington. One condition under discussion is a US commitment to avoid a unilateral ban on American diesel exports, and G7 leaders were due to speak on Friday afternoon. Investing.com
Why diesel? Because that is where the squeeze sits. Crude is moving again. Saudi Arabia shipped about 2.9 million barrels a day through Hormuz in September, up from about 1 million in August. Refined fuel is tighter, and China’s PetroChina held back October fuel shipments this week. “The whole energy complex trades lower, led by gasoil and ULSD,” said Ole Hansen of Saxo Bank. ULSD is the US diesel contract. Finwire
The military picture moved the other way. The carrier USS Theodore Roosevelt is heading for the region with about 10,000 sailors and Marines, Reuters reported, which would give the US 3 carrier groups there. President Trump has said heavier strikes on Iran are “possible” after November’s midterm elections. OPEC+ meets on Sunday 4 October and is expected to hold November output steady.
Sensei’s Insight: Crude recovered weeks ago. Fuel is the tight market, and now Europe’s governments are reaching for their own diesel tanks to ease it. What I am watching is the G7 call and Sunday’s OPEC+ meeting, with Brent down about 4.7% on the week.
💻 Accenture’s record deals eased the AI fear
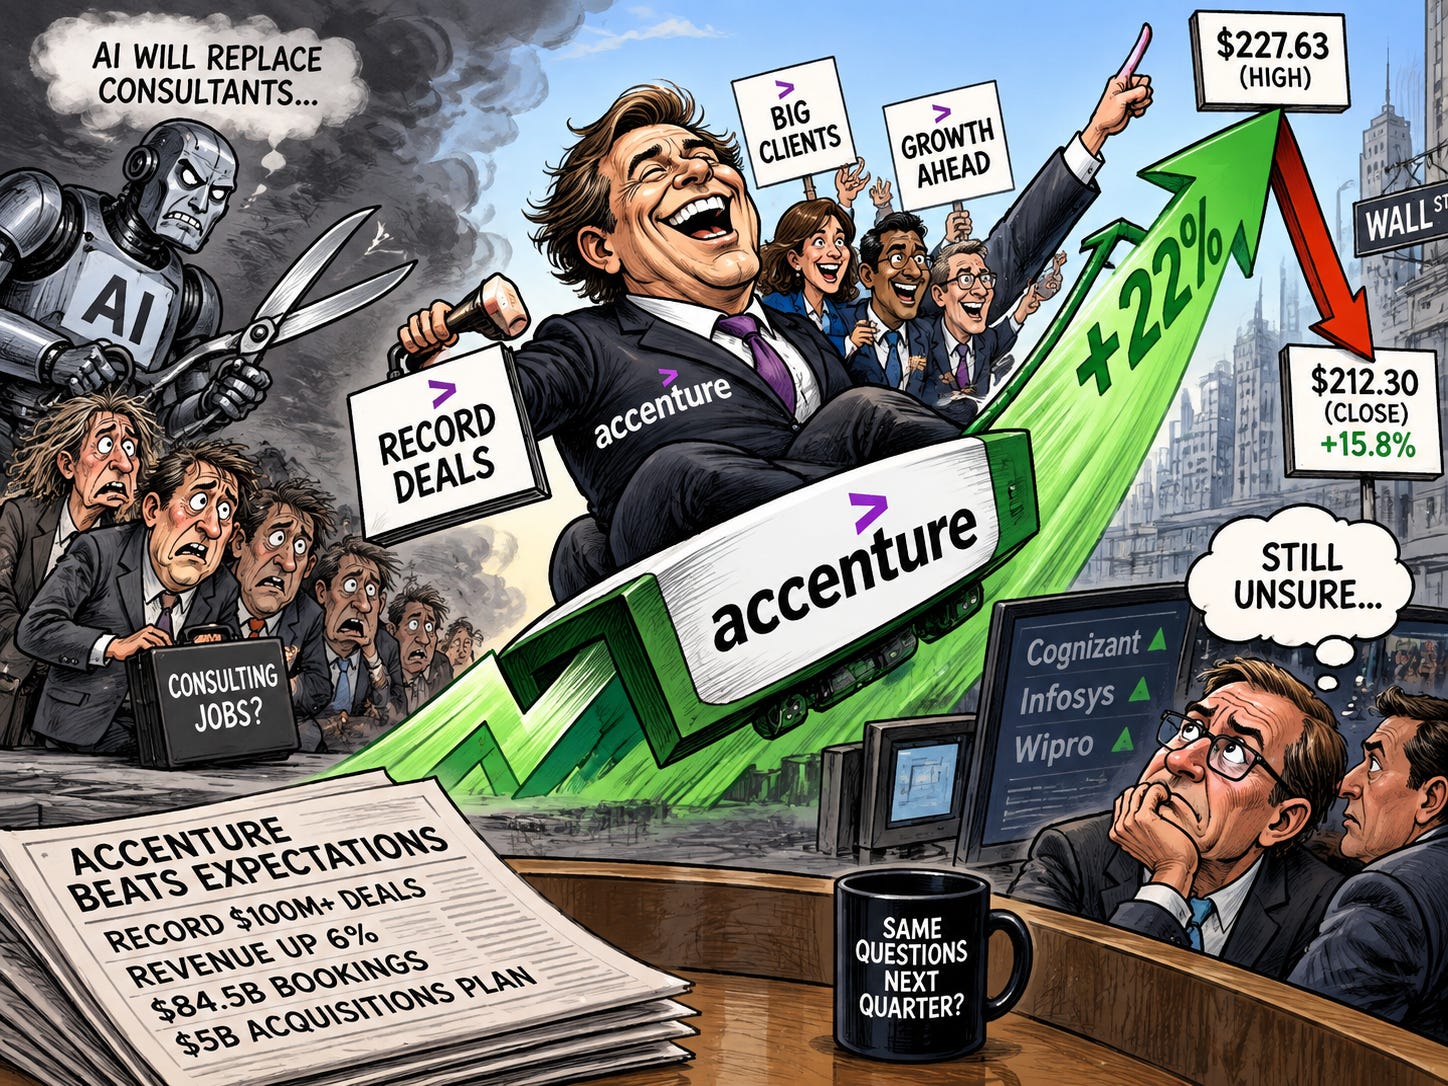
By mid-morning in New York on Thursday, Accenture shares were up more than 22%. They peaked at $227.63, about 24% above Wednesday’s close, and finished the day at $212.30, up 15.78%. Fourth-quarter revenue rose 6% to $18.70 billion against $18.03 billion expected. Earnings came in at $3.29 a share, against $3.18. The consulting group signed a record 141 deals worth $100 million or more in the quarter. Benzinga
The shares had fallen about 30% this year on one fear: that AI tools would automate the consulting and outsourcing work Accenture sells. The numbers pushed back on that. Bookings for the full year reached a record $84.5 billion. Accenture guided to revenue growth of 3% to 6% in local currency for the year ahead, against about 3.9% expected, and plans about $5 billion of acquisitions. Cognizant, Infosys and Wipro rallied with it. “Investors are quickly reevaluating their views,” said Steve Sosnick of Interactive Brokers. Yahoo Finance
The close came in well below the high. The shares gave back about a third of the day’s gain before the bell.
Sensei’s Insight: Record bookings answered the question investors had been asking all year about AI and consulting. A close well below the high says plenty of them are still unsure. What I am watching is the next quarter’s guide of $18.95 billion to $19.60 billion against the $19.36 billion analysts expect.
Stories You Might Have Missed
🇪🇺 Eurozone inflation jumped to 3.8%
Prices across the euro area rose 3.8% over the year to September, Eurostat’s flash estimate showed on Friday, above the 3.6% economists expected and up from 3.2% in August. It is the highest rate since September 2023. Energy did most of the work. Energy prices rose 18.8% on the year, up from 14.3%, adding about 1.7 percentage points to the headline. Core inflation, which strips out food and energy, edged up to 2.5% as forecast. Lithuania had the highest rate at 6.1%. The European Central Bank raised its deposit rate to 2.50% in September and meets again on 28 and 29 October. Euronews
🪙 Bitcoin climbed back above $86,000
Bitcoin traded at $86,443 at 9:19am UK time on Friday, 4:19am in New York, up 3.49% over 24 hours, CoinDesk data showed. The fund buyers came back too. US spot bitcoin ETFs took in a net $102.7 million on Thursday, after Wednesday’s $148.7 million outflow ended a 9-day buying streak. BlackRock’s fund drew $195.6 million while Fidelity’s lost $60.7 million. Bitcoin rose about 43% in the third quarter, its strongest quarter since the end of 2024, on $6.34 billion of fund inflows. Farside Investors CoinDesk
🏛️ Crypto Mom leaves the SEC
Hester Peirce, the SEC commissioner the crypto industry nicknamed Crypto Mom, leaves the agency on Friday 2 October after nearly 9 years. She ran the SEC’s crypto task force from February 2025. Her exit leaves 2 commissioners, Chair Paul Atkins and Mark Uyeda, and the White House has not named a successor. The CLARITY Act, the bill that would split oversight of digital assets between the SEC and the CFTC, is still stalled in the Senate. Peirce joins Regent University’s law school as an associate professor in November. Yahoo Finance
📱 New Mexico wants up to $40 billion from Meta
New Mexico has asked a judge to order Meta to pay $35 billion to $40 billion in penalties, Reuters reported. A Santa Fe jury found on 25 September that 26 of 29 company statements were misleading, and that Meta committed more than 43 million violations of the state’s consumer protection law. The law allows up to $5,000 per violation. Meta proposed a cap of $3.45 billion and called the state’s figure “astronomical”. Judge Francis Mathew is expected to rule later in October. Meta’s shares were marginally higher in pre-market trading. Investing.com
🔍 Deep Dive - The 4.1% Question: The September Jobs Report Cheat Sheet
The number lands at 1:30pm BST, 8:30am ET.
For a year, American employers have added only about 50,000 jobs a month, and unemployment has still fallen, from 4.5% last November to 4.1%. Fewer new workers are joining the jobs market, so it takes far fewer hires to keep it steady. That’s why I’m reading the unemployment rate first and the headline second. Our Cheat Sheet sets out what lands and when, what each result would mean for the 28 October Fed decision, the numbers that sound alarming and mean little, and the dates that decide October.
You can click the link below to download our Cheat Sheet PDF.