

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
👀 Today’s Stories at a Glance
💼 The revisions hit harder: September added 29,000 jobs, July turned into a 10,000 loss, and October hike odds fell to about 18%.
🛢️ Brent holds above $100: the G7 agreed a 100 million barrel release and OPEC+ held steady, and Brent still traded at $101.59 on Monday.
🏭 Schneider buys PTC: a $22.6 billion cash deal at a 42.3% premium, and Schneider’s own shares fell more than 7% in Paris.
💾 Toshiba hits the drive makers: a plan to double hard-drive output knocked about 10% off Seagate and Western Digital on Friday.
🇧🇷 Brazil heads to a runoff: Flávio Bolsonaro took 47.04% to Lula’s 45.15%, beating the polls, and the 2 meet again on 25 October.
🇯🇵 Nikkei tops 70,000: Japan’s index rose 2.53% to its highest close since early July as chip stocks followed Nvidia’s record.
🇬🇧 UK services raise prices: firms raised prices at the fastest pace since May on fuel costs, with the services PMI at 52.1.
📶 BT rescues TalkTalk: a £400 million deal brings 2.5 million customers, and the competition watchdog reports by 19 October.
🚗 Musk talks to TSMC: Musk confirmed talks with TSMC over the Texas Terafab chip project, saying “something may come of it”.
📈 The 10-year shrugged off payrolls: Chart of the Day covers the 5.02% breakout line, the 5.34% high and Sensei’s Momentum Band near 4.75%.
🧠 One Big Thing
America’s jobs market is weaker than it looked a week ago. Employers added 29,000 jobs in September, and July’s figure was revised to a loss of 10,000. Unemployment rose to 4.2%. That is why futures now put the chance of a Fed rate rise on 28 October at about 18%, down from about 70% at the start of last week. Prices have not cooled with it. The prices American factories pay jumped to 77.9 in September from 71.1. Wednesday’s minutes of the September meeting and September’s inflation figures on 14 October are the 2 dated things that decide whether the Fed waits.
⚖️ Fear & Greed

📉 The Number That Matters
-10,000
July’s jobs figure now shows a loss of 10,000, revised on Friday from a first reported gain of 21,000. September’s 29,000 landed on top of it, and October hike odds fell to about 18%.
⚔️ Winners vs Losers
🟢 Top Gainers
PCVX 0.00%↑ : +46.95% Vaxcyte, Inc. shares soared after its 31-valent pneumococcal vaccine VAX-31 met every primary endpoint in the pivotal OPUS-1 Phase 3 adult trial, matching Prevnar 20 and Capvaxive on all 28 shared serotypes and beating them on the 3 serotypes only VAX-31 covers. The company plans to file for US approval in the first half of 2028.
PTC 0.00%↑ : +37.47% PTC Inc. shares jumped after Schneider Electric agreed to buy the industrial software maker for $205 per share in cash, a 42.3% premium that values the deal at $22.6 billion. Both boards approved it unanimously, and it is expected to close by the third quarter of 2027.
XP 0.00%↑ : +15.02% XP Inc. shares rallied alongside other US-listed Brazilian stocks after Flávio Bolsonaro beat the polls to lead the first round of Brazil’s presidential election with 47% of valid votes. Investors are pricing in a more business-friendly government ahead of the 25 October runoff, and as a brokerage XP has outsized exposure to a domestic equity rally.
🔴 Top Losers
INTC 0.00%↑ -4.06% Intel Corporation shares fell after reports that TSMC is in talks to own and operate Elon Musk's Terafab chip plant in Texas, which threatens Intel's position as the project's sole named process technology partner. Susquehanna added pressure by estimating that Intel lost more CPU market share in the third quarter, with its laptop share down 3.9 points to 68.1%.
📊 Market Snapshot
Cryptocurrencies:
Bitcoin (BTC): $86,101 (▼0.48%)
Ethereum (ETH): $2,719 (▼0.27%)
XRP: $1.52 (▼0.15%)
Equity Indices (Futures):
S&P 500: 7,763 (▼0.18%)
NASDAQ 100: 30,983 (▼0.25%)
FTSE 100: 10,481 (▼0.14%)
Commodities & Bonds:
10-Year US Treasury Yield: 5.29% (▲0.25%)
Oil (WTI): $91 (▼0.68%)
Gold: $4,159 (▲0.38%)
Silver: $61.68 (▲2.04%)
Data as of: UK: 11:28 am BST / US: 6:28 am EDT / Asia (Tokyo): 7:28 pm JST
✅ 5 Things to Know
💼 The jobs revisions said more than September did
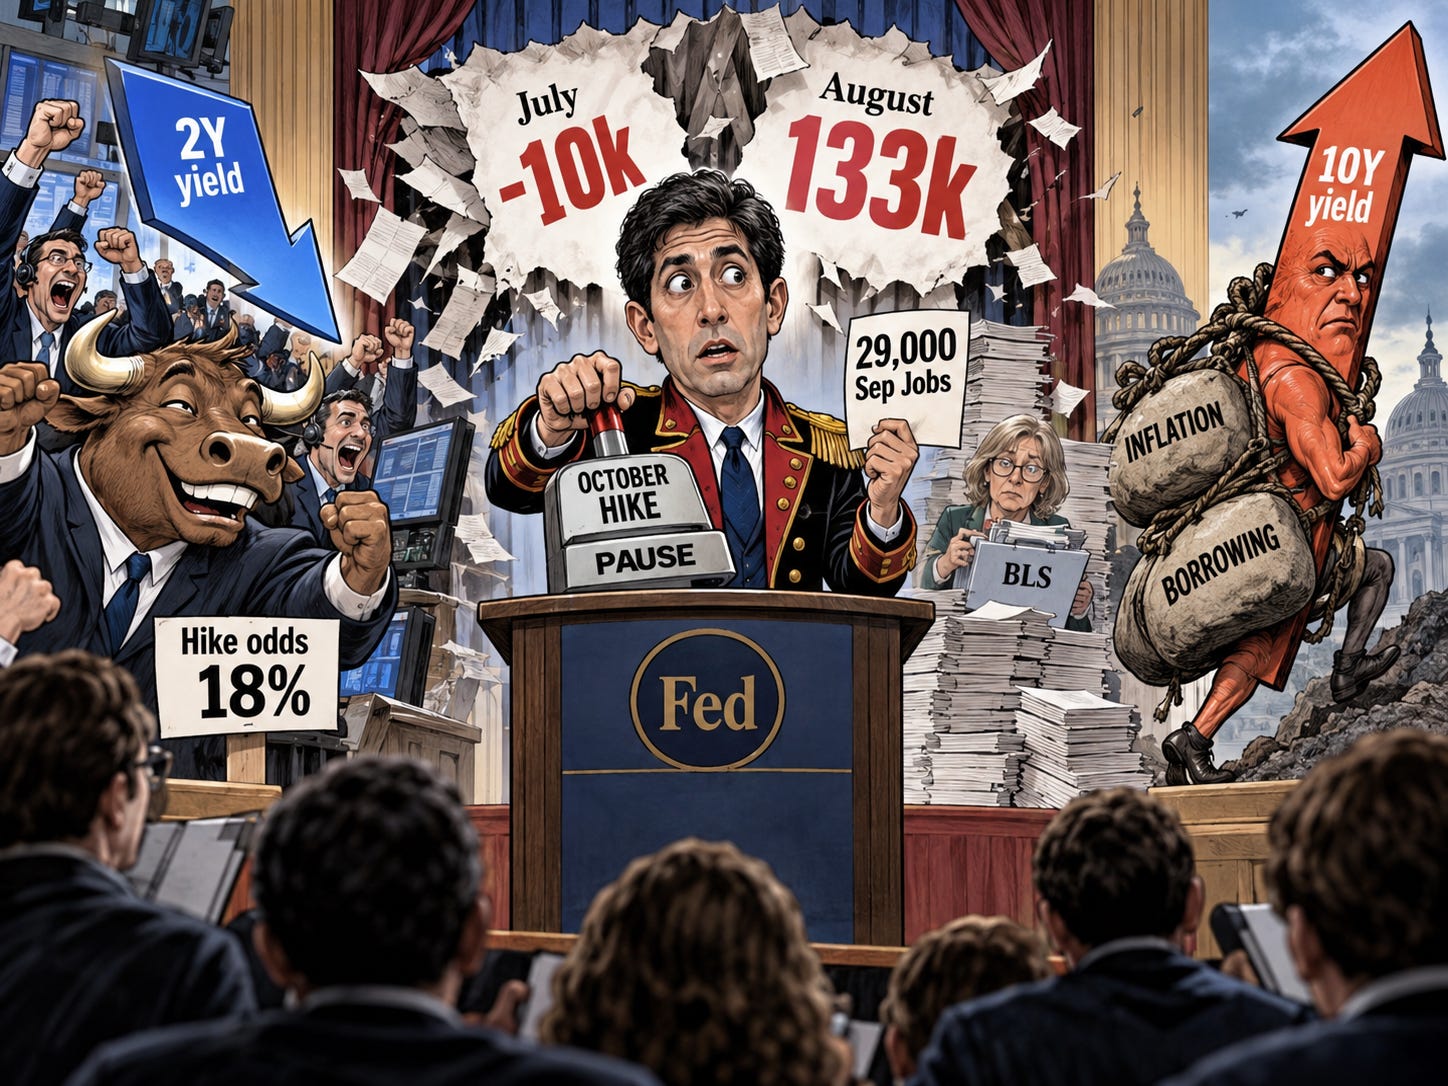
29,000. That is how many jobs American employers added in September, the Bureau of Labor Statistics said on Friday, against forecasts of 84,000 to 90,000. The revisions hit harder. July was cut from a gain of 21,000 to a loss of 10,000, and August from 162,000 to 133,000. Unemployment rose to 4.2% from 4.1%, and average hourly pay rose just 0.1% on the month, or 3.0% on the year. BLS
Add the 3 months together and employers created about 152,000 jobs, roughly 51,000 a month. Markets read that as the end of an October rate rise. CME FedWatch put the odds at about 18% after the report, TheStreet reported, down from about 70% at the start of last week. The 2-year Treasury yield, the one most tied to Fed expectations, fell about 10 basis points. The S&P 500 closed up 0.73% at 7,722.72, and the Nasdaq gained about 1.2%. TheStreet FNArena
The 10-year went the other way. It dipped to about 5.16% straight after the release, then turned and finished Friday near 5.28%, close to Thursday’s 5.34%, its highest since 2002. Short rates priced out the Fed. Long rates held on to inflation and government borrowing. CNBC
So what settles it from here? The services side of the economy, first. The ISM services survey lands at 3pm UK, which is 10am in New York, with forecasts running from 54.5 to 55.7 after 55.4 in August. Its employment index was 47.8 in August, below the 50 line that separates firms hiring from firms cutting. FXStreet
The minutes of the September Fed meeting follow on Wednesday, and September’s inflation figures on 14 October.
Sensei’s Insight: The headline was weak and the revisions were weaker, so an October rise went from likely to unlikely inside a week. The 10-year still ended the day higher. What I am watching at 3pm UK, 10am in New York, is the services employment index, after 47.8 in August.
🛢️ 100 million barrels, and Brent still sits above $100
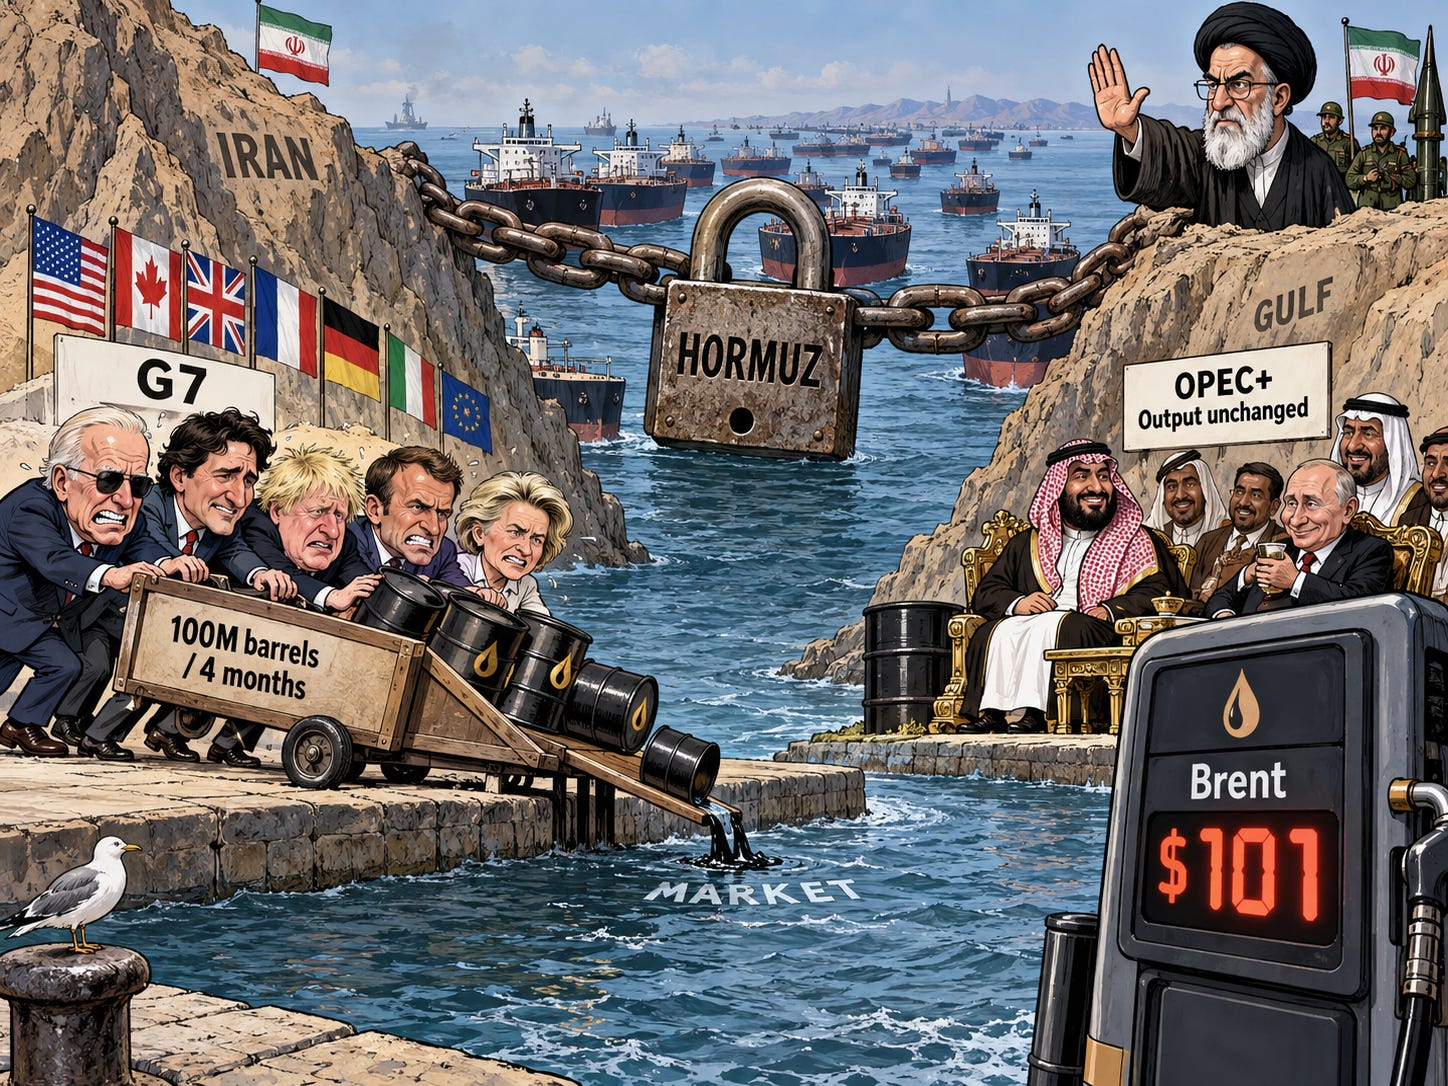
Brent crude traded at $101.59 a barrel at 7:34am UK time on Monday, down 0.71%, Reuters reported, and West Texas crude slipped 1.2% to $90.05. On Friday the G7 agreed to release 100 million barrels of diesel and crude from emergency stocks over 4 months, with a large diesel release in the first 20 days. On Sunday OPEC+ left its November output targets unchanged and set its next meeting for 1 November. Euronext The National
How big is 100 million barrels? Spread over 4 months, it works out at roughly 830,000 barrels a day. The Strait of Hormuz, effectively shut since the war began on 28 February, normally carries about a fifth of the world’s crude and liquefied natural gas. Producers have found their own way round part of the gap. Middle East crude exports rose above pre-war levels on 4 of the 7 days in the last week of September, Reuters reported, and most OPEC+ members are already pumping below their quotas. The National
Iran restated its terms on Sunday. “The era of wasting time and dictating unilateral demands is over,” said parliament speaker Mohammad Bagher Ghalibaf, and the strait stays shut until Washington meets 7 conditions set out in June. In Britain, the Pentagon pulled all its bombers from RAF Fairford in Gloucestershire after police arrested a 25-year-old in London on suspicion of planning an attack on the base. Al Jazeera
Sensei’s Insight: Governments have added supply and the producers have held theirs steady, and Brent is still above $100. That tells me the strait sets the price. What I am watching is whether the first 20 days of the diesel release pull fuel prices down faster than crude.
🏭 Schneider pays $22.6 billion for PTC, and its own shares fell
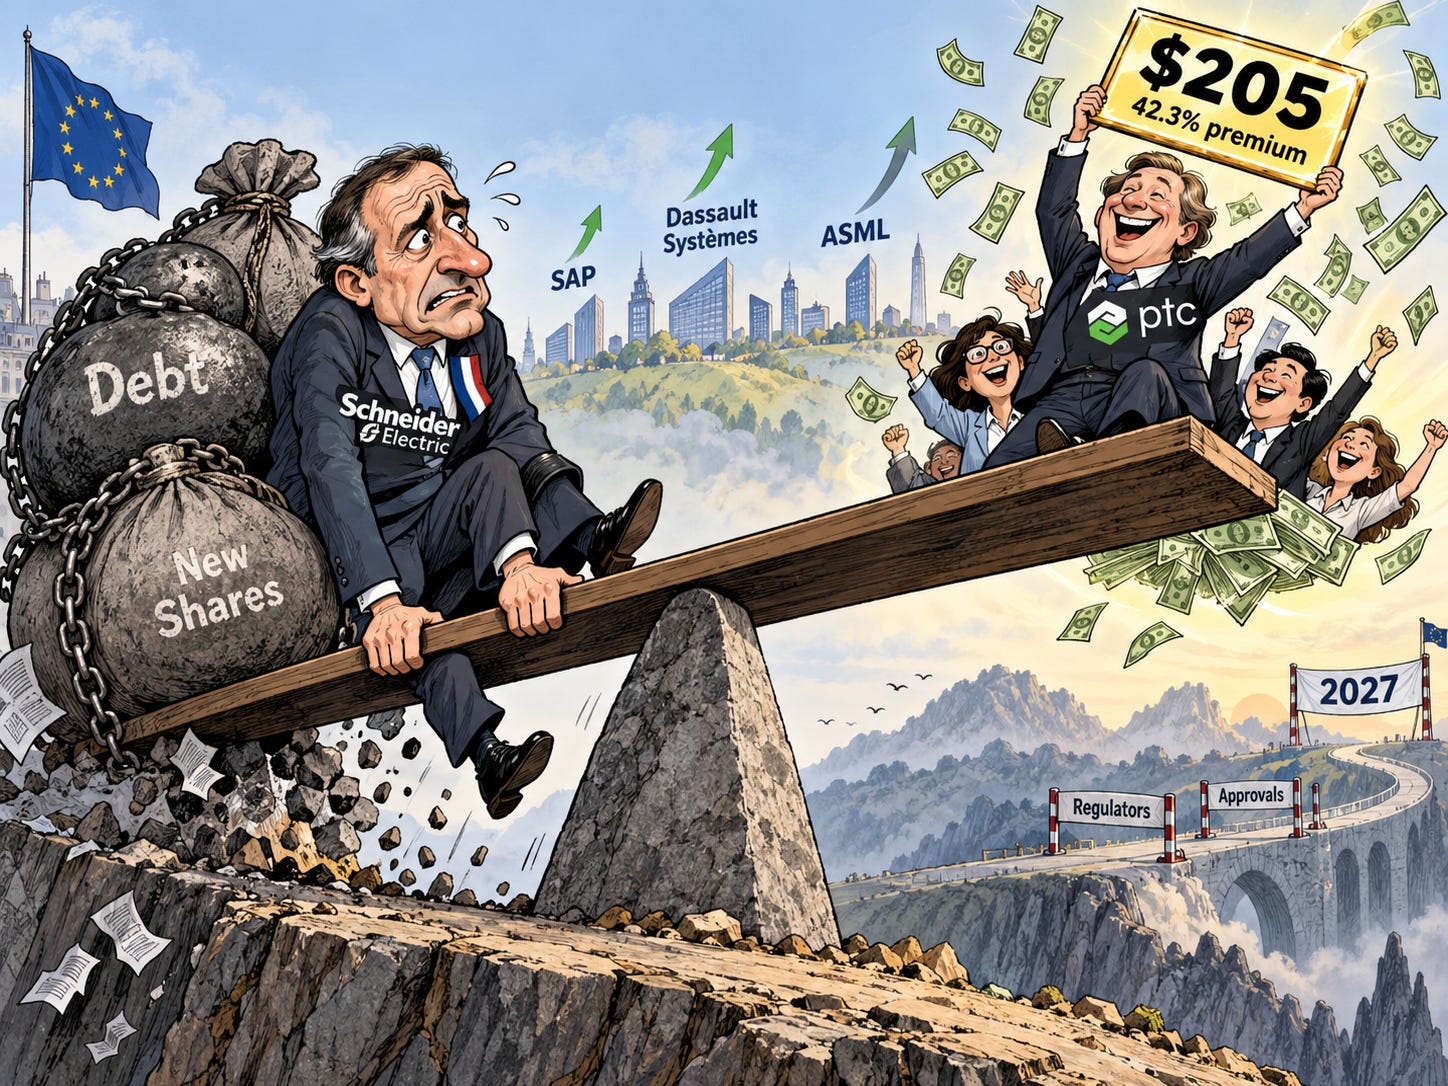
$205 a share, in cash. That is what France’s Schneider Electric agreed on Monday to pay for PTC, the American maker of software used to design and manage industrial products. The price is 42.3% above PTC’s Friday close of $144.03 and values the company at about $22.6 billion, or $23.7 billion including debt. It is Schneider’s biggest acquisition. PTC shares jumped more than 34% before the US open, while Schneider fell more than 7% in Paris. Yahoo Finance
Why did the buyer fall? Schneider is funding the deal with up to €6 billion of new shares and about €17 billion of new debt, backed by a bridge loan from Morgan Stanley and Société Générale. New shares dilute existing holders, and the debt adds interest costs. Schneider expects about €250 million a year of cost savings and roughly €800 million of extra revenue by year 3, and says the deal adds to earnings per share in its first full year. Investing.com
The rest of Europe’s software makers rose with PTC. Dassault Systèmes gained 2.3%, Nemetschek 1.9% and TeamViewer 3.2%. “The strategic rationale for SU is very clear,” said Jefferies analyst Lucas Ferhani, using Schneider’s Paris ticker. The deal needs regulatory approval and is expected to close by the third quarter of 2027. Investing.com
Sensei’s Insight: The seller’s shareholders got a 42.3% premium and the buyer’s lost about 7% in a morning. What I am watching is the gap between PTC’s share price and the $205 offer. That gap is the market’s read on the deal closing by late 2027.
💾 A rival’s plan knocked 10% off the hard-drive makers
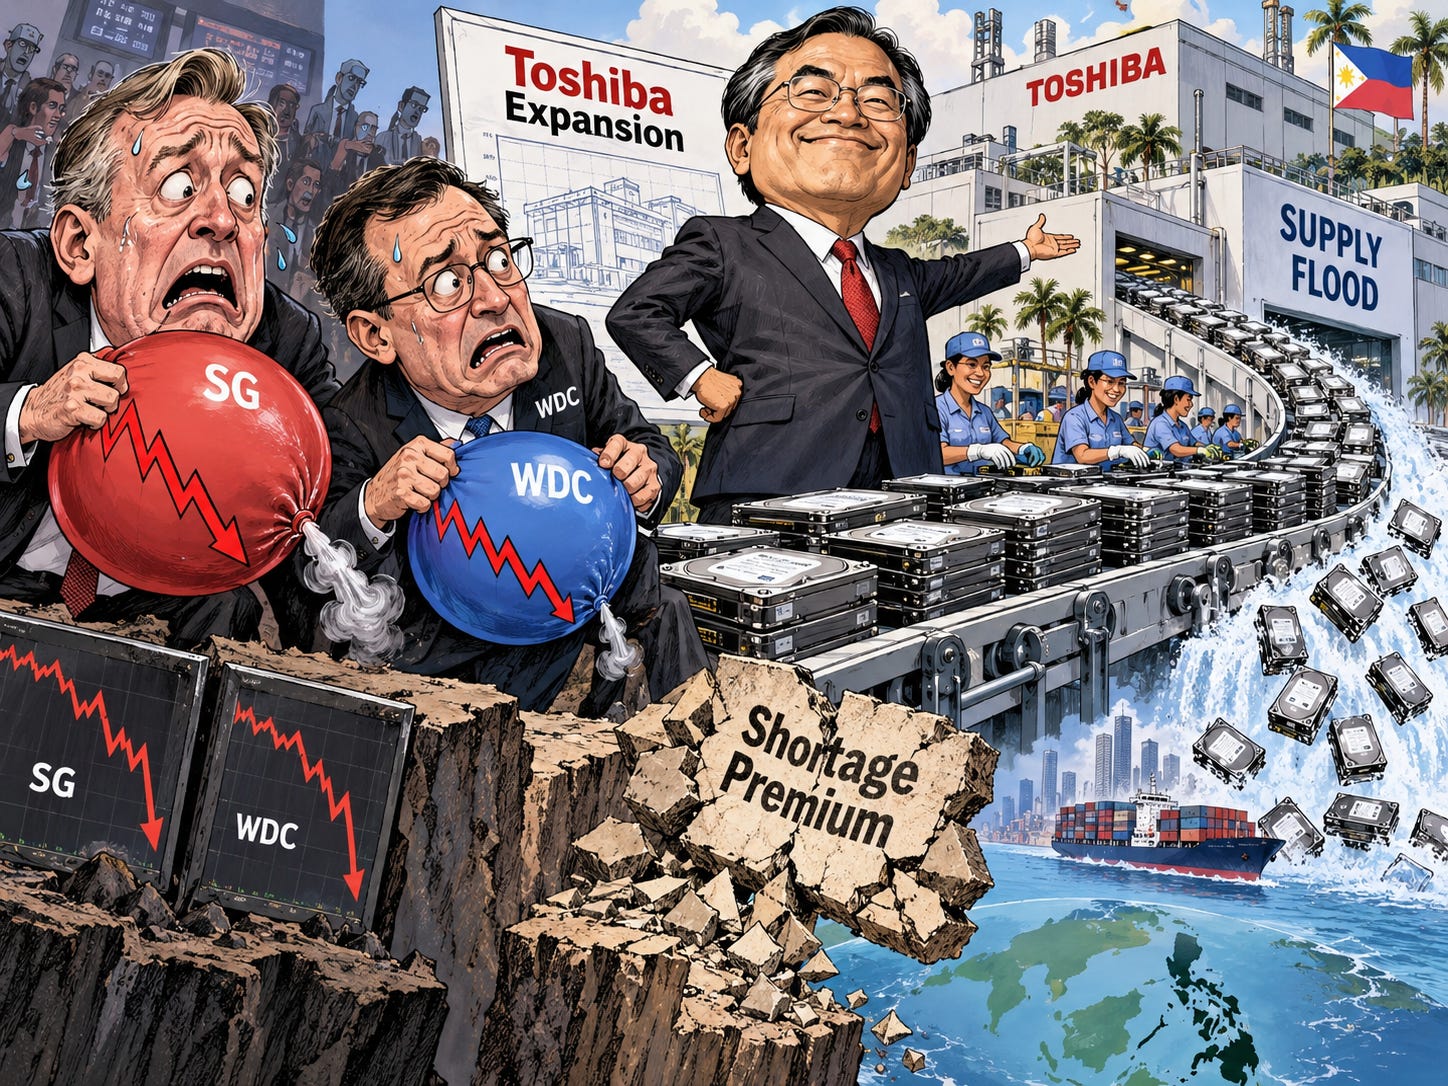
What happens to a shortage trade when a rival builds more? This one lost about 10% in a day. Toshiba plans to spend about ¥60 billion, roughly $400 million, to double its hard-drive output by its 2027 financial year, mostly at its factory in the Philippines, the Nikkei reported on Friday. Seagate closed down 9.96% at $851.39 and Western Digital down 10.07% at $415.97, on a day the Nasdaq rose about 1.2%. Investing.com 24/7 Wall St.
Both companies built their run on tight supply. Western Digital’s chief executive had said the shortage gave it “an opportunity for increased pricing leverage”. Toshiba holds just over 10% of the market by storage capacity and is aiming for about 30%. Seagate had more than tripled this year before Friday, and Western Digital had more than doubled.
Citi analyst Asiya Merchant pushed back. She said “the market may be overstating the impact,” because Toshiba relies on outside suppliers for key parts such as disks and recording heads. Seagate’s capacity for its big data-centre drives is also nearly fully allocated through 2027 under long-term contracts. 24/7 Wall St.
Sensei’s Insight: A plan costing about $400 million took far more than that off 2 companies’ market values in one session. That tells me how much of the price rested on the shortage lasting. What I am watching is whether Toshiba can source the heads and disks to deliver it.
🇧🇷 Brazil’s polls missed and the runoff is set for 25 October
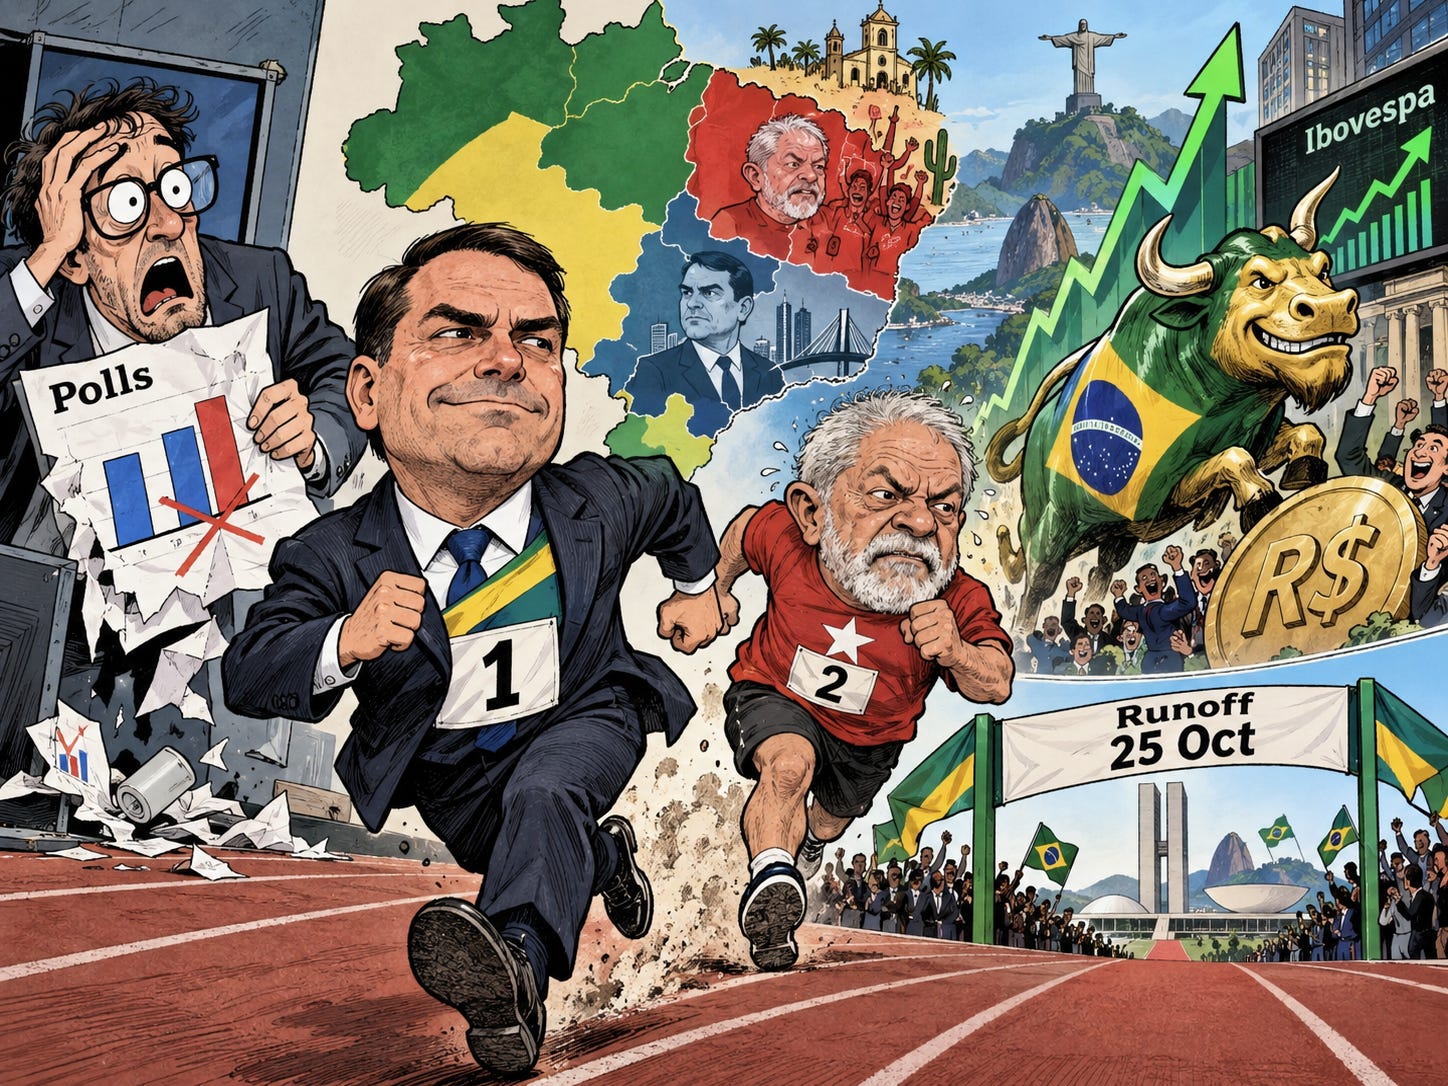
Flávio Bolsonaro won 47.04% of valid votes in Sunday’s first round, ahead of President Luiz Inácio Lula da Silva on 45.15%, with 99.96% counted. Pre-election polling had favoured Lula. Neither reached 50%, so the 2 meet again on Sunday 25 October. Flávio, the eldest son of former president Jair Bolsonaro, won São Paulo and Rio de Janeiro, while Lula swept the northeast. Abstention hit 21.08%, the highest in a first round since 1998. Rio Times
Brazilian markets open at 2pm UK, 9am in New York, and analysts expect a rally. “Investors will wake up on Monday to a very powerful rally across asset classes,” said Ivo Chermont, chief economist at Quantitas, who pencilled in a 2% to 4% fall in the dollar against the real and a 4% to 6% rise in stocks. The 2022 base rate points the same way. After Jair Bolsonaro beat his first-round polls against Lula that year, the real strengthened more than 4% and the Bovespa jumped 5.5%. Lula went on to win that runoff. Investing.com
The Ibovespa had already climbed 2.63% to 192,114.55 on Friday, and the real closed at R$5.21 per dollar.
Sensei’s Insight: Brazil’s market has priced a change of government before. In 2022 it rallied on the first round and Lula won the runoff anyway. What I am watching is how much of the open holds by the close, with 3 weeks to go until 25 October.