

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
👀 Today’s Stories at a Glance
🏦 American borrowing costs touch 5%: the 10-year Treasury yield hit a level last seen in 2007 before the Fed sat down.
🇨🇳 China’s factories ran, its shoppers did not: retail sales grew 0.4% in August, output rose 5.2%, investment fell 7.2%.
🏛️ The crypto bill faces its first Senate vote: cloture needs 60 votes later today, and Republicans hold 53 of 100 seats.
🇬🇧 Britain shed jobs at the fastest rate in 9 months: payrolls fell 26,000 in August, 2 days before the inflation print.
🛢️ Hormuz is down to 10 ships a day: about 130 crossed daily before the war, and Brent is trading above $107.
💻 Monday’s chip selloff did not carry into Tuesday: the semiconductor index fell 5.9%, then futures turned positive overnight.
💵 The dollar had its strongest day in months: the euro fell to a 1-month low of $1.15 as yields climbed everywhere.
🥇 Gold gave ground while oil kept running: bullion fell to about $4,282 an ounce and silver to $63.17 on Tuesday.
🩺 GSK rose 3.6% on 2 cancer trials: European healthcare gained 2.2% on a day technology shares lost 2.1%.
📈 Coinbase is stuck in a $60 range: Chart of the Day covers $210, $200, $150 and the $114 shelf.
🧠 One Big Thing
The American government’s cost of borrowing for 10 years touched 5% on Monday and went higher again on Tuesday, to 5.04%, a level last seen in 2007. That yield is the reference point for company debt and home loans across the world’s largest economy, and it moved before the Federal Reserve had said anything at all. That took 2 forces. Brent crude above $107 a barrel is pushing inflation expectations up, and Washington is borrowing heavily into a market that already has plenty of bonds to absorb. The Fed decides on Wednesday at 2:00pm in New York, which is 7:00pm UK.
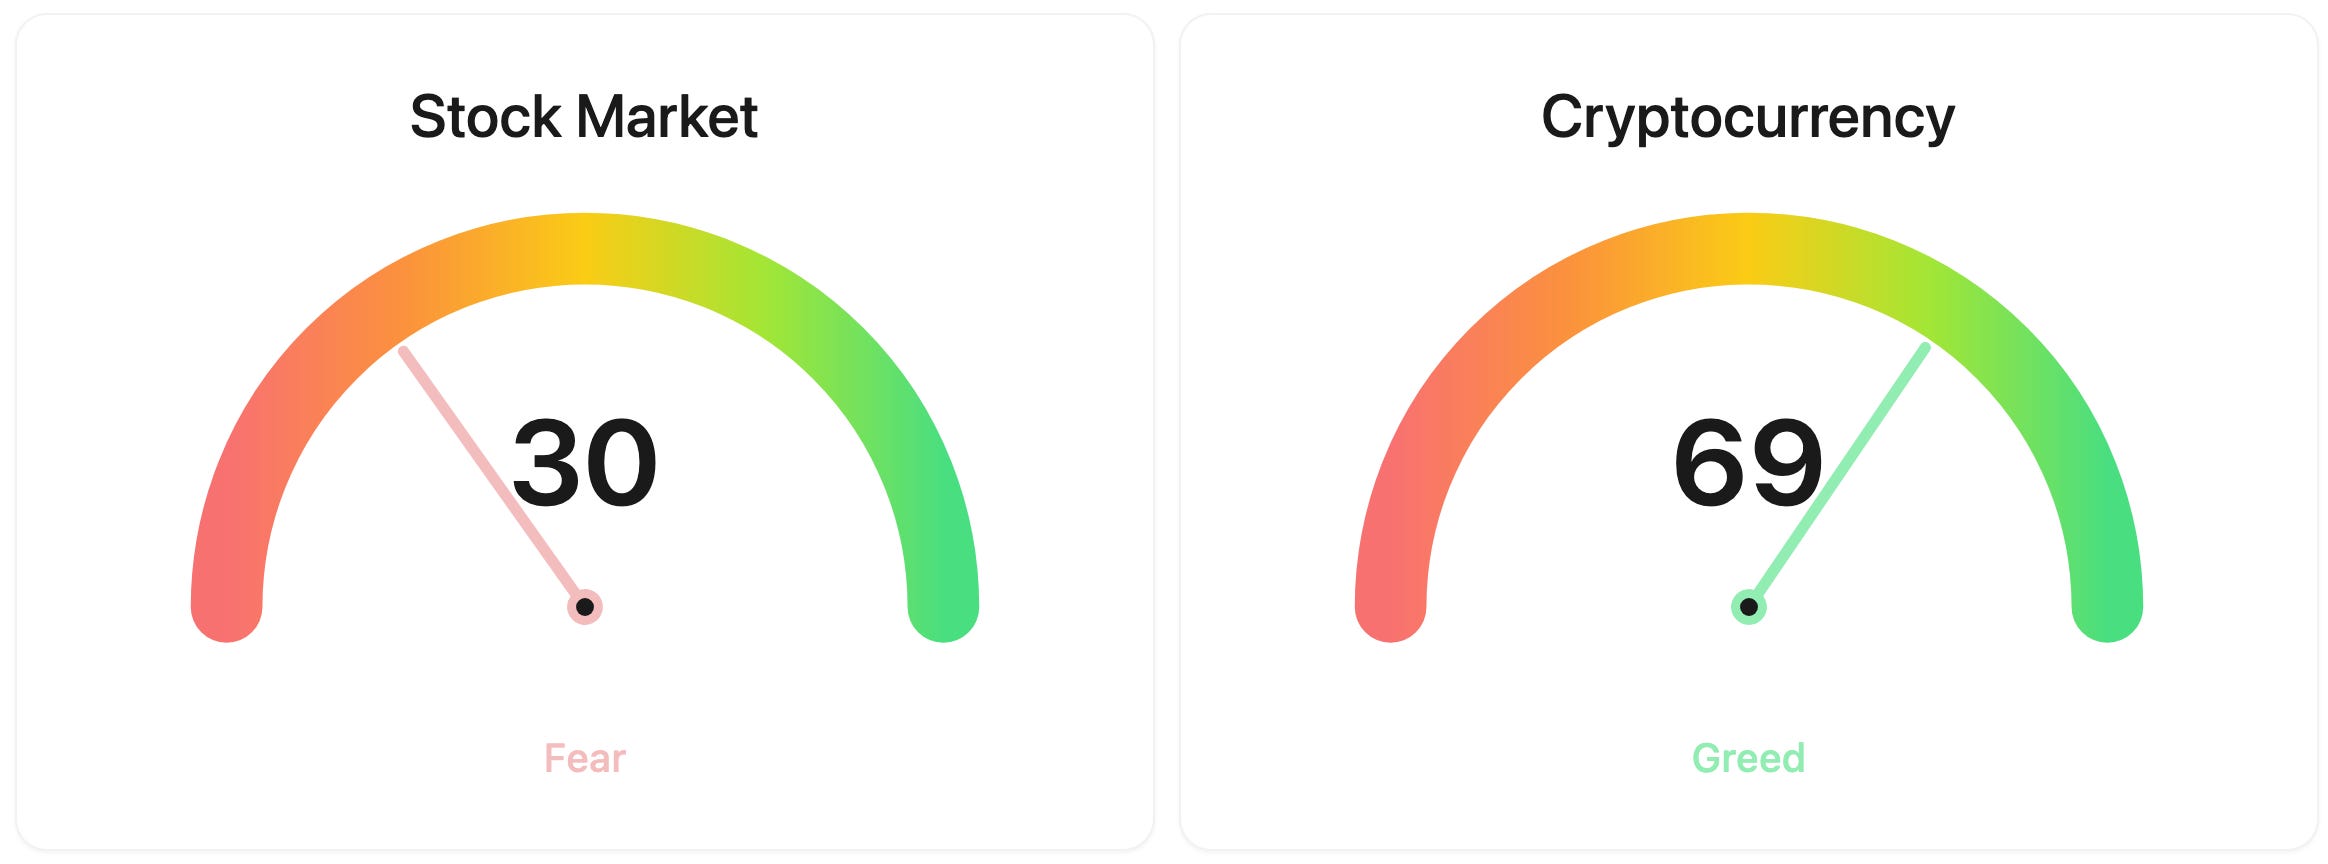
⚖️ Fear & Greed
📉 The Number That Matters
0.4%
China’s retail sales grew 0.4% in August against a year earlier, the slowest reading since May, while the country’s factories lifted output 5.2% over the same month.
⚔️ Winners vs Losers
Winners
RLGT 0.00%↑ : 17.17% Radiant Logistics, Inc. jumped after posting fiscal Q4 revenue of $261.4 million, up 18.5% year on year, with net income up 53.1% to $7.5 million and adjusted EBITDA up 31.6%. The company also extended its $200 million revolving credit facility to August 2031 and ended the year with no net debt.
BLSM 0.00%↑ : 6.67% BlossomHill Therapeutics, Inc. rose after presenting updated Phase 1/2 SOLARA data overnight at the World Conference on Lung Cancer in Seoul, showing anti-tumour activity for its macrocyclic EGFR inhibitor BH-30643 in patients with secondary resistance mutations including EGFR C797S, where no approved oral therapy currently exists.
Losers
ENVA 0.00%↑ : -16.20% Enova International, Inc. sank after withdrawing its regulatory applications with the OCC and the Federal Reserve to acquire Grasshopper Bancorp, with management saying regulators lack clear standards for nonbanks seeking bank charters. The company reaffirmed 2026 guidance of 20% to 25% revenue growth and said it will accelerate buybacks.
CLLS 0.00%↑ : -13.66% Cellectis S.A. extended its slide after abandoning its allogeneic CAR-T programmes lasme-cel and eti-cel to pivot into in vivo gene editing, leaving two early metabolic disease candidates with first Phase 1 data not due until late 2027.
SWRD 0.00%↑ : -10.79% Stewards Inc fell after its update on the proposed PIXL at Plantation and Envy Pompano Beach acquisitions confirmed the deals remain non-binding letters of intent with no assurance either completes, and that the roughly $240 million value covers the properties including existing debt rather than the stock consideration.
📊 Market Snapshot
Cryptocurrencies:
Bitcoin (BTC): $77,065 (▼1.42%)
Ethereum (ETH): $2,484 (▼1.25%)
XRP: $1.40 (▼1.43%)
Equity Indices (Futures):
S&P 500: 7,673 (▲0.63%)
NASDAQ 100: 29,373 (▲0.76%)
FTSE 100: 10,679 (▼0.11%)
Commodities & Bonds:
10-Year US Treasury Yield: 5.01% (▲0.20%)
Oil (WTI): $103 (▲0.98%)
Gold: $4,282 (▼0.38%)
Silver: $63.17 (▼0.07%)
Data as of: UK: 11:52 BST / US: 06:52 EDT / Asia (Tokyo): 19:52 JST
✅ 5 Things to Know
🏦 American borrowing costs reach a 2007 level
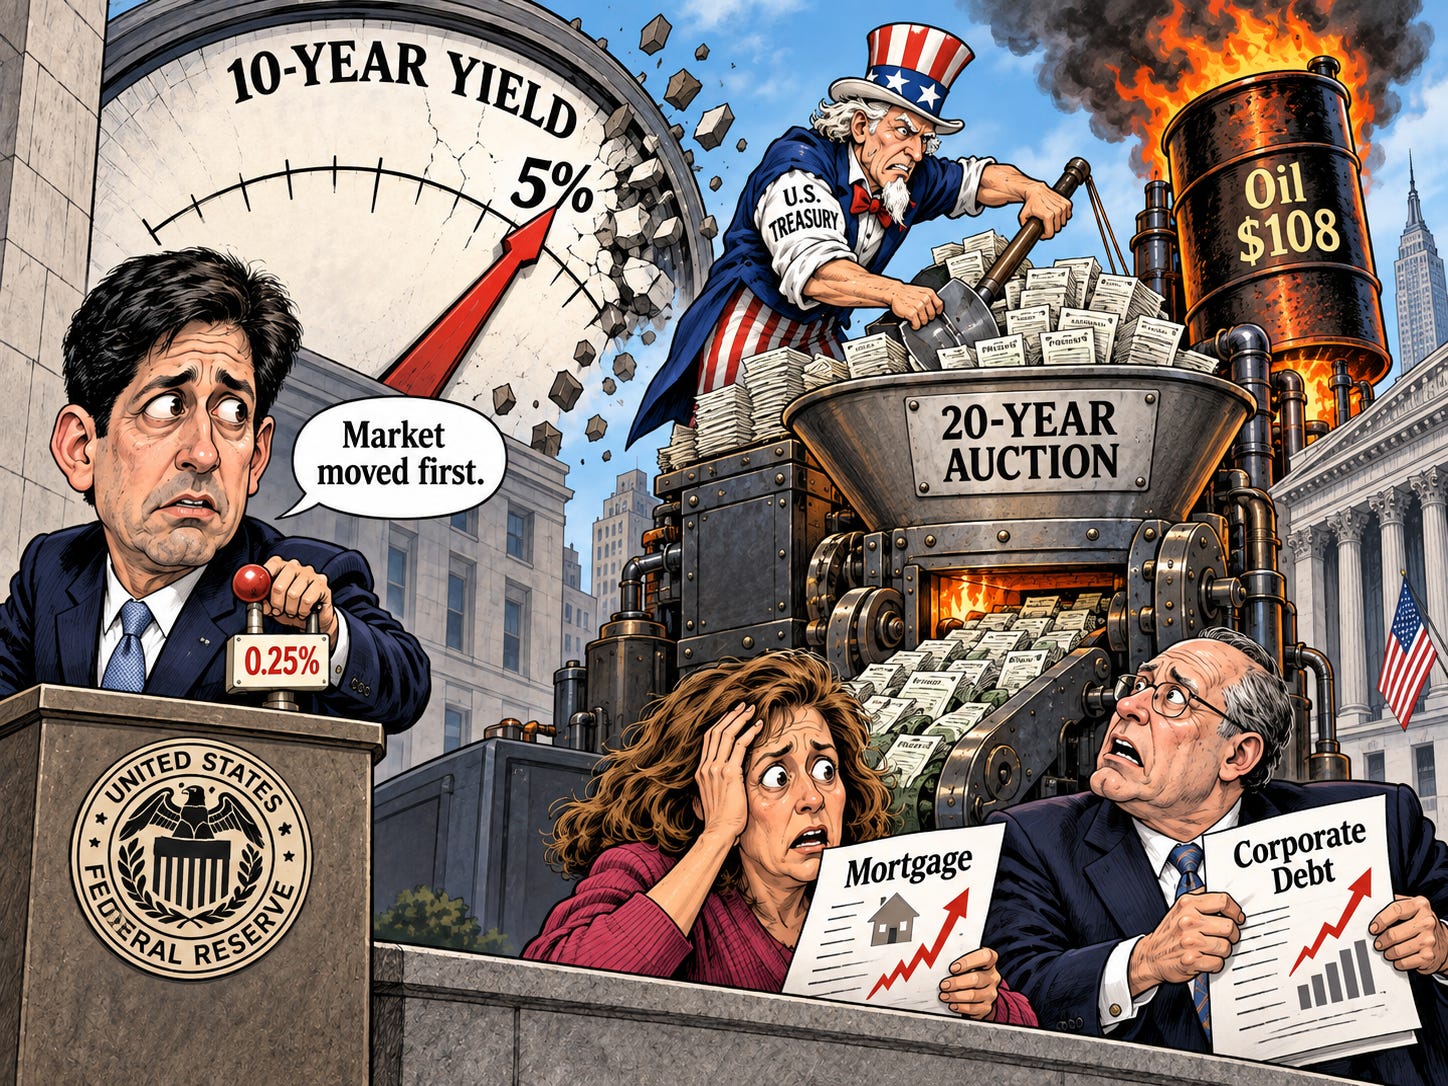
So the 10-year Treasury yield went through 5% on Monday for the first time since 2023, rising almost 5 basis points to 5.01% before buyers pulled it back. By early Tuesday in New York it had added 8 basis points more to 5.04%, the highest since 2007, and it was holding near 5.01% by late morning in London. That yield is what the American government pays to borrow for a decade, and it sets the reference rate for corporate debt and home loans underneath it. Brent crude climbing to $108 a barrel did part of the work, because oil feeds straight into inflation expectations. Heavy government borrowing and a wall of corporate issuance did the rest. (Bloomberg)
The Federal Reserve began its 2-day meeting on Tuesday and decides on Wednesday at 2:00pm in New York, which is 7:00pm UK. Futures put a quarter-point rise at roughly 92%, which would take the target range to 3.75% to 4.00% and would be the first increase since 2023. The bond market has already moved past that. Traders price a gradual climb to about 4.2% by December and roughly 4.6% by September 2027. Supply is the piece that does not depend on the Fed at all, because Treasury sells $16 billion of 20-year debt this week and the when-issued yield sat around 5.27% on Friday, which would be the highest for that maturity since it returned in 2020. Equities felt it on Monday, with the S&P 500 closing at 7,621.54, down 0.48%. (Yahoo Finance)
Sensei’s Insight: Look. 5% on the 10-year is the number that reprices everything else, and it got there before the Fed said a word. Watch the 20-year auction this week. A weak one tells you more about the next 6 months than the dot plot will.
🇨🇳 China’s factories sped up and its shoppers stopped
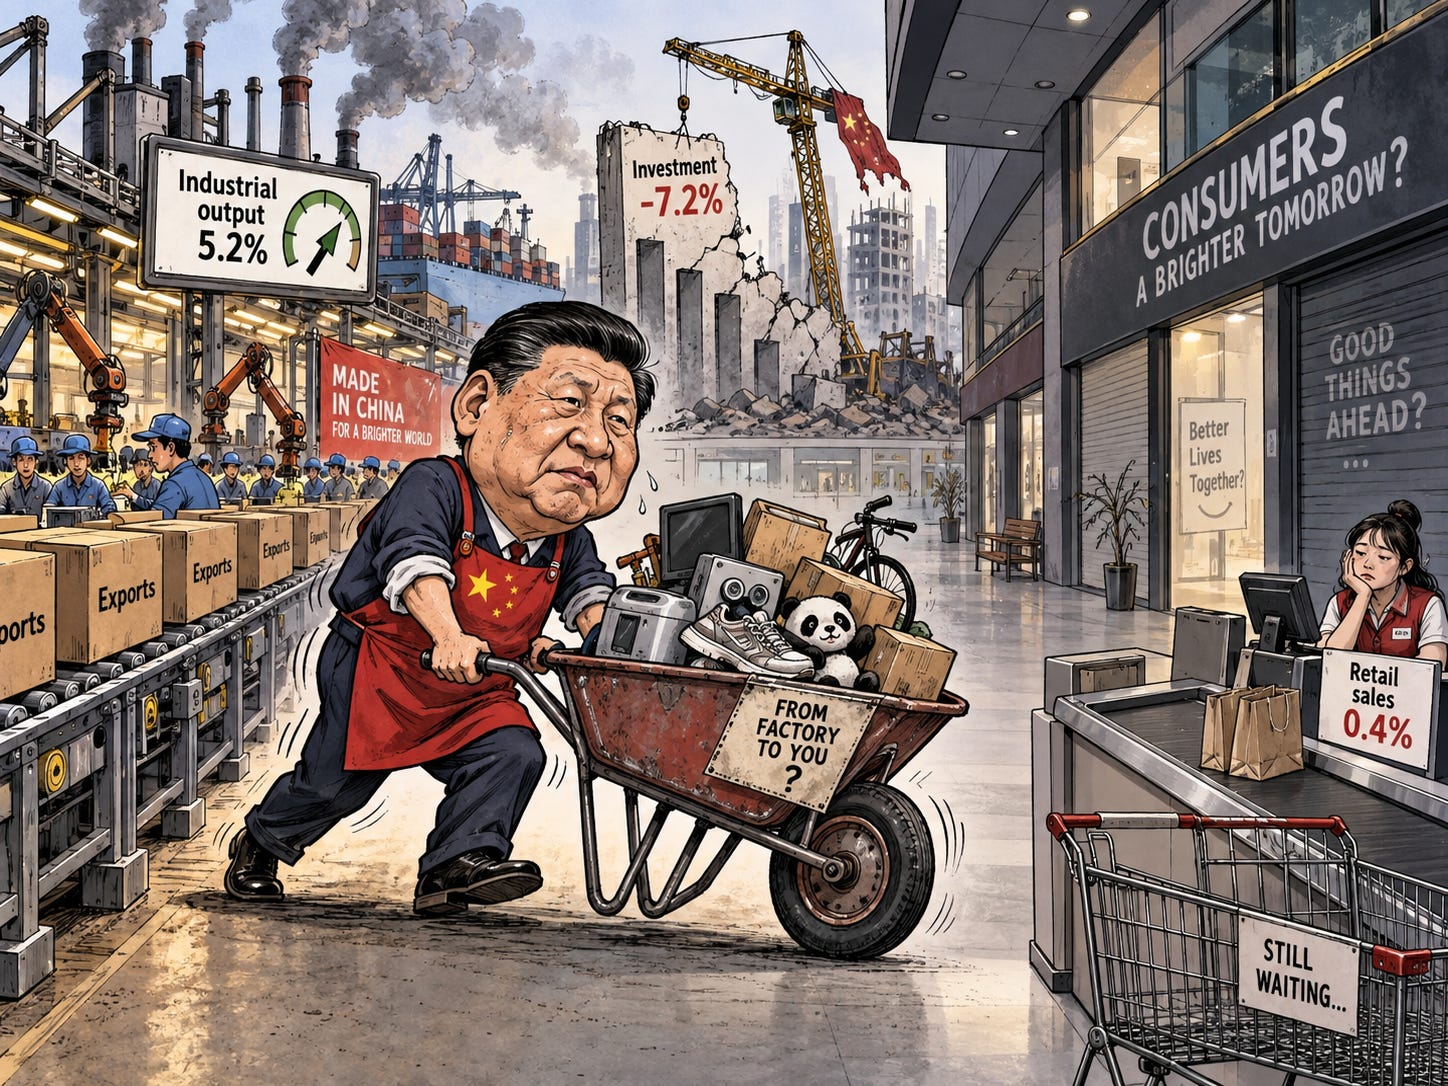
0.4%. That is how much China’s retail sales grew in August against a year earlier, and economists surveyed by Bloomberg had looked for 0.8%. It is the slowest reading since May and the second straight slowdown, after 1% in June. Industrial production went the other way, expanding 5.2% against July’s 4.5% and a forecast of 4.8%. Fixed-asset investment, which is the money going into factories, roads and property, fell 7.2% against a year earlier, a deeper contraction than expected. The National Bureau of Statistics said the economy “operated steadily” while acknowledging that “adverse external factors are intensifying”. (CNBC)
China is the second-largest consumer market on earth and the marginal buyer of a long list of commodities, so the split in this release matters well beyond Shanghai. Factories running at 5.2% while shoppers add 0.4% means goods are being made for somewhere other than the Chinese till, which is what the export data has been showing all summer. “China’s economy continues to show diverging signals, as consumption and investment remain weak while industrial production maintains the momentum,” said Zhiwei Zhang, chief economist at Pinpoint Asset Management. The investment figure is the one worth sitting with, because 7.2% down on the year is capital deciding not to arrive.
Beijing has spent 2 years trying to move growth towards the consumer and the consumer is still not showing up.
Sensei’s Insight: Now. Factories at 5.2% and shoppers at 0.4% is the same story China has been telling for 2 years, and the gap is getting wider. Investment down 7.2% is the number I would put first.