

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
👀 Today’s Stories at a Glance
🤖 Muse hit the habit stocks: financials fell as much as 2.4% on fears an AI agent makes switching providers effortless.
🛢️ Iran named its price: Brent settled at $99.25 as Tehran listed 3 conditions for reopening Hormuz. Each asks Washington first.
🇪🇺 Europe sped up, Britain slowed: the eurozone PMI hit 53.1, a 41-month high. Britain’s fell to 51.7, 35 days before the Budget.
💸 SoftBank borrows $11 billion of junk: the bond pays for its next OpenAI tranche, and it prices on Thursday.
⛽ Trump backs a diesel export ban: with pump diesel near $6.50, he wants a decision “fast, one way or the other”.
🏭 Ineos idles 3 UK plants: almost 4,000 Humberside jobs are at risk as gas costs 12 times the US price.
🇬🇧 Airtel Money picks London: the African payments firm wants up to $9 billion for one of London’s biggest floats in years.
🔷 Ether’s best ETF day of 2026: US funds took about $270 million on Monday as ETH closed at an 8-month high.
🇨🇳 Trump meets Xi on the tarmac: a rare planeside welcome opens 3 days of pomp, with talks and a state dinner on Thursday.
📈 The 10-year just broke its 2023 high: Chart of the Day covers 5.02%, the 5% target and the 4.4% back test.
🧠 One Big Thing
Every company that earns money from customers who never get round to switching just picked up a new competitor. Meta’s Muse agent can compare prices, cancel memberships and book things on your behalf, and on Tuesday the market put a price on that. Banks, insurers, brokers and travel sites fell hard while the Nasdaq closed at a record. Goldman Sachs named telecoms, insurance and utilities as the industries to watch. Until now the AI trade has been about who builds it. This week it turned into a story about who pays for it.
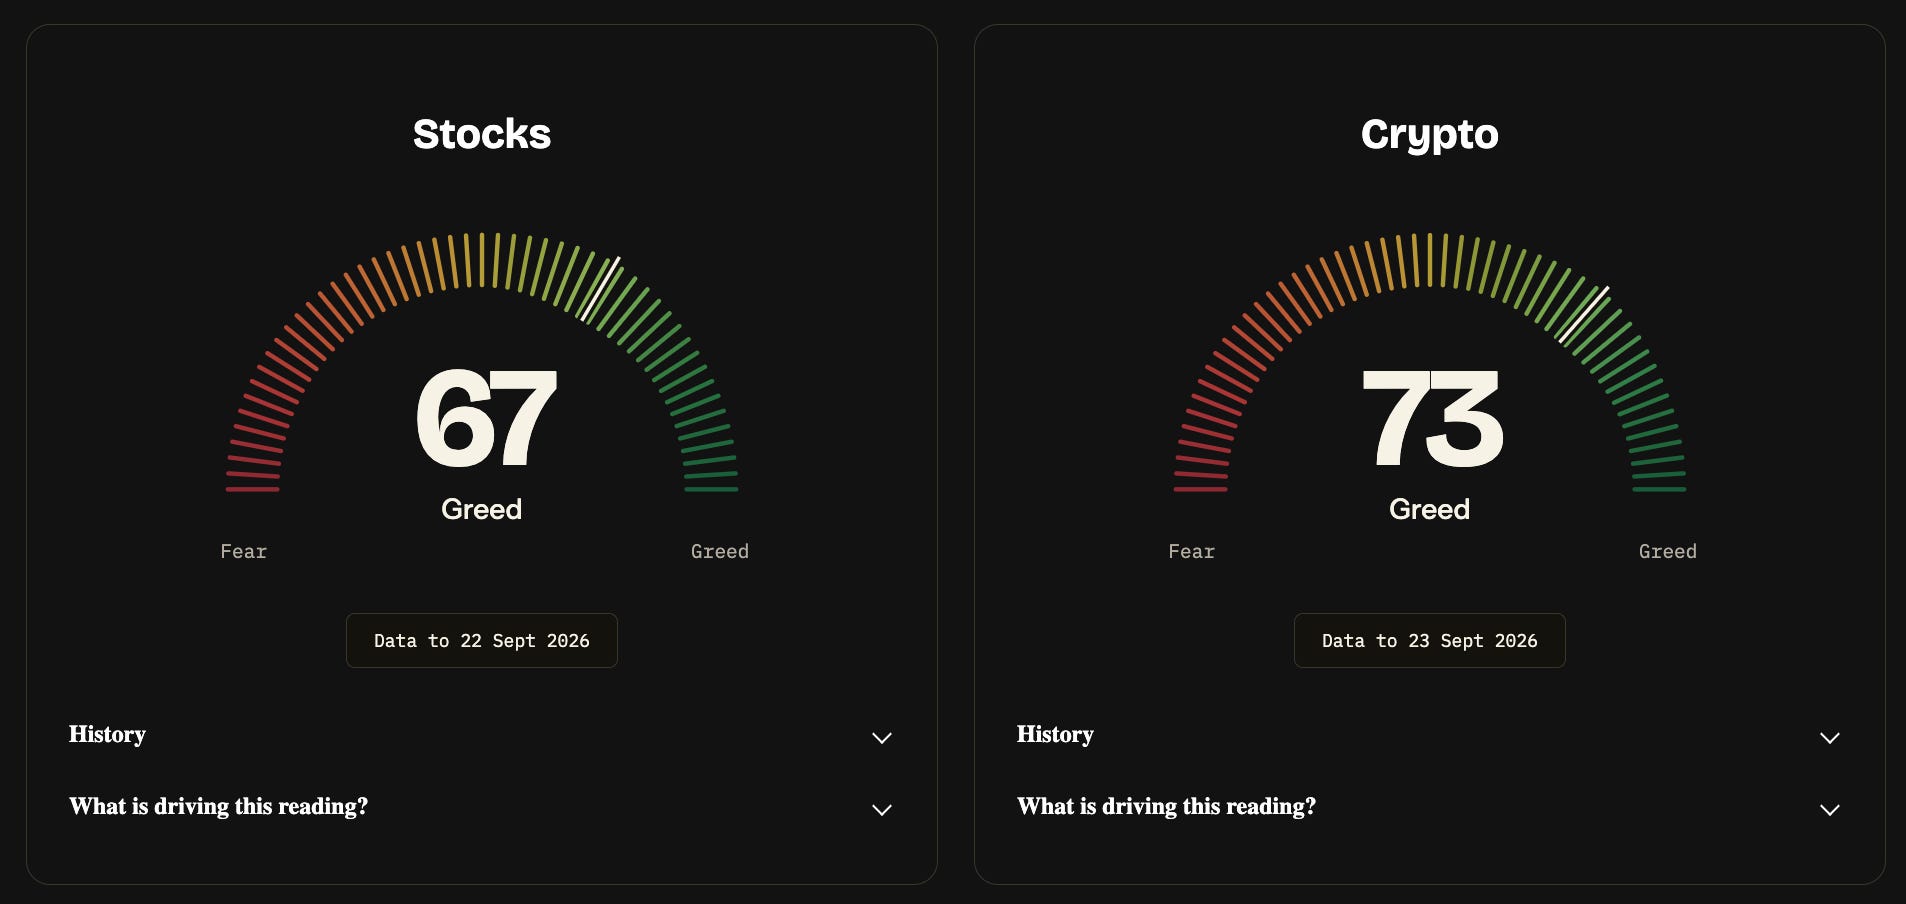
⚖️ Fear & Greed
📉 The Number That Matters
2
Only 2 commercial ships crossed the Strait of Hormuz on Monday, against about 125 a day before the war. Brent still closed under $100 on Tuesday, pricing a reopening that has not happened yet.
⚔️ Winners vs Losers
Winners
WOR 0.00%↑ : 16.73% Worthington Enterprises, Inc. shares jumped after fiscal first-quarter adjusted EPS of 82 cents beat the 75-cent consensus. Sales rose 13% to beat estimates, including 7% organic growth, and free cash flow nearly doubled year on year.
IONQ 0.00%↑ : 11.41% IonQ, Inc. shares rallied after the company announced what it called the industry’s first end-to-end real-time quantum error correction decoder running on standard CPUs, tested on circuits simulating 408 logical qubits. The news came a day after a multiyear hardware deal with South Korea’s SDT and just as the Quantum World Congress opens.
Losers
AU 0.00%↑ : -5.20% AngloGold Ashanti PLC shares erased Tuesday's 2.62% gain and more as gold fell from its open. Demand for safe havens is fading with US-Iran tensions easing and Trump hosting Xi Jinping in Washington.
📊 Market Snapshot
Cryptocurrencies:
Bitcoin (BTC): $85,468 (▼0.84%)
Ethereum (ETH): $2,718 (▼1.27%)
XRP: $1.57 (▼0.09%)
Equity Indices (Futures):
S&P 500: 7,825 (▼0.08%)
NASDAQ 100: 30,943 (▼0.28%)
FTSE 100: 10,690 (▼0.56%)
Commodities & Bonds:
10-Year US Treasury Yield: 4.98% (▲0.59%)
Oil (WTI): $91 (▲1.11%)
Gold: $4,300 (▼1.36%)
Silver: $64.86 (▼3.23%)
Data as of: UK: 12:41pm BST / US: 7:41am EDT / Asia (Tokyo): 8:41pm JST
✅ 5 Things to Know
🤖 Meta’s agent hit the companies that live on habit
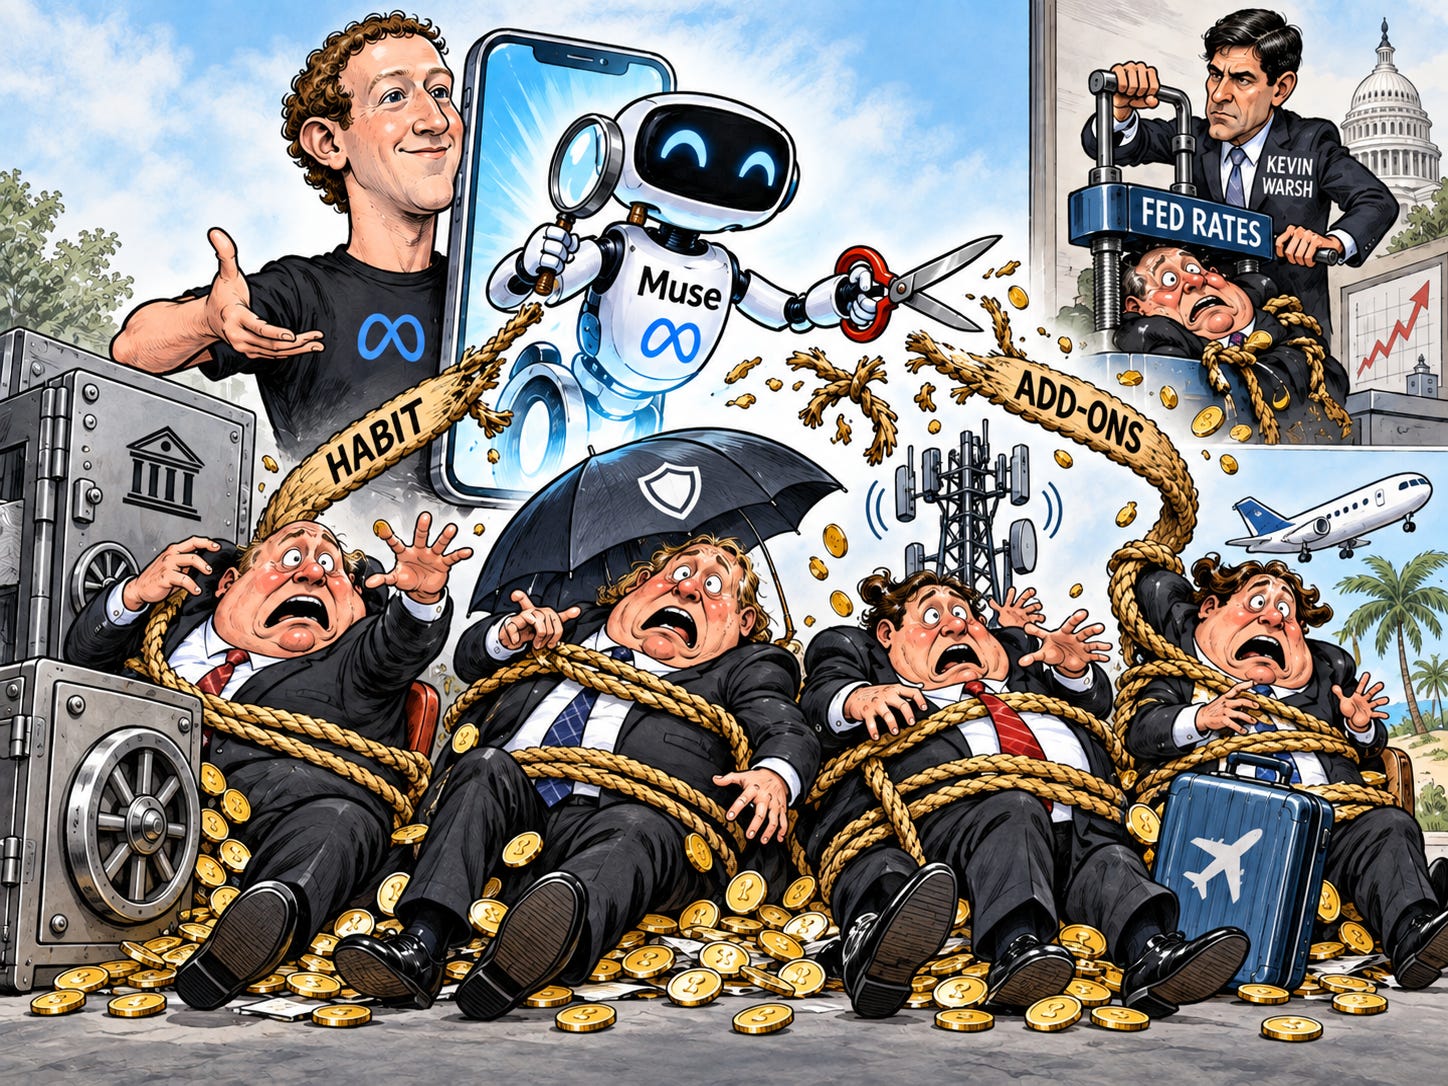
Who loses when switching costs nothing? On Tuesday the market answered. The S&P 500 financials index dropped as much as 2.4% to its lowest level since July, with JPMorgan, Morgan Stanley and Wells Fargo all down more than 2.5%. Allstate and Charles Schwab fell more than 5%. Expedia lost 3.7% and Booking 3.9%. In Europe, telecoms were the worst sector in the Stoxx 600, with Orange and BT down about 4% each. The trigger was Muse, Meta’s personal AI agent, which topped Apple’s US App Store and can complete tasks through services like Gmail and OpenTable. Yahoo Finance
Goldman Sachs’s trading desk said industries built on recurring bills, negotiable pricing and add-ons could come under pressure as agents get better at comparing prices, booking trips and handling customer service. Its basket of “consumer inertia” stocks includes AT&T, T-Mobile, Allstate, Progressive, Netflix, Paramount Skydance, Expedia and Booking. Consumer inertia is the habit of paying the same provider year after year even when a cheaper one exists. Rhys Williams of Wayve Capital Management called Muse “no doubt a negative for those kinds of companies”, and also said that right now it is “more of a curiosity”.
Banks had a second problem. They have been weak since the Federal Reserve raised rates on 16 September, because a narrower gap between short and long interest rates squeezes what they earn on the difference. JPMorgan fell 3.4% and was one of the heaviest weights on the S&P 500, which closed flat at 7,764.64. The Nasdaq Composite closed at a record 27,244.28 on the same day. Associated Press
Sensei’s Insight: The market has started pricing where AI money comes from. It comes out of companies that profit from people not paying attention. Meta Connect opens on Wednesday. What I am watching is whether Muse gets the ability to pay for things, because that turns a curiosity into a threat.
🛢️ Iran named its price for reopening Hormuz
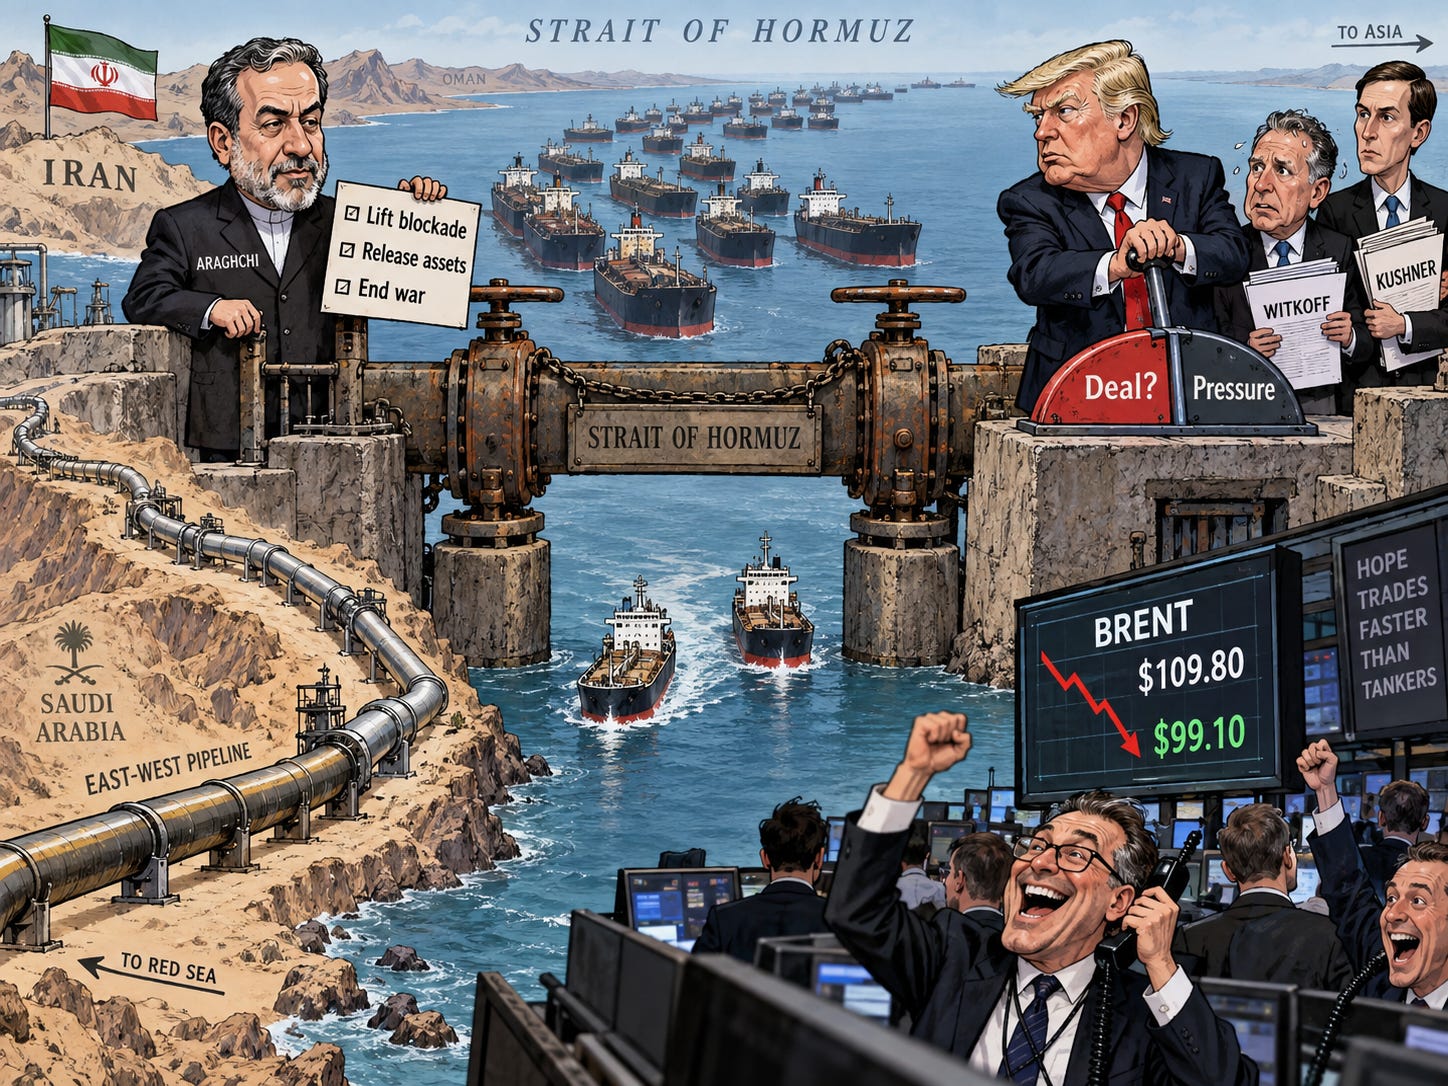
Brent crude settled at $99.25 a barrel on Tuesday, down 1.1%, after briefly trading below $98 in the morning. It touched nearly $110 last week. Before the war with Iran began, a barrel cost $72. Associated Press
What moved it was a meeting. Mediators shuttled for hours between US envoys Steve Witkoff and Jared Kushner and Iran’s foreign minister Abbas Araghchi on the sidelines of the UN General Assembly in New York, and Trump called it “a very productive meeting”. Iranian state media listed Tehran’s conditions for reopening the Strait of Hormuz: lift the US naval blockade, release frozen Iranian assets, and end the war on what it calls the “resistance” fronts. A senior Iranian official told Reuters the strait could reopen within 7 days if the US eased military pressure and lifted its blockade of Iranian ports.
All 3 conditions ask Washington to move first. Hours before the talks, Trump told the General Assembly he faces a “big decision” between a deal and moving to “annihilate the Islamic Republic”. Iran’s armed forces replied that they were ready to deliver “more severe, crushing, and unpredictable blows”. Witkoff said the mediators will continue their work. Al Jazeera
The ships have not moved yet. Only 2 commercial vessels crossed Hormuz on Monday, against about 125 a day before the conflict. Saudi Aramco has restarted its East-West pipeline, which carries crude to the Red Sea and around the strait, and that is where the physical relief has come from so far.
Sensei’s Insight: Oil has priced the reopening before a single extra tanker has sailed. Monday saw 2 ships cross. What I am watching is the daily transit count, because a deal on paper needs ships on the water before it moves the barrel for good.
🇪🇺 Europe sped up in September and Britain slowed
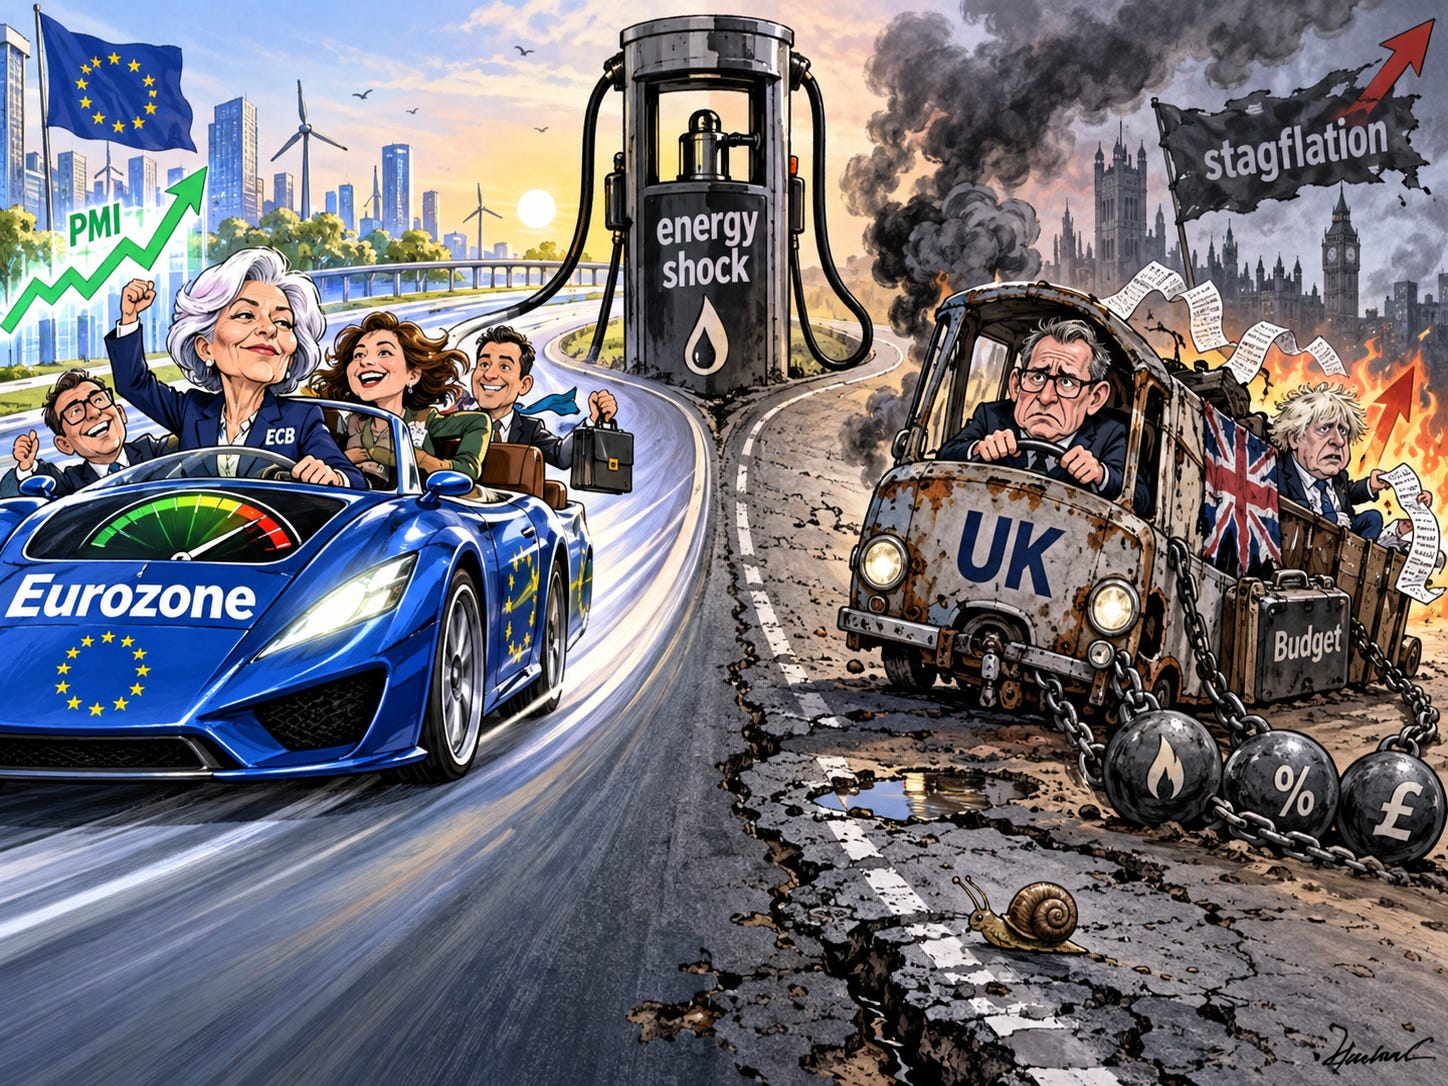
53.1. That is the eurozone’s flash composite PMI for September, up from 52.0 in August and well above the 51.7 expected. A reading above 50 means firms reported growth, and this one is the fastest in almost 3.5 years. Services jumped to 53.0 against 51.5 expected. Germany grew for a third straight month and France expanded for the first time in 10 months. Input costs and selling prices both rose at the sharpest rates in 4 months, and markets now put the chance of an ECB rate rise in October at about 48%, up from about 45% before the data. investingLive
Britain went the other way half an hour later. The UK composite fell to 51.7 from 52.5, below the 52.0 expected, with services also at 51.7 and manufacturing at 52.0. Chris Williamson of S&P Global Market Intelligence said output is growing at a pace consistent with “a mere 0.1% quarterly rate”. He blamed high energy prices, business costs, higher borrowing costs and uncertainty before the autumn Budget. He also said the survey’s price gauges suggest the Bank of England will keep “a hawkish bias”. investingLive
The same energy shock is producing 2 different economies.
Europe is growing fast enough to take a rate rise. Britain is slowing while its prices climb, which is the mix a central bank likes least. The Budget is on 28 October and the Bank of England decides on 5 November. The American flash PMI follows at 2:45pm UK, which is 9:45am in New York.
Sensei’s Insight: Britain is getting the inflation without the growth. In plain English, that is stagflation, and it lands 35 days before the Budget. What I am watching is whether the price gauges keep rising into October, because the Bank cannot look through those.
💸 SoftBank is borrowing $11 billion of junk to fund OpenAI
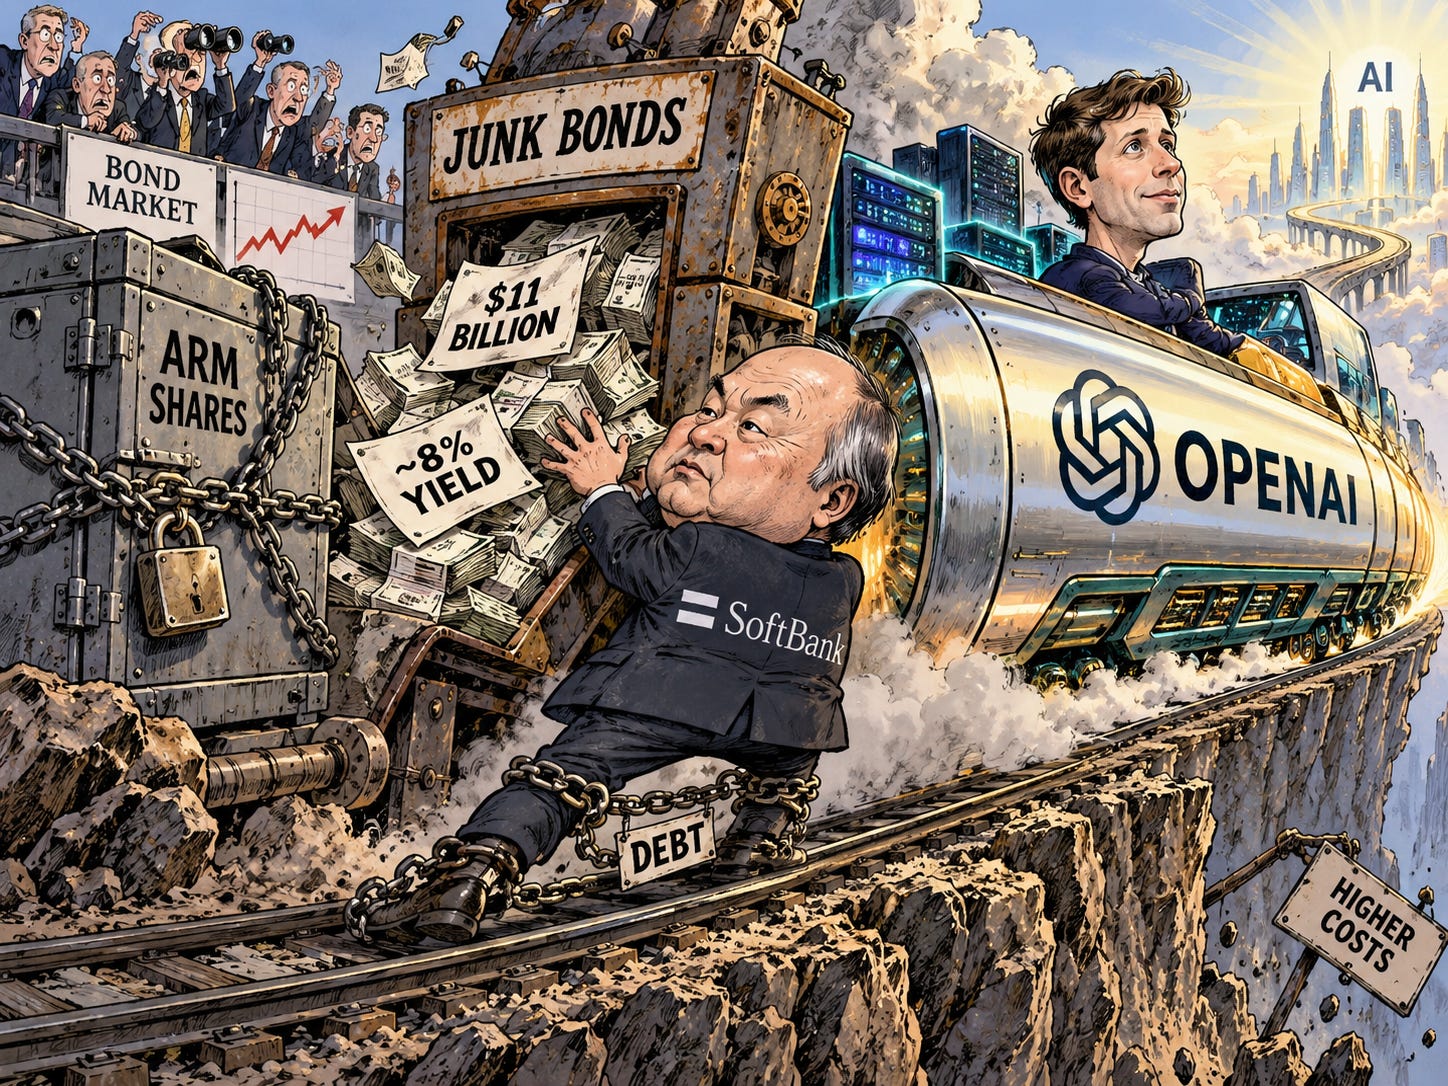
On Monday, SoftBank launched $10 billion of dollar bonds and €1 billion of euro bonds, worth more than $11 billion in total, with the money earmarked for its OpenAI investment. If it completes at that size, it would be the largest non-financial corporate bond deal on record from Asia Pacific and Japan. Quartz
The bonds are rated junk, meaning below investment grade, so SoftBank pays more to borrow. They price on Thursday 24 September and settle on 29 September. The proceeds cover SoftBank’s $10 billion payment for the third tranche of its follow-on OpenAI investment, due to close on 1 October. SoftBank has committed close to $65 billion to OpenAI and has sold almost $15 billion of bonds in 2026, the most of any junk-rated company this year.
The cost of the bet is rising. The yield on SoftBank’s dollar bond due in 2031 reached 8.2% earlier this month, up from as low as 6.7% in January. The cost of insuring its debt against default is at a 3-year high. It has also raised a loan secured on its Arm shares to $25 billion. Sam Altman has said OpenAI will not list this year, so SoftBank’s stake has no public market to sell into. Business Standard
Sensei’s Insight: The AI buildout is now being paid for with junk debt yielding about 8%. That is a very different thing from spending spare cash. What I am watching is Thursday’s final pricing against that 8.2%, because it tells us how much appetite the bond market has left for carrying the bill.