

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
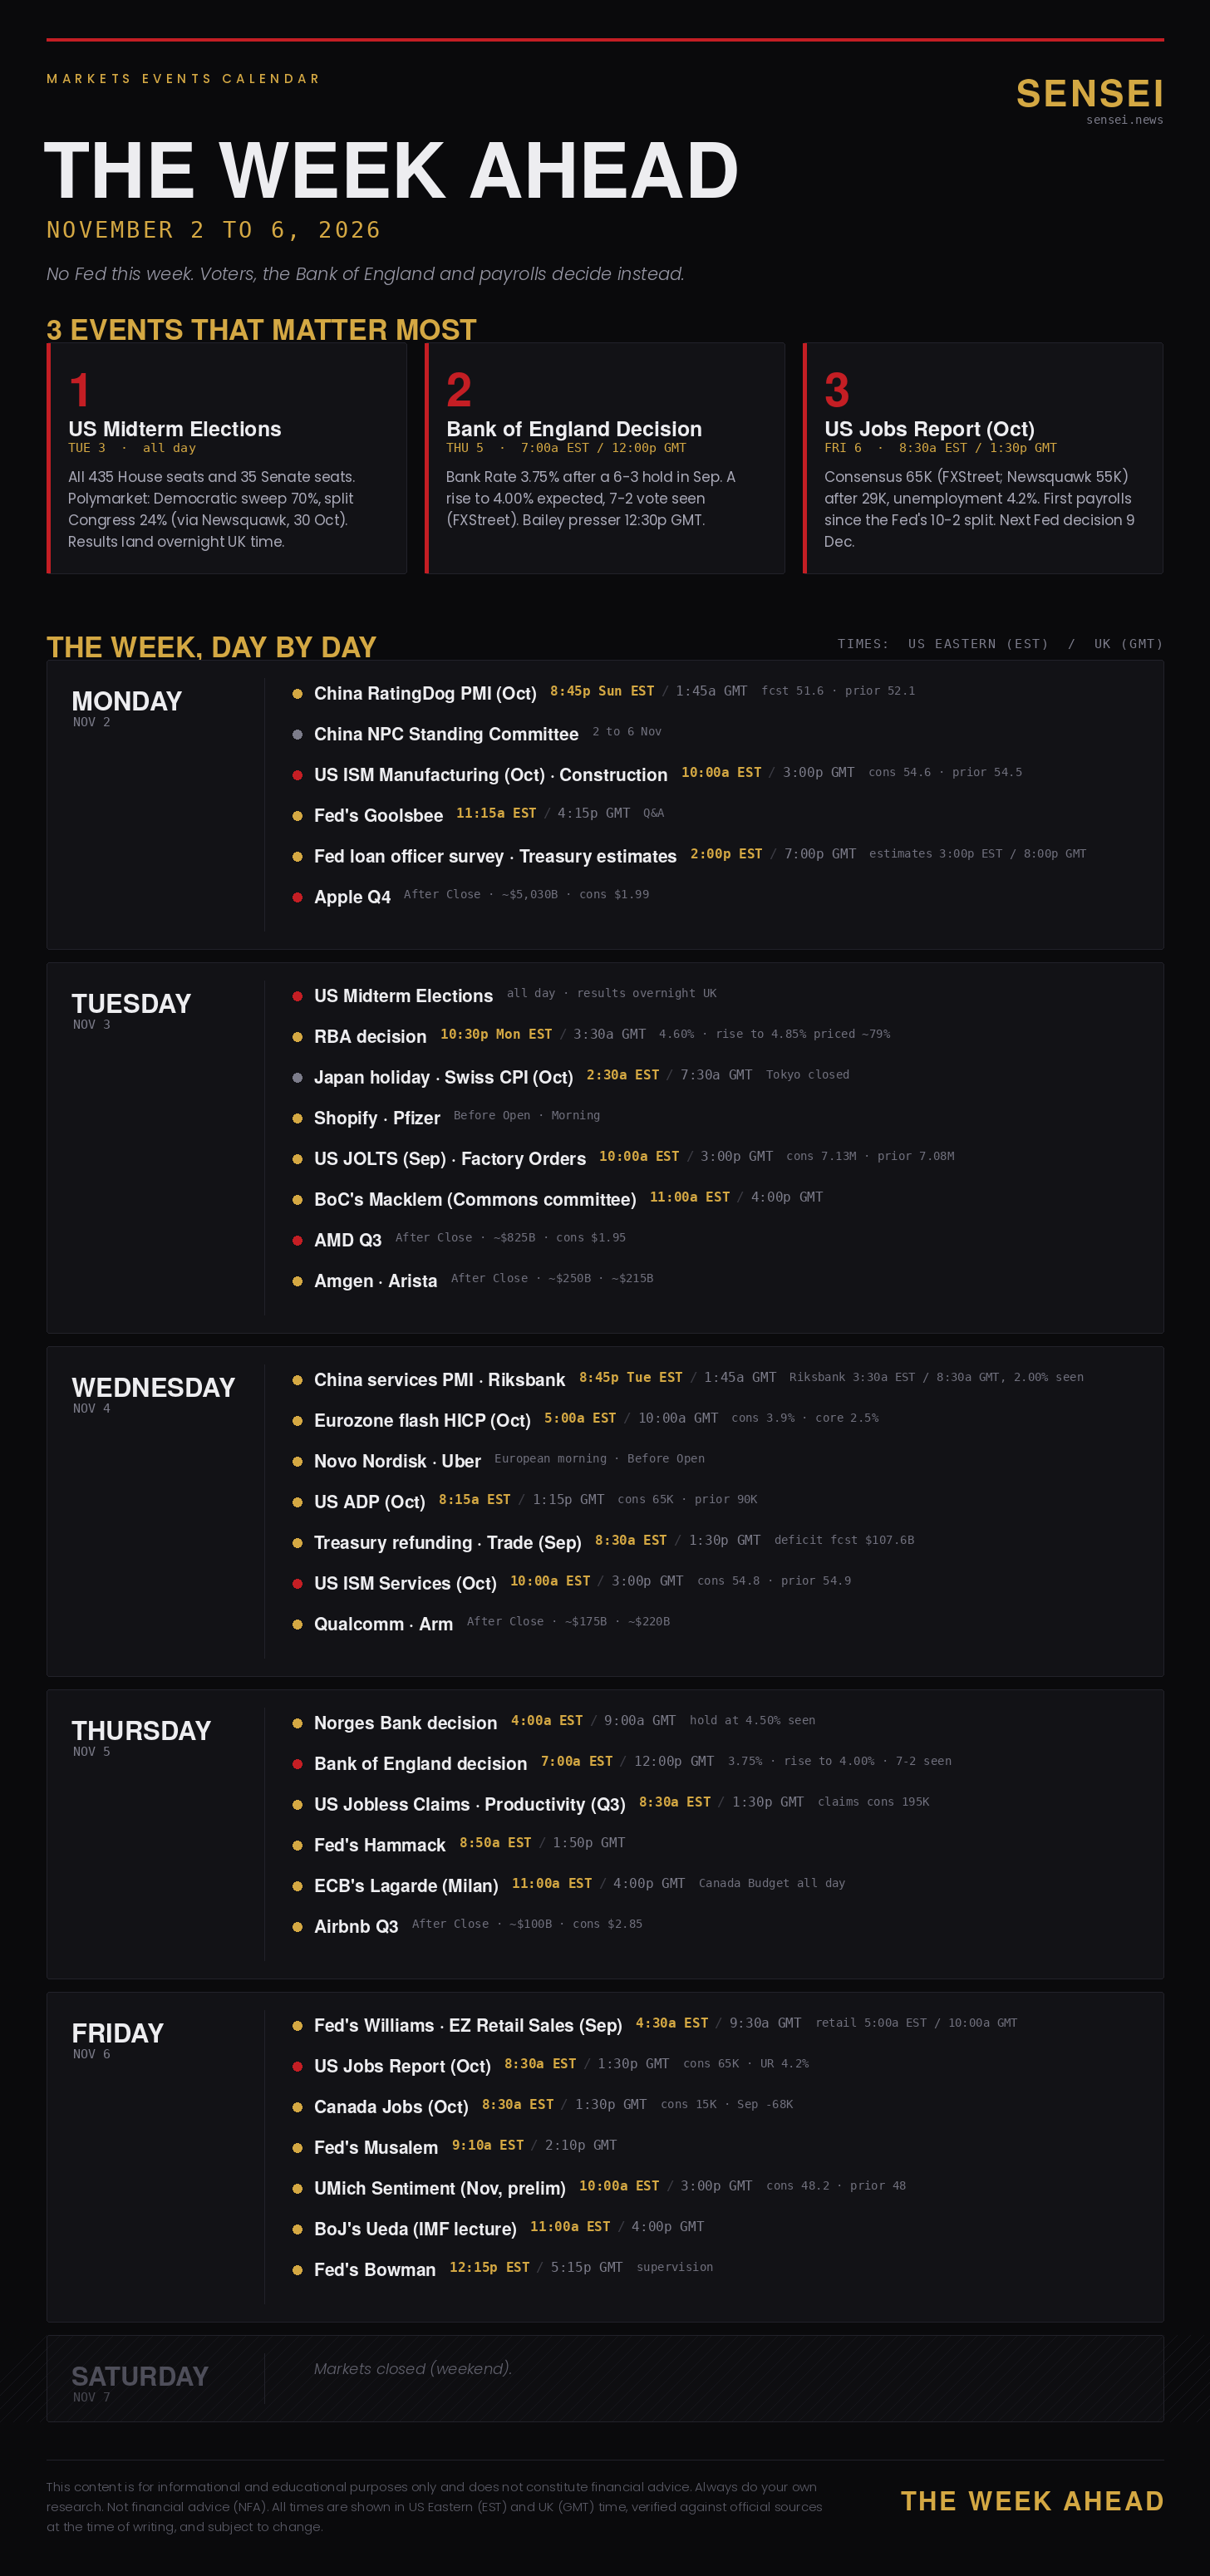
There is no Fed meeting this week, so the big decisions sit elsewhere. Americans vote in the midterms on Tuesday, and the Bank of England is expected on Thursday to make its first rate rise of this cycle. The October jobs report lands on Friday, a week after a Fed that split 10-2 left December open. Apple opens the earnings week on Monday evening, with AMD, Arista, Qualcomm and Arm behind it, straight after the Nasdaq’s worst month since March 2025. US clocks went back on Sunday, so New York and London are 5 hours apart again.
Last Week:
Fed Decision (October) The Fed held at 3.75% to 4.00% in a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack voting for a rise. The statement now says “the accumulation of more information will help the Committee determine the policy stance”, and Chair Kevin Warsh told reporters, “We just came out of a heck of a family fight.” Futures still priced about an 85% chance of a rise on 9 December after the decision (Yahoo Finance, citing Bloomberg data, 28 October). (Wolf Street)
US Q3 GDP and PCE (September) 3.4%. Consensus was 3.2%. Headline PCE inflation rose to 3.6% and core to 3.1%, both as expected, and the saving rate slipped to 3.8% from 4.0%. Friday’s Employment Cost Index rose 0.8%, also as expected, which leaves this Friday’s payrolls as the next big read on the labour market before December.
Microsoft, Alphabet and Amazon Q3 Google Cloud revenue grew 103% to $30.71 billion, Azure grew 48% and AWS grew 39% to $45.98 billion. Spending decided the reaction. Alphabet’s capital spending reached $51.36 billion in the quarter and Amazon’s $77.26 billion, which took Amazon’s free cash flow over the last 12 months to minus $42.4 billion. Alphabet ended October down 17.22% and Microsoft up 1.78%, and the Nasdaq fell 5.30% in the month, its worst since March 2025. (investingLive)
UK Autumn Budget Chancellor John Healey raised the bank surcharge to 6% from 3% for 15 months, and his headroom against the fiscal rules came in at £14.5 billion, down from £23.6 billion. The gilt market took it calmly. The Bank of England decides 8 days later.
The setup: the S&P 500 fell 1.82% on Friday to 7,580.07, down 0.6% on the week, and the Nasdaq lost 2.0%, a third straight weekly fall for both (Yardeni Research). The 10-year Treasury yield ended at 4.93% and the 2-year at 4.59%, and several Fed officials spoke on Friday of further rises. This week the decisions pass to American voters, the Bank of England and the October payrolls. (investingLive, Yardeni Research)
Week at a Glance
🔴 US Midterm Elections: Tuesday, All day
🔴 US Jobs Report (October): Friday, 8:30 AM ET / 1:30 PM GMT
🔴 Bank of England Decision: Thursday, 7:00 AM ET / 12:00 PM GMT
🔴 Apple Q4 Results: Monday, After Close
🟠 ISM Manufacturing and Services PMIs: Monday and Wednesday, 10:00 AM ET / 3:00 PM GMT
🟠 Eurozone Flash Inflation (October): Wednesday, 5:00 AM ET / 10:00 AM GMT
🟠 AMD, Arista, Qualcomm and Arm Results: Tuesday and Wednesday, After Close
🟠 US Treasury Quarterly Refunding: Wednesday, 8:30 AM ET / 1:30 PM GMT
🟠 RBA Decision: Monday, 10:30 PM ET / Tuesday, 3:30 AM GMT
MONDAY, November 2
China Manufacturing PMI, RatingDog (October) · Sunday 8:45 PM ET / Monday 1:45 AM GMT Rio Times has 51.6 after 52.1 in September for the private survey of Chinese factories.
China NPC Standing Committee · All day China’s top legislative body meets from 2 to 6 November, and Newsquawk notes the draft agenda contains no fiscal items, including any change to the debt quota.
⚡⚡ US ISM Manufacturing PMI (October) · 10:00 AM ET / 3:00 PM GMT Consensus is 54.6 (FXStreet) after 54.5, where anything above 50 means growth, and the prices paid index is seen at 77 after 77.9 in September (FXStreet). (ISM)
US Construction Spending (September) · 10:00 AM ET / 3:00 PM GMT Building activity for September, out with the ISM report.
Fed’s Austan Goolsbee · 11:15 AM ET / 4:15 PM GMT The Chicago Fed president, who does not vote on rates this year, moderates a Q&A with Andréa Maechler of the Bank for International Settlements at the bank’s Financial Markets Group conference, so he may not be giving his own view on policy. (Chicago Fed)
Fed Senior Loan Officer Survey (Q3) · 2:00 PM ET / 7:00 PM GMT The Fed’s quarterly survey of whether banks are tightening or loosening lending standards. (Federal Reserve)
US Treasury Financing Estimates · 3:00 PM ET / 8:00 PM GMT How much the government plans to borrow this quarter, 2 days before the full refunding plan. (US Treasury)
EARNINGS
⚡⚡⚡ AAPL · Apple · After Close · ~$5,030B Watching: revenue against Apple’s own guide of 9% to 11% growth, which points to about $111.7 billion to $113.7 billion. Consensus is $1.99 a share (MarketBeat), it is John Ternus’s first results call as chief executive, and the call is at 5:00 PM ET / 10:00 PM GMT.
TUESDAY, November 3
⚡⚡⚡ US Midterm Elections · All day All 435 House seats, 35 Senate seats and 36 governorships are on the ballot, and results arrive through Tuesday night ET, which is the early hours of Wednesday in the UK. Detail in The 3 Events That Matter Most below.
⚡⚡ Reserve Bank of Australia Decision · Monday 10:30 PM ET / Tuesday 3:30 AM GMT The cash rate is 4.60% after September’s rise, and money markets priced about a 79% chance of a rise to 4.85% (Newsquawk, 30 October) after Australian inflation of 4.3% in September. Governor Michele Bullock’s press conference follows an hour later.
Swiss CPI (October) · 2:30 AM ET / 7:30 AM GMT Prices were flat on the month and up 1.0% on the year in September.
⚡ US JOLTS Job Openings (September) · 10:00 AM ET / 3:00 PM GMT Consensus is 7.13 million (FXStreet) after 7.08 million in August, 3 days before the payrolls report. (BLS)
US Factory Orders (September) · 10:00 AM ET / 3:00 PM GMT Consensus is a 1.2% rise (FXStreet) after 0.1% in August.
BoC Governor Tiff Macklem · 11:00 AM ET / 4:00 PM GMT Macklem and Senior Deputy Governor Carolyn Rogers appear before the House of Commons finance committee, with a Senate committee appearance to follow on Thursday. (Bank of Canada)
Japan Holiday · All day Tokyo markets are closed for Culture Day.
EARNINGS
⚡⚡ AMD · Advanced Micro Devices · After Close · ~$825B Watching: data centre chip sales, a week after Intel’s AI chip division grew 78%. Consensus is $1.95 a share (MarketBeat), and the call is at 5:00 PM ET / 10:00 PM GMT.
⚡ AMGN · Amgen · After Close · ~$250B Watching: sales growth of its newer drugs. Consensus is $5.79 a share (MarketBeat), and the call is at 4:30 PM ET / 9:30 PM GMT.
⚡ ANET · Arista Networks · After Close · ~$215B Watching: AI networking orders from the big cloud spenders, a week after Alphabet spent $51.36 billion in a quarter. Consensus is $1.08 a share (MarketBeat), and the call is at 4:30 PM ET / 9:30 PM GMT.
SHOP · Shopify · Before Open · ~$205B Watching: merchant sales volume heading into the holiday quarter. The call is at 8:30 AM ET / 1:30 PM GMT.
PFE · Pfizer · Morning · ~$175B Watching: whether it keeps its 2026 guidance. Consensus is $0.73 a share (MarketBeat), and the call is at 10:00 AM ET / 3:00 PM GMT.
WEDNESDAY, November 4
China Services PMI, RatingDog (October) · Tuesday 8:45 PM ET / Wednesday 1:45 AM GMT The private survey of Chinese services firms was 51.6 in September.
⚡⚡ Eurozone Flash Inflation (October) · 5:00 AM ET / 10:00 AM GMT Consensus is 3.9% (FXStreet) after 3.8% in September, with core seen steady at 2.5%, the first eurozone figure since the ECB held at 2.50% last week. On the EU harmonised measure, France already printed 3.8% and Italy 5.6% for October, both above expectations (Newsquawk, Istat).
Riksbank Decision · 3:30 AM ET / 8:30 AM GMT Sweden’s central bank is expected to raise its rate to 2.00% from 1.75% (Newsquawk), with Nordea, SEB, Handelsbanken and ING all calling for a rise.
⚡ US ADP Employment (October) · 8:15 AM ET / 1:15 PM GMT Consensus is 65,000 (FXStreet) after 90,000 in September, 2 days before the official payrolls figure.
⚡ US Treasury Quarterly Refunding · 8:30 AM ET / 1:30 PM GMT The plan for which bonds the government sells and in what sizes, and Barclays expects no change to auction sizes with the 10-year yield near 4.93%. (US Treasury)
US Trade Balance (September) · 8:30 AM ET / 1:30 PM GMT Rio Times has a deficit of $107.6 billion after $105.6 billion. (BEA)
US S&P Global Services PMI, Final (October) · 9:45 AM ET / 2:45 PM GMT The flash composite reading was 57.6.
⚡⚡ US ISM Services PMI (October) · 10:00 AM ET / 3:00 PM GMT Consensus is 54.8 (FXStreet) after 54.9, and services firms in S&P Global’s flash survey reported the fastest rise in selling prices since August 2022.
EARNINGS
⚡ ARM · Arm Holdings · After Close · ~$220B Watching: royalty revenue from data centre chips. Consensus is $0.48 a share (MarketBeat) for its fiscal second quarter, and the call is at 5:00 PM ET / 10:00 PM GMT.
⚡ NVO · Novo Nordisk · European Morning · ~$175B Watching: weight-loss drug sales against cheaper rivals. Consensus is $0.73 a share (MarketBeat, US-listed shares).
⚡ QCOM · Qualcomm · After Close · ~$175B Watching: phone chip sales and its guide for the December quarter. Consensus is $2.17 a share (MarketBeat) for its fiscal fourth quarter, and the call is at 4:45 PM ET / 9:45 PM GMT.
UBER · Uber · Before Open · ~$135B Watching: trip growth and its robotaxi partnerships. The call is at 8:00 AM ET / 1:00 PM GMT.
THURSDAY, November 5
⚡⚡⚡ Bank of England Decision · 7:00 AM ET / 12:00 PM GMT Bank Rate is 3.75% after a 6-3 vote to hold in September, and a rise to 4.00% is expected, with FXStreet’s consensus a 7-2 vote for the rise and the Monetary Policy Report out at the same time. Detail in The 3 Events That Matter Most below. (Bank of England)
Governor Andrew Bailey’s Press Conference · 7:30 AM ET / 12:30 PM GMT Bailey explains the decision and the new forecasts half an hour after the announcement.
Norges Bank Decision · 4:00 AM ET / 9:00 AM GMT Norway’s central bank is expected to hold at 4.50% after September’s rise (Newsquawk). (Norges Bank)
⚡ US Initial Jobless Claims · 8:30 AM ET / 1:30 PM GMT Consensus is 195,000 (FXStreet) after 194,000.
US Productivity and Unit Labour Costs (Q3) · 8:30 AM ET / 1:30 PM GMT Output per hour worked rose 1.4% in the second quarter, and the first Q3 estimate lands a week after the Fed’s statement said “productivity growth is strong”. (BLS)
Fed’s Beth Hammack · 8:50 AM ET / 1:50 PM GMT The Cleveland Fed president speaks a week after she dissented in favour of a rise (Kiplinger).
Canada Federal Budget · All day Ottawa’s budget lands a week after the Bank of Canada decision.
ECB President Christine Lagarde · 11:00 AM ET / 4:00 PM GMT Lagarde speaks at an event in Milan, the day after the eurozone inflation figures. (ECB)
EARNINGS
ABNB · Airbnb · After Close · ~$100B Watching: bookings for the fourth quarter. Consensus is $2.85 a share (MarketBeat), and the call is at 5:00 PM ET / 10:00 PM GMT.
FRIDAY, November 6
⚡⚡⚡ US Jobs Report (October) · 8:30 AM ET / 1:30 PM GMT Consensus is 65,000 jobs (FXStreet) after 29,000 in September, with Newsquawk at 55,000 and unemployment seen at 4.2%. Detail in The 3 Events That Matter Most below. (BLS)
Canada Jobs Report (October) · 8:30 AM ET / 1:30 PM GMT Consensus is 15,000 jobs (FXStreet) after Canada lost 68,000 in September, and the figures land at the same minute as the US report.
Fed’s John Williams · 4:30 AM ET / 9:30 AM GMT The New York Fed president, a permanent voter, speaks before the payrolls report.
Eurozone Retail Sales (September) · 5:00 AM ET / 10:00 AM GMT Consensus is 0.6% on the year (FXStreet) after 0.8%.
Fed’s Alberto Musalem · 9:10 AM ET / 2:10 PM GMT The St. Louis Fed president said last Friday that rates would need to rise again soon (investingLive).
US UMich Consumer Sentiment (November, Preliminary) · 10:00 AM ET / 3:00 PM GMT Consensus is 48.2 (FXStreet) after 48, with year-ahead inflation expectations at 4.7% last month. (University of Michigan)
BoJ Governor Kazuo Ueda · 11:00 AM ET / 4:00 PM GMT Ueda gives the IMF’s Michel Camdessus Central Banking Lecture in Washington. (Bank of Japan)
Fed’s Michelle Bowman · 12:15 PM ET / 5:15 PM GMT The Vice Chair for Supervision discusses bank supervision and regulation at the University of Mississippi. (Federal Reserve)