

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
The Fed has gone silent. Its quiet period started on Saturday and runs until the day after the 28 October decision, so no official can talk the market up or down this week. That leaves the companies and the rest of the world to do the talking. Meta, Tesla, IBM, Texas Instruments, Lam Research and SAP all report on Wednesday after the close, hours after UK inflation lands that morning. Brent settled at $109.86 on Friday, its highest since May, and Friday’s flash PMIs give the first read on what that is doing to prices inside businesses.
Last Week:
US CPI (September) Prices rose 0.6% on the month and 3.7% on the year. Core, which strips out food and energy, rose 0.3% on the month and 2.6% on the year, up from 2.4%. Petrol jumped 9.1% and did more than half of the headline’s work. The S&P 500 fell 1.10% that day and CME FedWatch briefly put a 28 October rise at about 1 in 2. (BLS, Axios)
US PPI and Retail Sales (September) Wholesale prices rose 1.3% on the month and 6.3% on the year. Excluding food, energy and trade, the rise was 0.5% on the month and 5.0% on the year. Retail sales rose 0.8%, but the control group, the slice that feeds into GDP, rose just 0.1%. Energy made up more than 80% of the wholesale jump. The 10-year yield fell about 12 basis points that day. (BLS, Babypips)
The Big Banks Q3 JPMorgan earned $5.57 a share against forecasts of about $5.90, with costs up 12% and revenue up 8%, and it gave a first 2027 net interest income case of about $107 billion excluding markets. Goldman earned $17.01 on a 72% jump in equities trading to $6.44 billion. Bank of America took a $1.2 billion Treasury penalty, earned $0.91 a share and closed 4.76% lower on Wednesday. Citigroup guided fourth quarter markets revenue down about 20%. (TradingNews, Yahoo Finance, Citigroup)
TSMC Q3 Net income hit a record NT$763.1 billion, about $23.6 billion, up 69%, on revenue of $46.72 billion. The fourth quarter guide of $52.3 billion to $54.3 billion sat above the $50.48 billion consensus. The shares still fell as much as 5.1% in New York, in a week when the chip index fell for 8 straight days. (Investing.com, Techloy)
The setup: Fed Chair Kevin Warsh told the Bangkok audience “I don’t prejudge meetings” and said the world “has broadly conformed to our expectations”. October odds fell back below 1 in 5 after he spoke, with CME FedWatch at 17% for October and 89% for December on Friday, as reported by Yahoo Finance. The S&P 500 closed Friday at 7,659, down 1.95% on the week, and the Nasdaq fell 4.48%, its worst week since June. Brent settled at $109.86 after Iran said 2 tankers hit mines in Hormuz, which has not been independently confirmed. With the Fed silent, Wednesday’s results and Friday’s PMIs are the last big reads before 28 October. (Axios, Yahoo Finance, Investrade)
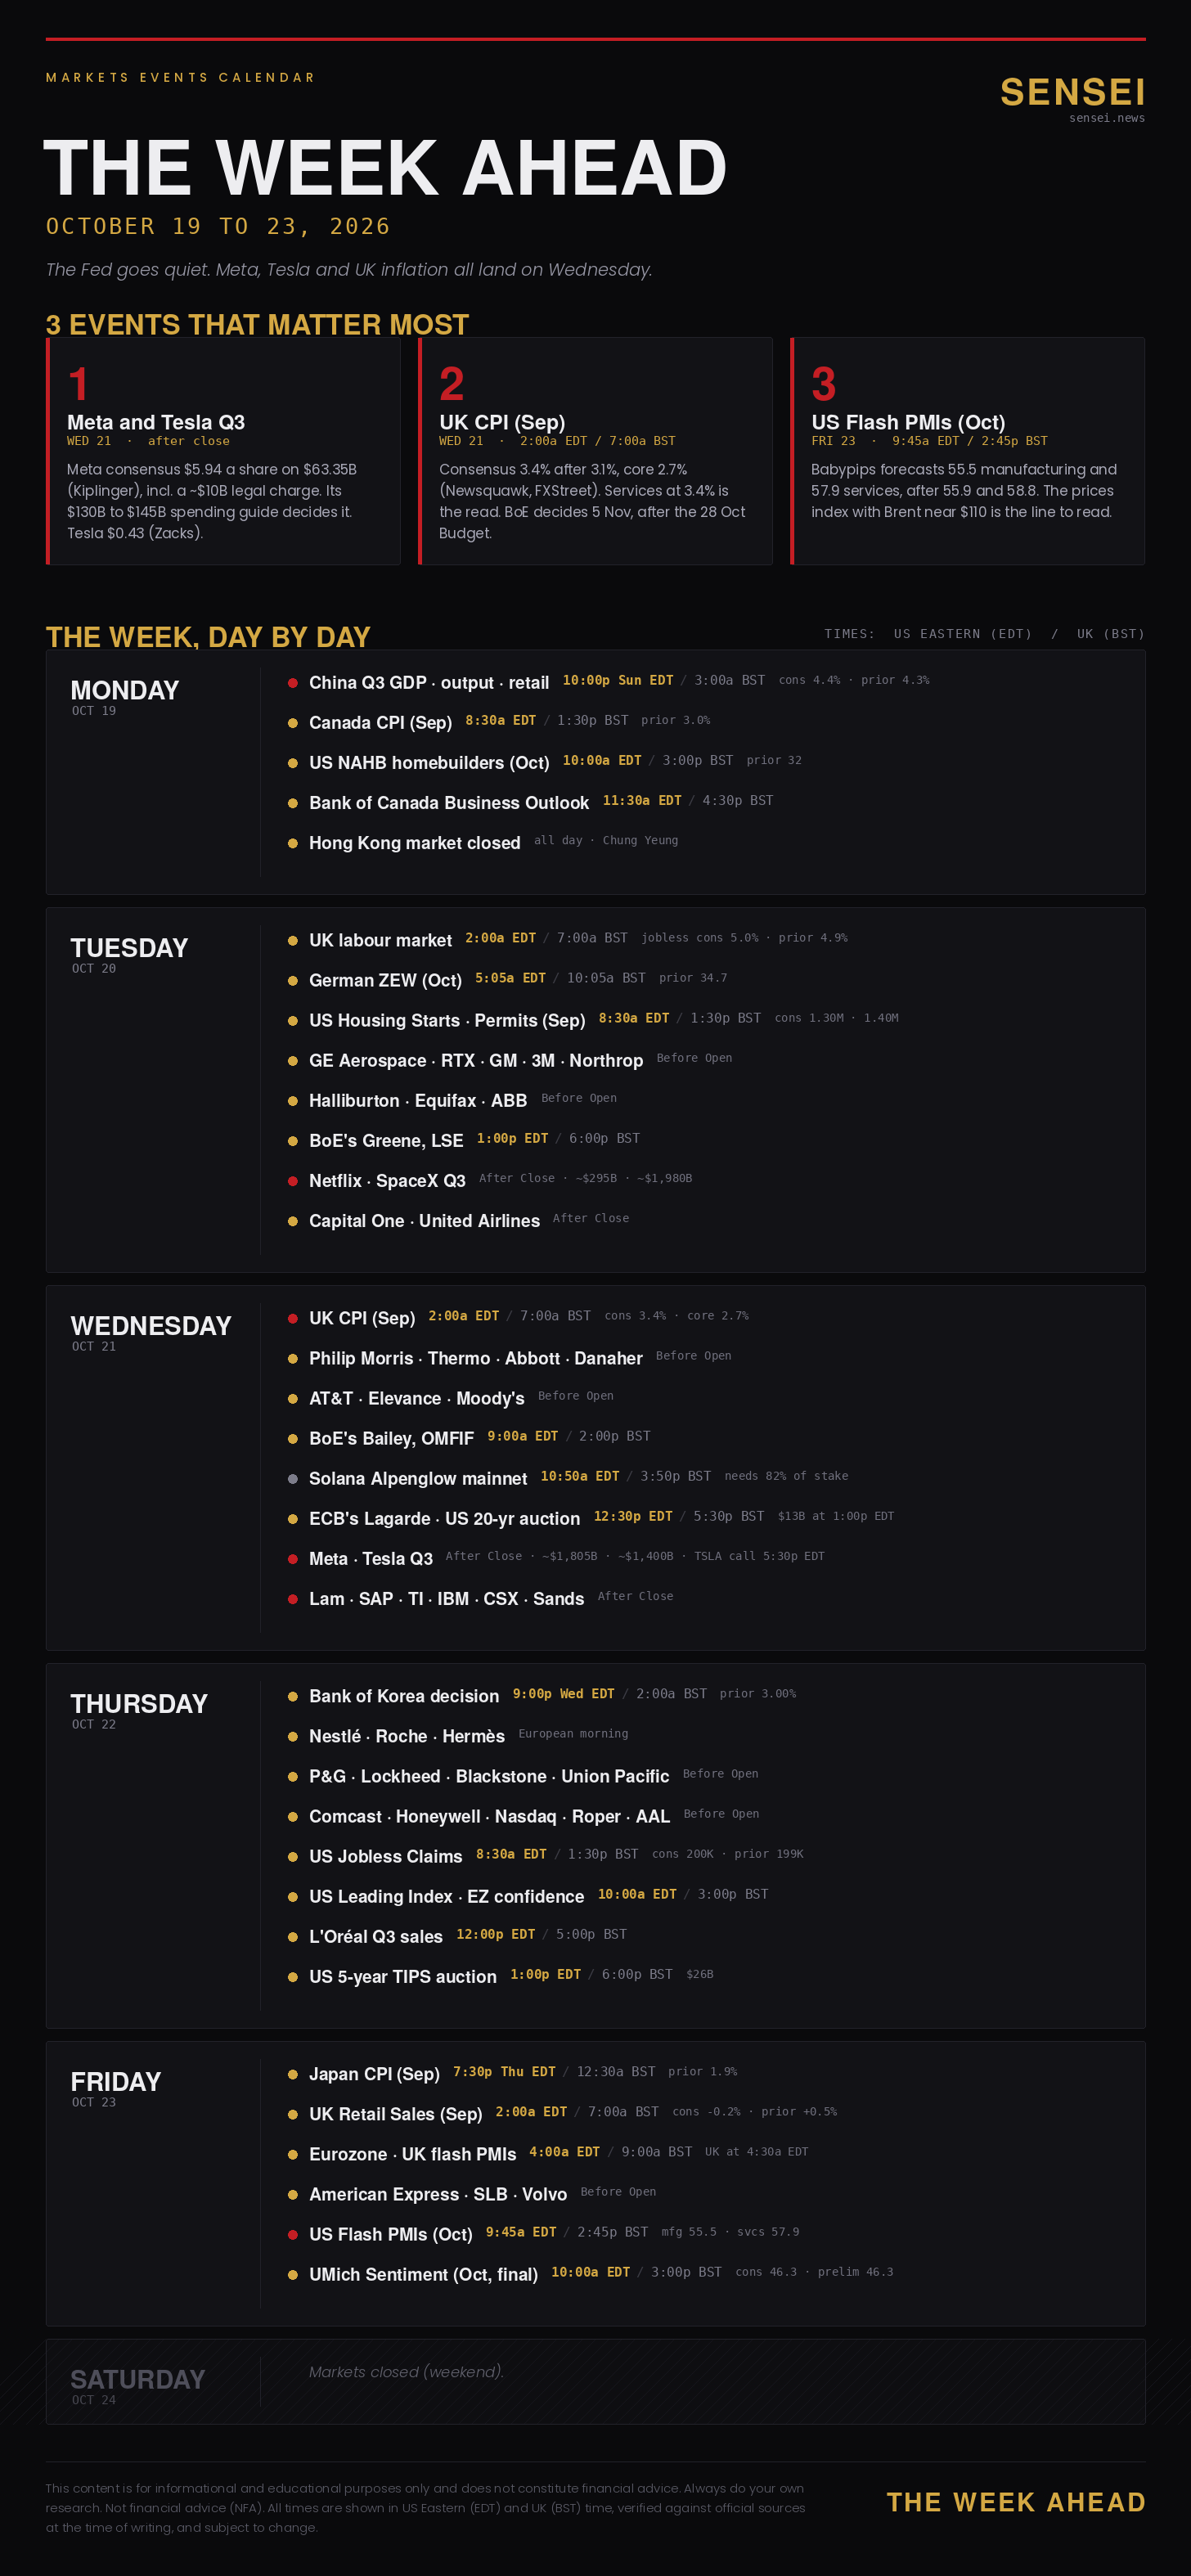
Week at a Glance
🔴 Meta, Tesla, IBM, Texas Instruments, Lam Research and SAP Q3 Results: Wednesday, After Close
🔴 UK CPI (September): Wednesday, 2:00 AM ET / 7:00 AM BST
🔴 US Flash PMIs (October): Friday, 9:45 AM ET / 2:45 PM BST
🔴 Netflix and SpaceX Q3 Results: Tuesday, After Close
🔴 China Q3 GDP: Sunday, 10:00 PM ET / Monday, 3:00 AM BST
🟠 GE Aerospace, RTX, GM and 3M Q3 Results: Tuesday, Before Open
🟠 UK Labour Market: Tuesday, 2:00 AM ET / 7:00 AM BST
🟠 Procter & Gamble, Lockheed Martin, Blackstone and Union Pacific Q3 Results: Thursday, Before Open
🟡 Solana Alpenglow Upgrade: Wednesday, 10:50 AM ET / 3:50 PM BST