

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
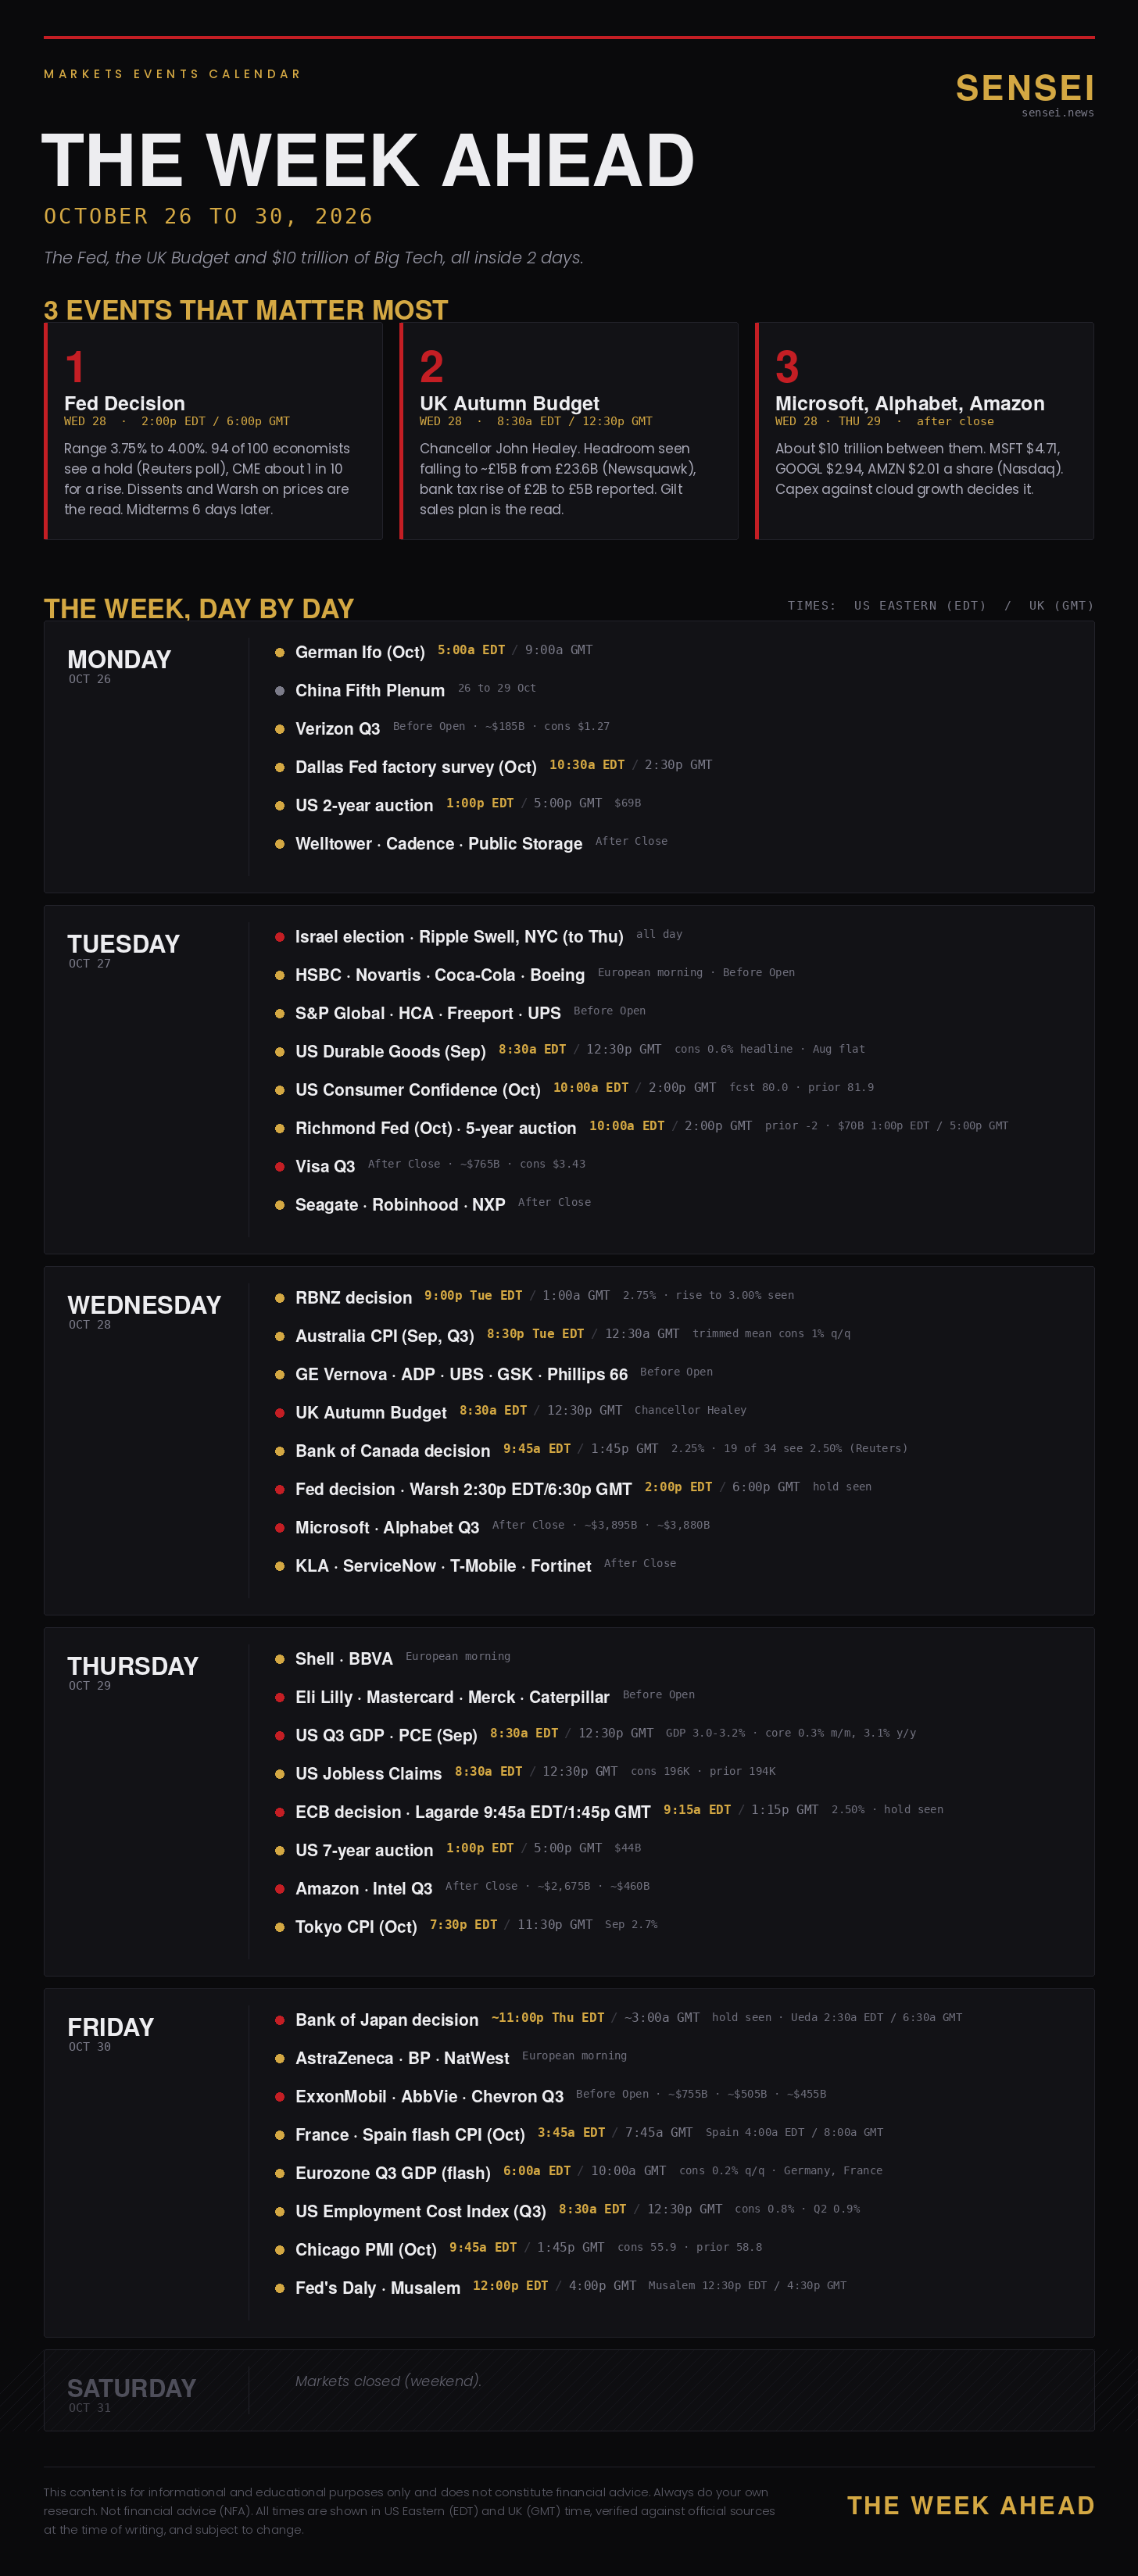
5 central banks decide this week, and the biggest of them meets with Brent at $116.72 and the 10-year Treasury yield at 5%. The Fed announces on Wednesday afternoon, a few hours after the UK Budget and 2 hour before Microsoft and Alphabet report. Thursday morning then brings US growth and the Fed’s preferred inflation gauge for September, the day after the decision it would normally inform. Amazon reports that evening, and the Bank of Japan closes the week on Friday. UK clocks went back on Sunday and the US does not change until 1 November, so this week the gap between New York and London is 4 hours.
Last Week:
Meta and Tesla Q3 Meta reported revenue of $64.6 billion, up 26%, and narrowed its 2026 spending range to $135 billion to $145 billion. Capital spending of $34.91 billion ran ahead of the $32.79 billion of cash its operations brought in, and it gave no 2027 figure. The shares closed 6.98% lower at $648.85 on Thursday, the day the Nasdaq had its worst session since June. Tesla went the other way on spending: it cut its capital budget to about $20 billion from more than $25 billion and earned $0.48 a share against a $0.43 consensus (Zacks).
UK CPI (September) 3.5%. Consensus was 3.4%, and August was 3.1%. Core inflation rose to 2.8% from 2.6% and services to 3.7% from 3.4%, so the rise reached beyond the pump, where petrol averaged 169.5p, the highest since August 2022. The Bank of England decides on 5 November, a week after Wednesday’s Budget. (ONS)
US Flash PMIs (October) Manufacturing printed 56.0 against 55.5 expected and services 57.9 against 58.0, with the composite at 57.6 after 58.4. The output prices index rose to 59.8, its highest since August 2022. Chris Williamson of S&P Global said the reading “indicates consumer price inflation is likely to rise further above the Fed’s target in the coming months”. (investingLive, Newsquawk)
The setup: the S&P 500 closed Friday at 7,623.68, down 0.47% on the week, and the Nasdaq fell 0.71%, a second straight weekly loss for both. Brent’s December contract settled $3.55 higher at $116.72 on Friday, and the 10-year yield ended at 4.99%. CME FedWatch pricing on Friday implied about a 1 in 10 chance of a rise on Wednesday and close to a full rise by December. Wednesday’s decision comes 6 days before the 3 November midterms, with business surveys showing the fastest price rises in more than 4 years. (investingLive, Newsquawk)
Week at a Glance
🔴 Fed Decision and Warsh Press Conference: Wednesday, 2:00 PM ET / 6:00 PM GMT
🔴 UK Autumn Budget: Wednesday, 8:30 AM ET / 12:30 PM GMT
🔴 Microsoft and Alphabet Q3 Results: Wednesday, After Close
🔴 US Q3 GDP and September PCE Inflation: Thursday, 8:30 AM ET / 12:30 PM GMT
🔴 Amazon Q3 Results: Thursday, After Close
🟠 ECB Decision: Thursday, 9:15 AM ET / 1:15 PM GMT
🟠 Bank of Japan Decision: Thursday Night ET / Friday Morning GMT
🟠 Bank of Canada Decision: Wednesday, 9:45 AM ET / 1:45 PM GMT
🟡 Ripple Swell, New York: Tuesday to Thursday, All day