

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
A week ago the futures market put the odds of another Federal Reserve rate rise on 28 October at roughly 2 in 3. Then September payrolls came in at 29,000 jobs with unemployment up to 4.2%, and CME FedWatch had those odds at about 1 in 6 by Friday afternoon. Wednesday’s minutes cover the 16 September meeting, where the vote to raise rates was unanimous and the median official pencilled in one more rise this year. How united were they on the next step? The minutes are the first written record of that argument, and they land 2 days after the ISM services survey and in the same week Treasury sells $61 billion of 10 and 30-year debt.
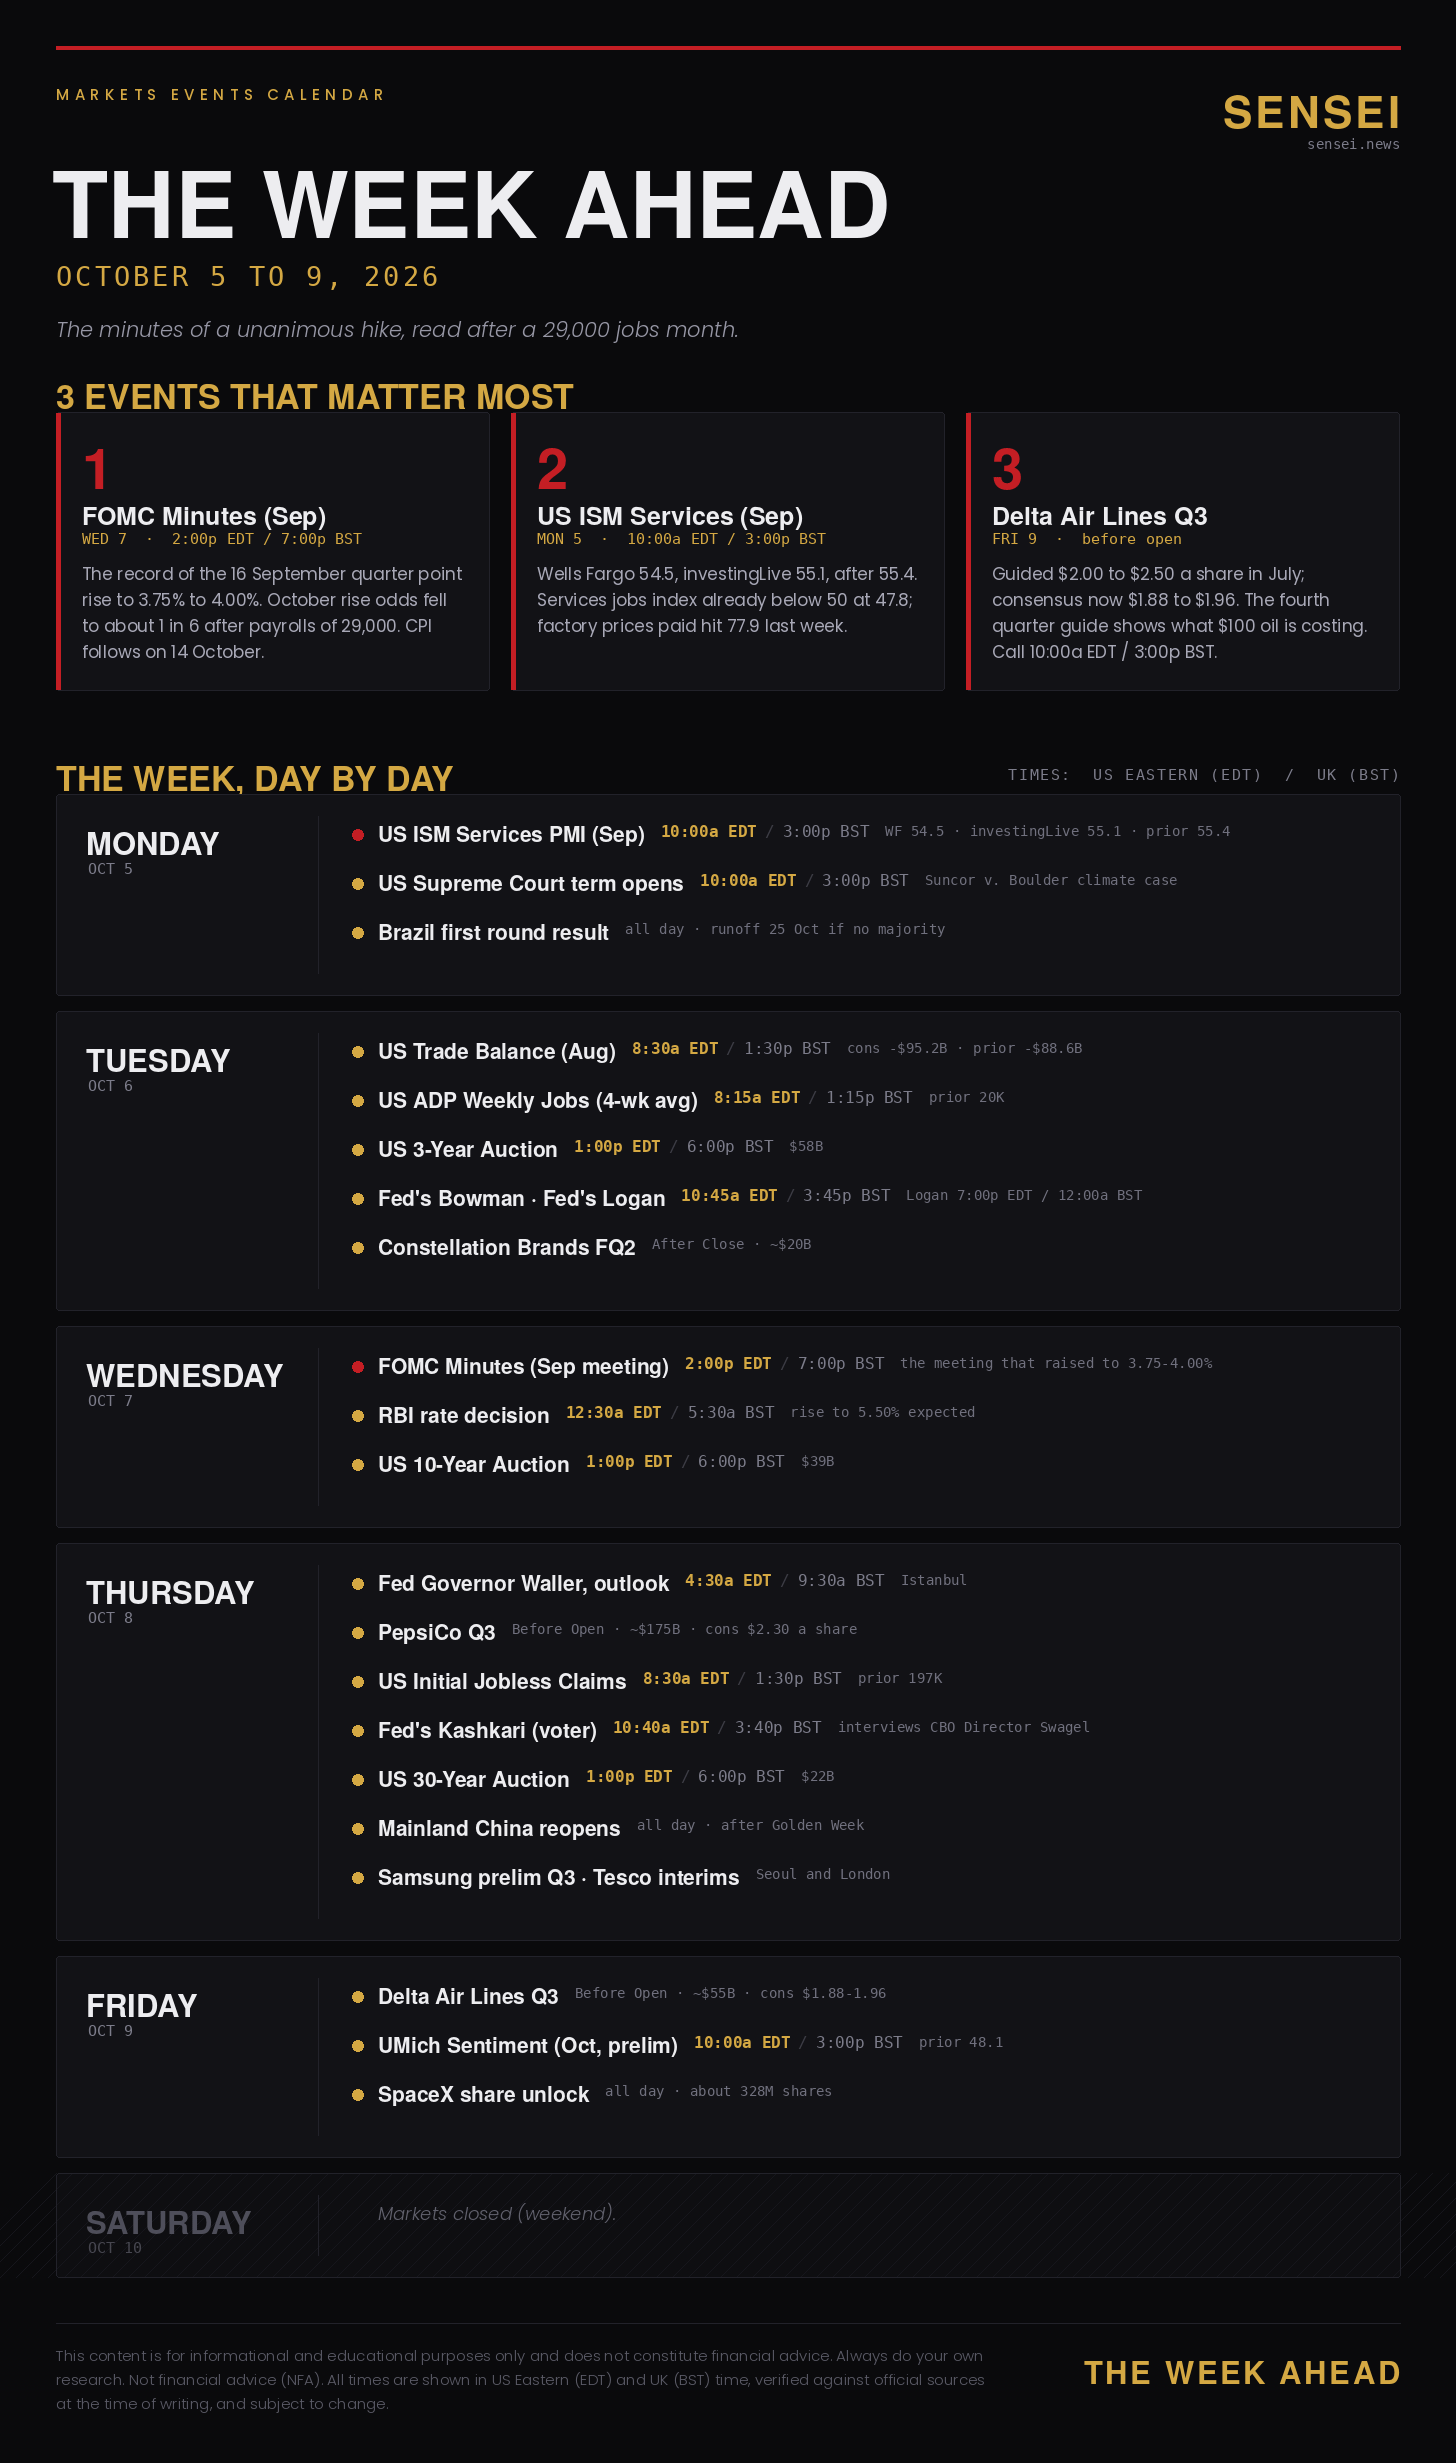
This Week at a Glance:
🔴 FOMC Minutes (September Meeting): Wednesday, 2:00 PM ET / 7:00 PM BST
🔴 US ISM Services PMI (September): Monday, 10:00 AM ET / 3:00 PM BST
🟠 Delta Air Lines Q3 Results: Friday, Before Open
🟠 PepsiCo Q3 Results: Thursday, Before Open
🟠 Fed Governor Christopher Waller Speaks: Thursday, 4:30 AM ET / 9:30 AM BST
🟠 US 10-Year and 30-Year Treasury Auctions: Wednesday and Thursday, 1:00 PM ET / 6:00 PM BST
🟠 University of Michigan Sentiment (October, Preliminary): Friday, 10:00 AM ET / 3:00 PM BST
🟠 SpaceX Share Unlock: Friday, All day
🟠 US Initial Jobless Claims: Thursday, 8:30 AM ET / 1:30 PM BST
Last Week:
US Nonfarm Payrolls (September) 29,000. The Reuters poll had 90,000. Unemployment rose to 4.2% from 4.1%, and average hourly earnings rose just 0.1% on the month. July and August were revised down by a combined 60,000, with July now showing a loss of 10,000 jobs. Odds of an October rise fell to about 17% on CME FedWatch, and the S&P 500 closed Friday up 0.73% at 7,722.72.
US PCE Price Index (August) Core inflation rose 0.2% on the month and 3.0% on the year, against forecasts of 0.3% and 3.3%. Part of the gap came from the Bureau of Economic Analysis’s annual revision, which rewrote the data back to 2021. Spending jumped 0.9%, or 0.6% after inflation, up from 0.1% in July. Americans kept buying even as the inflation number cooled.
Micron Fiscal Q4 (quarter to August) Revenue came in at $54.23 billion against about $51.1 billion expected in LSEG’s survey, with earnings of $33.42 a share and a gross margin of 86.8%. Guidance for this quarter is $60 billion to $63 billion. Chief executive Sanjay Mehrotra said memory supply would be “much tighter in 2027 and 2028”, and the shares rose about 3% on Thursday before giving back 2.05% on Friday to $1,074.89.
Eurozone Flash Inflation (September) Prices rose 3.8% on the year against 3.7% expected in Bloomberg’s survey and 3.2% in August, the highest in about 3 years, with energy up 18.8%. Core rose to 2.5% from 2.4%. After the print, traders trimmed bets on an ECB rise at the 28 and 29 October meeting, with some banks expecting the ECB to wait for December. At least one more rise this year is still widely expected.
The setup: Australia raised its cash rate to 4.60% on Tuesday, its fourth rise this year. ISM’s prices paid index for American factories jumped to 77.9 from 71.1, just below the 78.3 of March, when the Iran war began, and OPEC+ held November output targets unchanged on Sunday with Brent at $102.25 on Friday’s settle. Tesla delivered 486,532 cars in the third quarter against 461,974 expected and closed Friday up 4.65%, with its results confirmed for 21 October after the close. The Fed’s own record of September is what this week adds, before September CPI on 14 October.