

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
Sensei Desk goes live in the next couple of days. Company research, clear financial charts and Sensei Score, all included with your Sensei News premium membership.
Want access at launch? Upgrade using the subscribe button below. Already a premium member? You’re included. Look out for the launch announcement and access instructions.
You can take a first look at now.
https://desk.sensei.news/
Member access opens shortly.
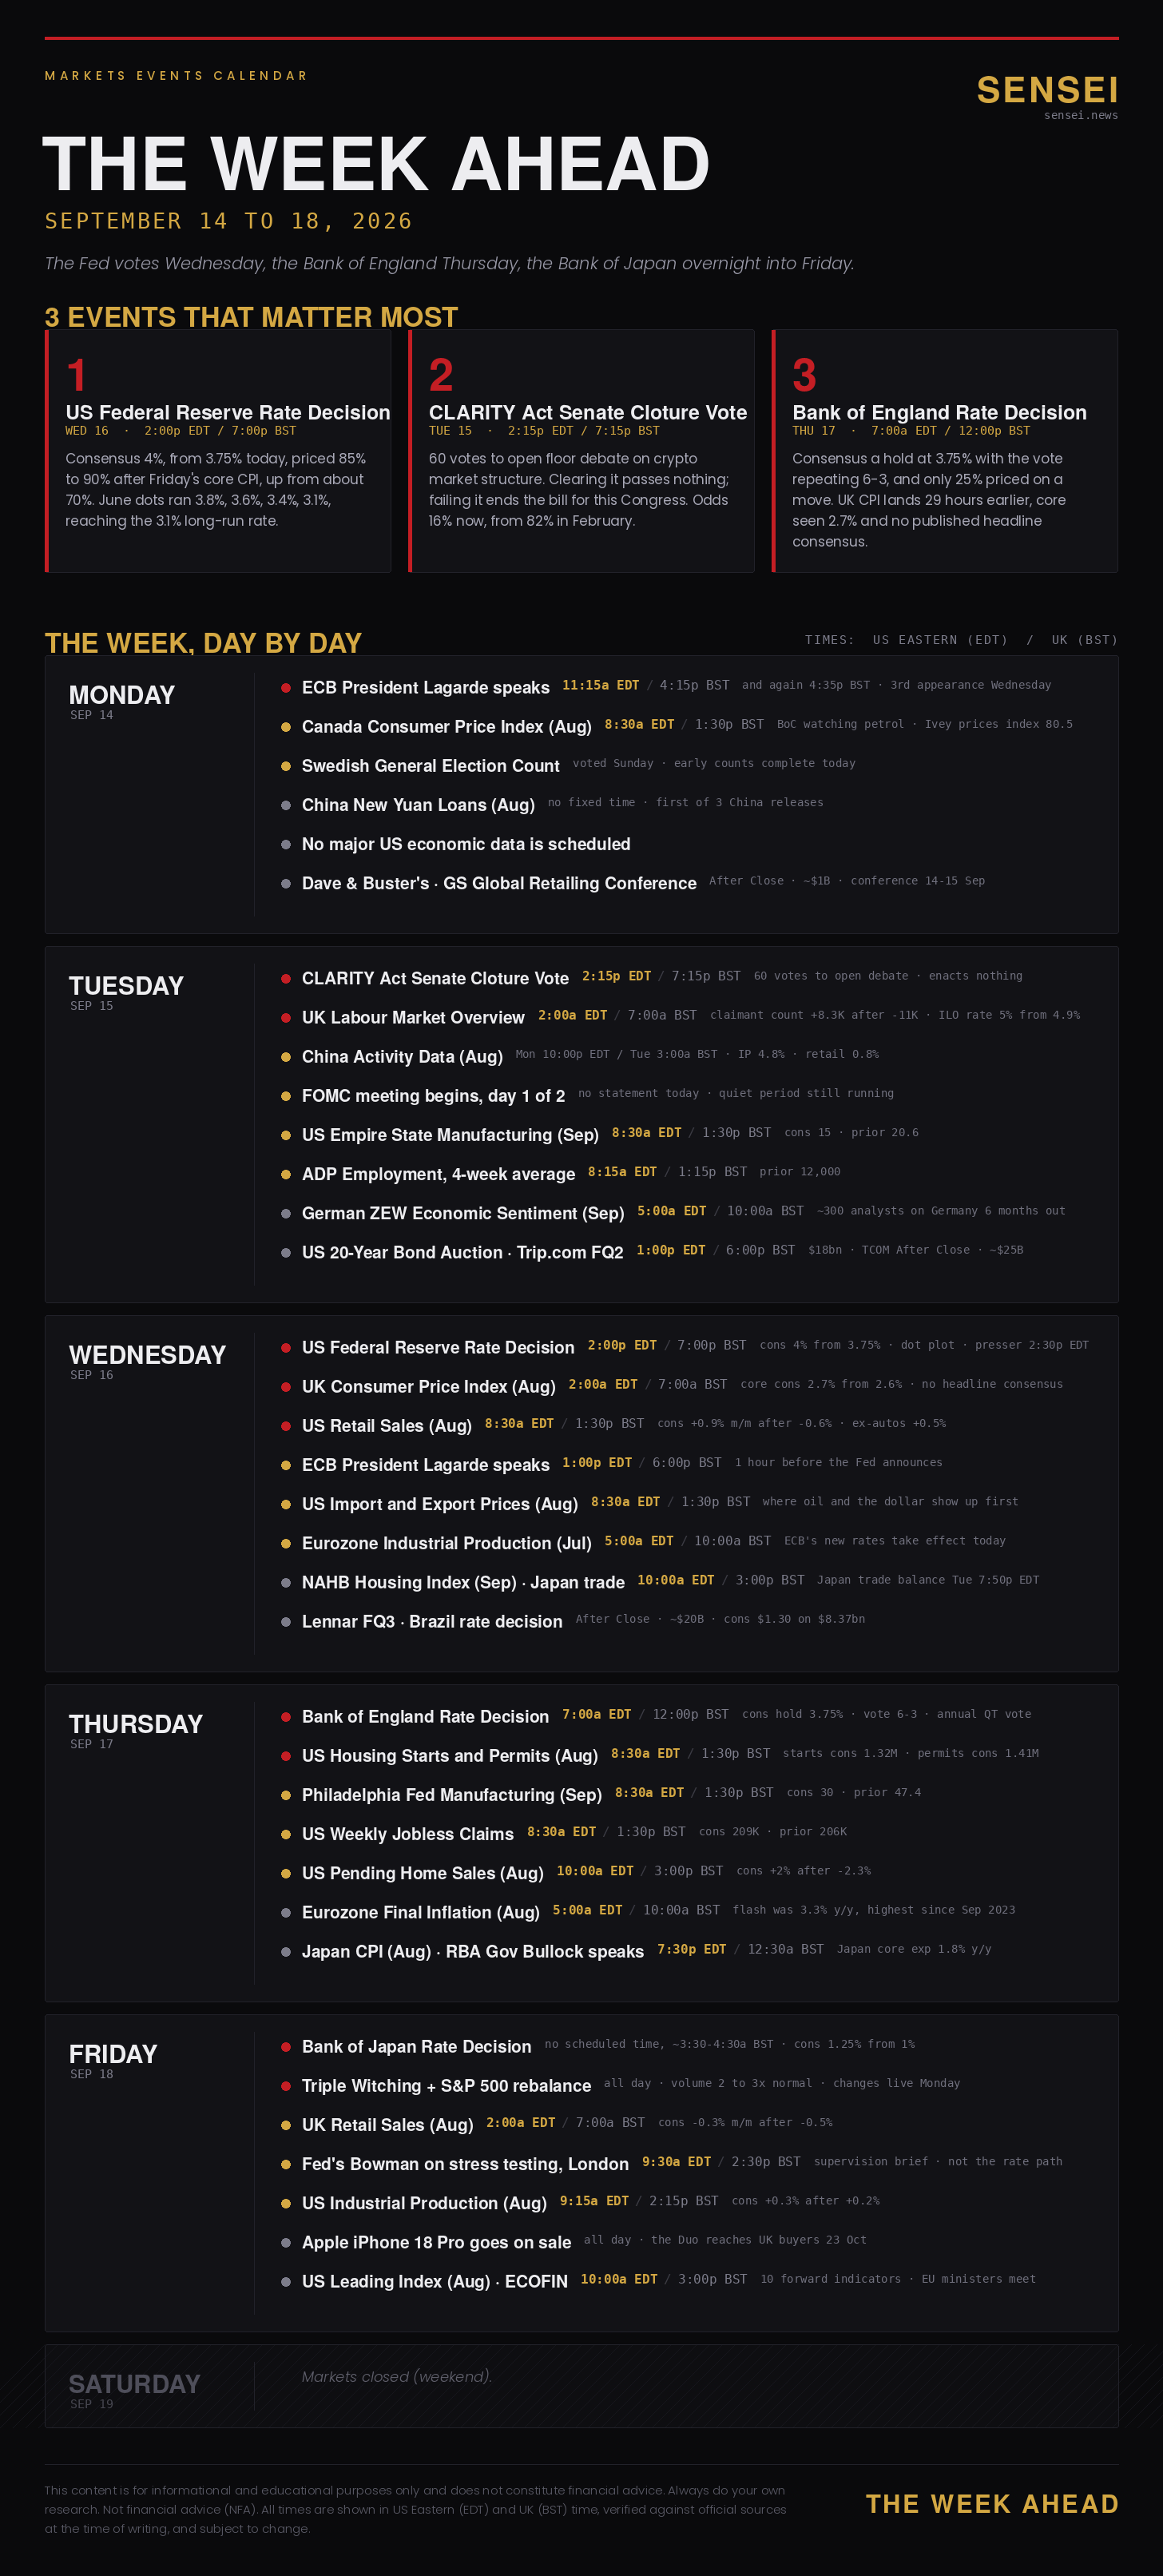
Consensus for Wednesday’s Federal Reserve decision is 4%. The top of the range sits at 3.75% today, so the base case going in is a rise. The Bank of England follows on Thursday lunchtime and the Bank of Japan overnight into Friday, where consensus is 1.25% against 1% now. That is 3 decisions inside 48 hours, and all 3 arguments are about going up. British inflation lands on Wednesday morning, about 29 hours before the Bank of England votes.
Last Week:
US Consumer Price Index (August) Headline inflation held at 3.4% on the year and rose 0.4% on the month, both in line with forecasts. Core rose 0.29% on the month against 0.22% expected, and petrol did more than a third of the monthly increase on its own. Futures pricing for a rise on Wednesday moved to between 85% and 90%, from about 70% before the release.
Bank of England at the Treasury Committee Governor Andrew Bailey told MPs that the market curve for higher rates carries a risk premium for a worse energy outcome rather than a hidden Bank plan, and that any move still depends on the data and on geopolitics. The rates market prices a 25% chance of a rise on Thursday, with a full quarter point priced for November and another for December.
Oracle Q1 (quarter to 31 August) Revenue grew 30% to $19.3 billion against $19.13 billion expected, adjusted earnings came in at $1.92 a share against $1.75, and the contracted backlog reached $664 billion. The shares gave up a 6% intraday gain and closed Friday down 1.74% at $150.28, because capital spending has gone to $28.50 billion from $8.50 billion a year earlier and free cash flow is running at minus $5.4 billion.
The setup: payrolls added 162,000 jobs in August against a 56,000 forecast, producer prices ran at 5.4% on the year, and core inflation then came in a tenth above consensus. A central bank that wanted a reason to wait no longer has one. Wednesday’s projections are the first since June, when the median official had 3.8% for the end of this year, 3.6% for 2027, 3.4% for 2028, 3.1% for 2029 and 3.1% in the long run.
Week at a Glance
🔴 US Federal Reserve Rate Decision: Wednesday, 2:00 PM ET / 7:00 PM BST
🔴 CLARITY Act Senate Cloture Vote: Tuesday, 2:15 PM ET / 7:15 PM BST
🔴 UK Consumer Price Index (August): Wednesday, 2:00 AM ET / 7:00 AM BST
🔴 Bank of England Rate Decision: Thursday, 7:00 AM ET / 12:00 PM BST
🔴 Bank of Japan Rate Decision: Friday, no scheduled announcement time
🟠 US Retail Sales (August): Wednesday, 8:30 AM ET / 1:30 PM BST
🟠 UK Labour Market Overview: Tuesday, 2:00 AM ET / 7:00 AM BST
🟠 Triple Witching and the S&P 500 Rebalance: Friday, All day
🟠 China Activity Data (August): Monday 10:00 PM ET / Tuesday 3:00 AM BST