

This content is for informational and educational purposes only and does not constitute financial advice. Always do your own research. Not financial advice (NFA).
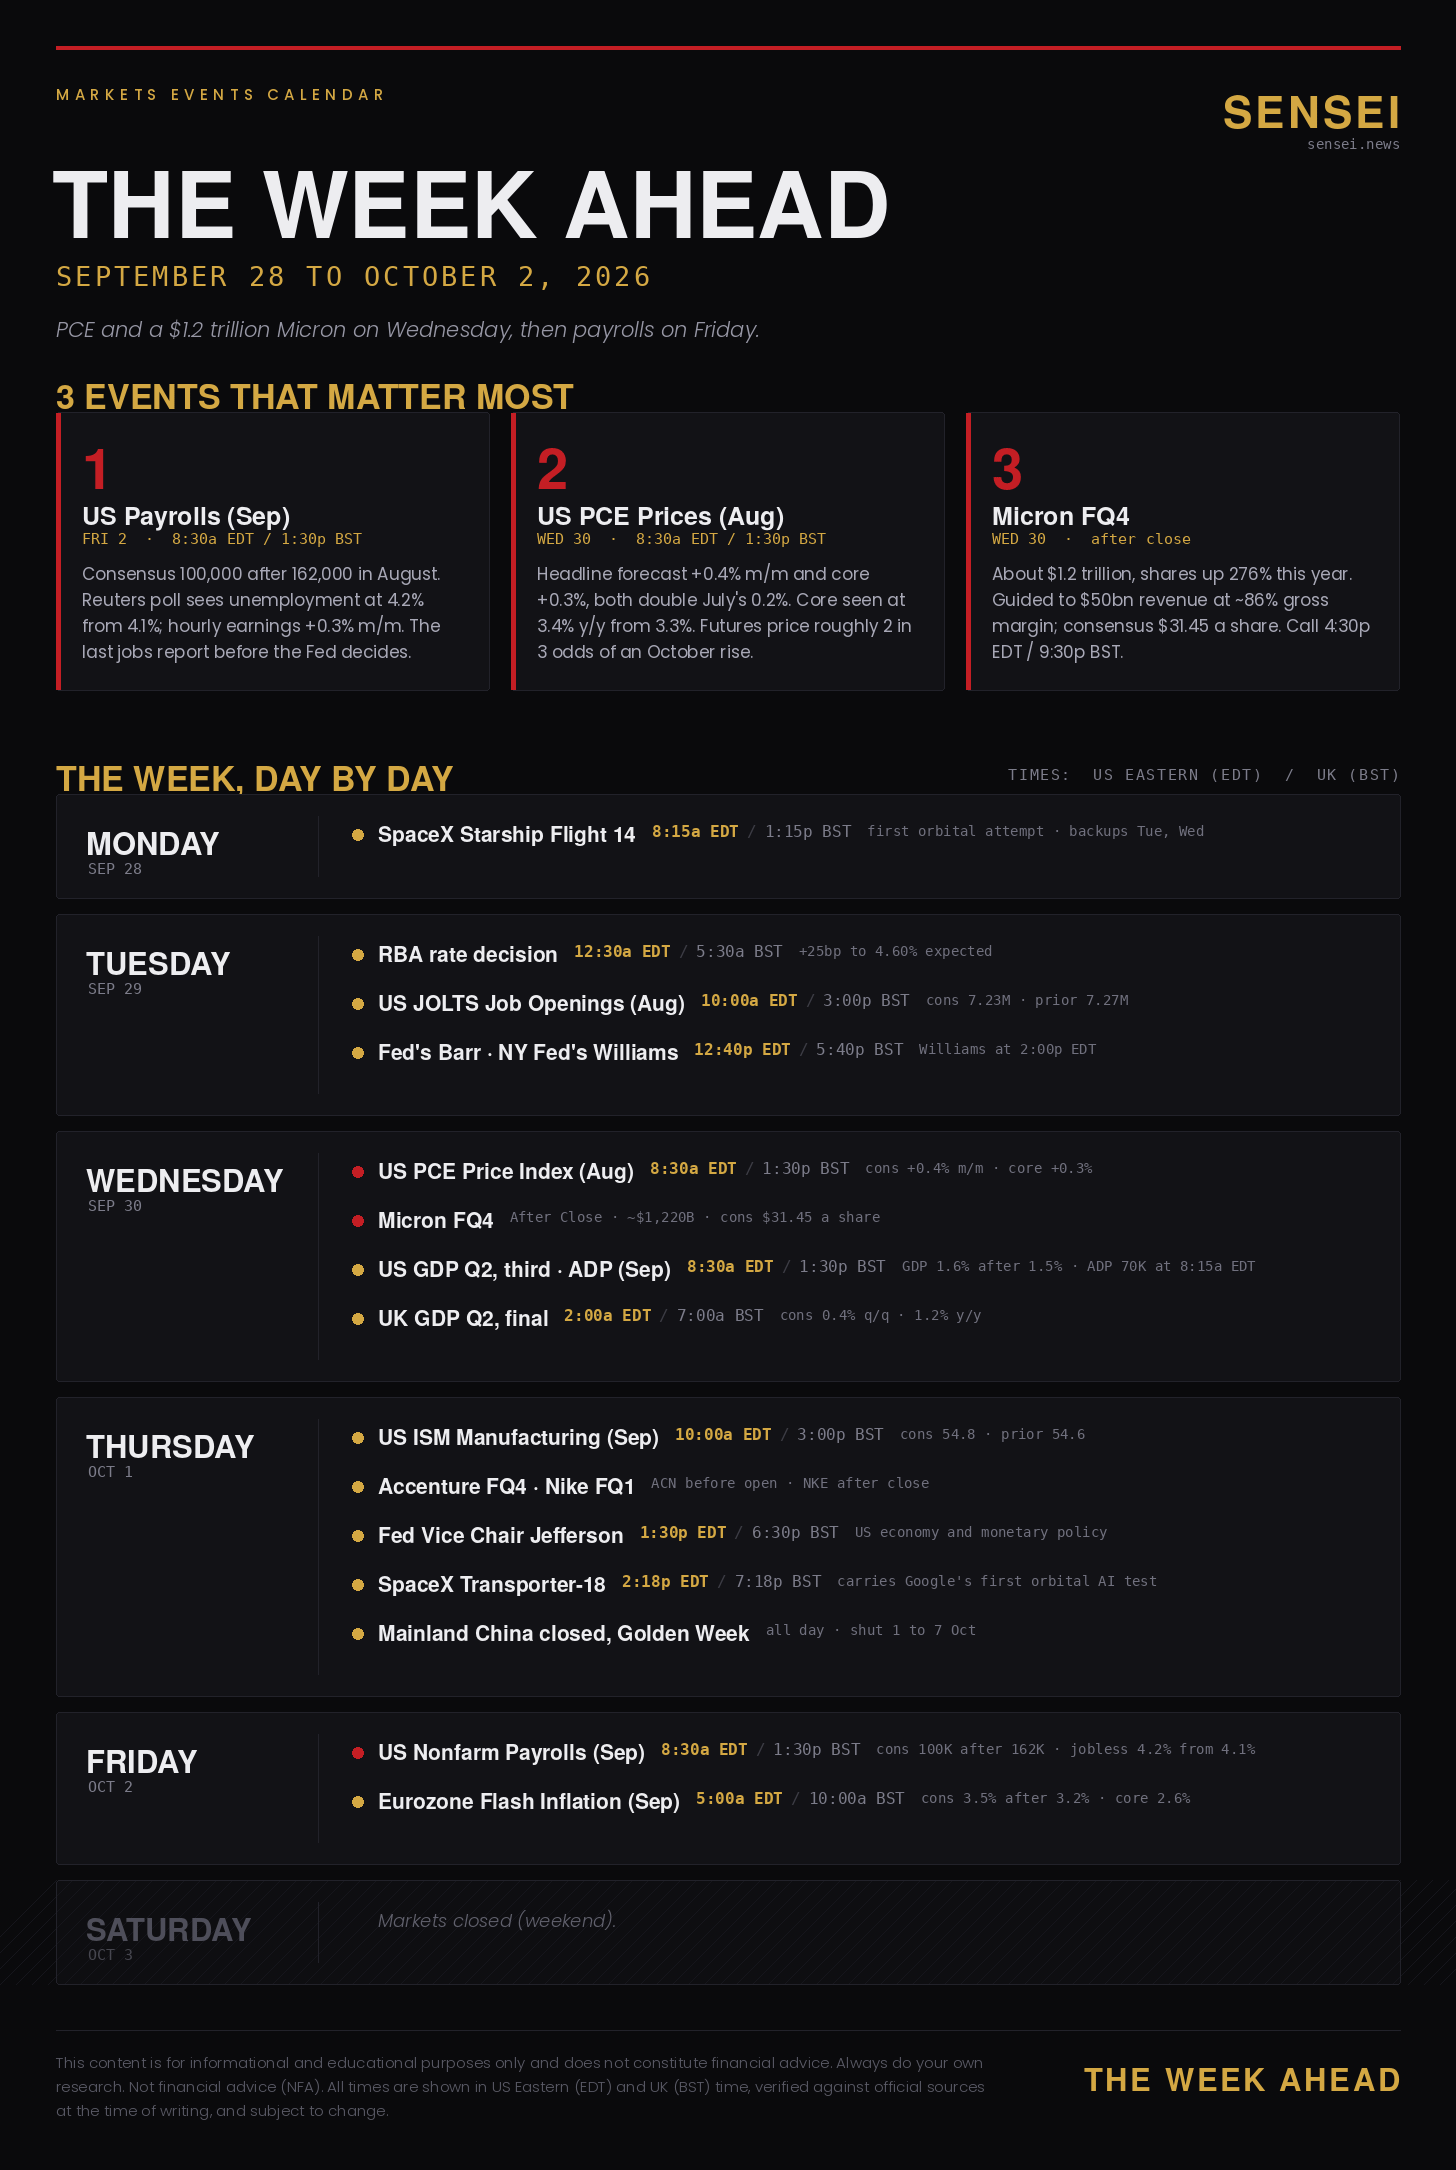
The odds of another Federal Reserve rate rise on 28 October went into the weekend at roughly 2 in 3. This week brings the 2 American numbers most likely to move them. PCE inflation for August lands on Wednesday, forecast up 0.4% on the month, and September payrolls follow on Friday with 100,000 jobs expected. Hot prices and steady hiring would make October hard to avoid, and a soft jobs number would give the Committee a reason to wait. Micron reports on Wednesday night as a $1.2 trillion company, the biggest single read on AI spending this week.
Last Week:
Xi Jinping’s State Visit to the White House (24 September) Trump and Xi extended their tariff truce by 2 months to 10 January, agreed an AI safety channel, and set further meetings in China in November and Florida in December. The new commitments were narrow, among them Chinese purchases of American coal in 2027 and 2028 and fresh export controls on the chemicals used to make fentanyl. Hong Kong’s Hang Seng fell on Friday, the first session after the state dinner.
Federal Reserve Speakers (September) Governor Michael Barr said on Wednesday that “further policy adjustments are likely to be needed”, and Philadelphia’s Anna Paulson said “some modest further tightening may be warranted”. New York’s John Williams called another rise by the end of the year “reasonable” on Thursday, while declining to commit to October. Futures pricing for an October rise went from about 53% on Wednesday to 77.5% straight after Williams spoke, and settled near 2 in 3 by Friday’s close.
US S&P Global Flash PMI (September) The composite, which combines factories and services, jumped to 58.4 from 56.0, the fastest growth since July 2021, with manufacturing at a 52-month high of 57.0. Input costs rose at the steepest pace in 4 years, and the 10-year Treasury yield rose 15 basis points that day to close at 5.11%, its highest since 2007. It finished the week at 5.17%, which is where this week’s PCE and payrolls land.
Costco Q4 (quarter to 30 August) Earnings came in at $6.75 a share, including a one-off 15 cents from tariff refunds, on net sales of $93.9 billion. Membership fee income rose 7.3% to $1.85 billion with a renewal rate of 89.8%, and the shares rose 2.93% on Friday to $922.77.
The setup: Norway raised rates to 4.50% on Thursday and South Africa to 7.25% the day before, while Sweden held and signalled rises starting this year. Australia is expected to follow on Tuesday. In America, August durable goods orders came in flat against a forecast fall, and orders for core capital goods, the slice that tracks business investment, jumped 1.6%. The final University of Michigan reading put sentiment at 48.1, with households expecting 4.6% inflation over the next year.
Week at a Glance
🔴 US Nonfarm Payrolls (September): Friday, 8:30 AM ET / 1:30 PM BST
🔴 US PCE Price Index (August): Wednesday, 8:30 AM ET / 1:30 PM BST
🔴 Micron Q4 Results: Wednesday, After Close
🟠 US ISM Manufacturing PMI (September): Thursday, 10:00 AM ET / 3:00 PM BST
🟠 Eurozone Flash Inflation (September): Friday, 5:00 AM ET / 10:00 AM BST
🟠 Reserve Bank of Australia Rate Decision: Tuesday, 12:30 AM ET / 5:30 AM BST
🟠 US JOLTS Job Openings (August): Tuesday, 10:00 AM ET / 3:00 PM BST
🟠 Accenture and Nike Results: Thursday, Before Open and After Close
🟠 SpaceX Starship Flight 14: Monday, 8:15 AM ET / 1:15 PM BST
MONDAY, September 28
⚡⚡ SpaceX Starship Flight 14 · 8:15 AM ET / 1:15 PM BST The Federal Aviation Administration issued the launch licence late on Saturday for Starship’s first attempt to reach orbit, with a 75-minute window from Starbase in Texas and backup dates on Tuesday and Wednesday. Ship 41 carries 26 Starlink V3 satellites on a flight of just under 10 hours, the rocket’s first revenue-generating mission.
⚡ Bank of England Deputy Governor Dave Ramsden Speaks · 6:00 AM ET / 11:00 AM BST Ramsden, the Deputy Governor for Markets and Banking, speaks on quantitative tightening, the Bank’s run-down of the gilts it bought in past crises. The Committee’s 17 September decision put those holdings on a path to zero by the end of 2034, apart from £120 billion set aside to back banknotes.
⚡ ECB President Christine Lagarde Speaks · 9:30 AM ET / 2:30 PM BST Lagarde gives her introductory statement to the European Parliament’s economic affairs committee in Brussels, the regular hearing where MEPs question her on policy, 18 days after the ECB raised its deposit rate to 2.50%.
⚡ 2 Federal Reserve Governors Speak · From 8:15 AM ET / 1:15 PM BST Vice Chair for Supervision Michelle Bowman discusses bank supervision at 8:15 AM ET / 1:15 PM BST, and Governor Lisa Cook speaks on AI and emerging technology in Oakland at 1:25 PM ET / 6:25 PM BST. Both topics sit away from the rate path.
⚡ US Dallas Fed Manufacturing Index (September) · 10:30 AM ET / 3:30 PM BST Bloomberg’s consensus is 7.3 after 11.6 in August, and any reading above 0 means more Texas factories reported improving business than worsening.
EARNINGS
No company above $15 billion is scheduled to report.
Also reporting: Jefferies and Vail Resorts, both after the close.
TUESDAY, September 29
⚡⚡ Reserve Bank of Australia Rate Decision · 12:30 AM ET / 5:30 AM BST A Reuters poll found 33 of 34 economists expecting a quarter point rise to 4.60% from 4.35%, which would be the fourth this year and the highest cash rate since late 2011. Governor Michele Bullock’s press conference follows an hour later, 5 days after the jobless rate hit 4.6%, the highest since late 2021.
⚡⚡ US JOLTS Job Openings (August) · 10:00 AM ET / 3:00 PM BST Openings are forecast at 7.23 million after 7.27 million in July, the first of the week’s American labour market reports.
⚡⚡ Fed Governor Michael Barr Speaks · 12:40 PM ET / 5:40 PM BST Barr speaks on the economic outlook in Detroit, 6 days after he said “further policy adjustments are likely to be needed”.
⚡⚡ New York Fed President John Williams Speaks · 2:00 PM ET / 7:00 PM BST Williams gives remarks on the outlook and monetary policy at the University at Buffalo, with a text and questions expected, 5 days after he called another rise by the end of the year “reasonable”.
⚡ 3 More Federal Reserve Speakers · From 1:00 PM ET / 6:00 PM BST Chicago’s Austan Goolsbee takes questions at a manufacturers’ lunch at 1:00 PM ET / 6:00 PM BST, St. Louis’s Alberto Musalem is in conversation at the London School of Economics at 1:30 PM ET / 6:30 PM BST, and Governor Christopher Waller speaks on payments at 3:00 PM ET / 8:00 PM BST. Goolsbee and Musalem are not voters this year.
⚡ Prime Minister Andy Burnham Addresses the Labour Conference · All day Burnham gives his first conference speech as Prime Minister in Liverpool, 4 weeks before Chancellor John Healey’s first Budget on 28 October, and he has said the message will be “It’s time for Britain to have hope again”. The party has not published the hour.
⚡ US Conference Board Consumer Confidence (September) · 10:00 AM ET / 3:00 PM BST Consensus is 90.0 after 89.4, 4 days after the University of Michigan’s measure closed September at 48.1.
⚡ UK Mortgage Approvals (August) · 4:30 AM ET / 9:30 AM BST The Bank of England’s monthly count of loans agreed for house purchases is forecast at 58,000 after 56,100 in July.
⚡ Spain Flash CPI (September) · 3:00 AM ET / 8:00 AM BST Consensus is 4.7% on the year after 4.3%, the first national reading ahead of Friday’s eurozone figure.
Canada GDP (July) · 8:30 AM ET / 1:30 PM BST Consensus is flat on the month after a 0.3% rise in June.
EARNINGS
⚡ CCL · Carnival · Before Open · ~$30B Watching: the fuel bill. Carnival’s guidance of about $1.35 a share, set in June, was built on spot fuel at $812 a ton, and Brent settled at $104.32 on Friday. Consensus is $1.36 a share on $8.30 billion, and the call is at 10:00 AM ET / 3:00 PM BST.
Also reporting: CarMax and Uranium Energy before the open, and AAR and Concentrix after the close. BWX Technologies holds an investor day in New York.
WEDNESDAY, September 30
⚡⚡⚡ US PCE Price Index (August) · 8:30 AM ET / 1:30 PM BST The Federal Reserve’s preferred inflation measure is forecast to rise 0.4% on the month with core at 0.3%, both up from 0.2% in July. Core is seen at 3.4% on the year from 3.3%, and the headline ran at 3.7% in July. Personal spending lands in the same minute, forecast up 0.8% after 0.2%, with income seen up 0.4% for a second month. Detail in The 3 Events That Matter Most below.
⚡⚡ US GDP, Third Estimate (Q2) · 8:30 AM ET / 1:30 PM BST Consensus is 1.6% annualised, against 1.5% in the second estimate.
⚡⚡ US ADP Employment (September) · 8:15 AM ET / 1:15 PM BST Consensus is 70,000 private sector jobs after 38,000 in August.
⚡⚡ UK GDP, Final Estimate (Q2) · 2:00 AM ET / 7:00 AM BST Consensus is 0.4% on the quarter and 1.2% on the year, both matching the first estimate, after 0.6% growth in the first quarter.
⚡⚡ China Official PMIs (September) · Tuesday 9:30 PM ET / Wednesday 2:30 AM BST Manufacturing is forecast at 50.1 after 49.8 and non-manufacturing at 49.3 after 49.0, where 50 divides growth from contraction. The private RatingDog surveys, formerly branded Caixin, follow at Tuesday 9:45 PM ET / Wednesday 2:45 AM BST, with manufacturing seen at 51.6 from 51.5 and services at 51.1 from 51.4. They are the last activity numbers before mainland markets close for a week on Thursday.
⚡ Australian CPI (August) · Tuesday 9:30 PM ET / Wednesday 2:30 AM BST Consensus is 4.1% on the year after 3.5% in July, landing the day after the rate decision.
⚡ US Chicago PMI (September) · 9:45 AM ET / 2:45 PM BST Consensus is about 51 after 47.1, which would put the Chicago region’s firms back above the 50 line that separates growth from contraction.
⚡ German Flash CPI (September) · 8:00 AM ET / 1:00 PM BST August ran at 2.9% on the year, and France (2:45 AM ET / 7:45 AM BST) and Italy (5:00 AM ET / 10:00 AM BST) publish their own first estimates earlier in the day.
⚡ 3 Federal Reserve Speakers · From 3:25 PM ET / 8:25 PM BST Governor Lisa Cook speaks on the rural economy at 3:25 PM ET / 8:25 PM BST, and Goolsbee gives a keynote on why consumers and economists see different economies at 5:15 PM ET / 10:15 PM BST. Minneapolis’s Neel Kashkari, a voter this year, sits down with CNBC’s Steve Liesman at the Council on Foreign Relations in New York at 6:00 PM ET / 11:00 PM BST.
EARNINGS
⚡⚡⚡ MU · Micron · After Close · ~$1,220B Watching: the gross margin guide for next quarter, set against about 86% this quarter. The company guided to $50 billion of revenue, give or take $1 billion, and $31.00 a share, against $11.32 billion of revenue a year ago. Consensus is $31.45 on about $50.75 billion, and the call is at 4:30 PM ET / 9:30 PM BST.
⚡ JBL · Jabil · Before Open · ~$35B Watching: the fiscal 2027 outlook and how much of it rests on AI and cloud data centre demand. Consensus is $4.06 a share on $9.69 billion against guidance of $3.80 to $4.20, and the call is at 8:30 AM ET / 1:30 PM BST.
Also reporting: FactSet, Conagra and Cal-Maine before the open, and Progress Software after the close.
THURSDAY, October 1
⚡⚡ US ISM Manufacturing PMI (September) · 10:00 AM ET / 3:00 PM BST Consensus is 54.8 after 54.6, and the prices paid index, 71.1 in August, is forecast at 72. August’s employment index was 51.2 and new orders 53.7, and S&P Global’s flash survey last week had manufacturing at a 52-month high of 57.0.
⚡⚡ Fed Vice Chair Philip Jefferson Speaks · 1:30 PM ET / 6:30 PM BST Jefferson’s talk in Charlottesville is titled “U.S. Economy and Monetary Policy”, and Chair Kevin Warsh has no appearance scheduled this week.
⚡⚡ Mainland China Closed for Golden Week · All day Shanghai and Shenzhen shut from 1 to 7 October for National Day and reopen on Thursday 8 October. Hong Kong closes for Thursday only.
⚡⚡ SpaceX Transporter-18 Launch, Carrying Google’s First Orbital AI Test · 2:18 PM ET / 7:18 PM BST A Falcon 9 rideshare from Vandenberg in California carries about 130 payloads, among them a Google test satellite built with the satellite company Planet. Google says it will be the first time its own AI chips, known as TPUs, go into orbit. The launch window runs just under an hour.
⚡ Japan Tankan Survey (Q3) · Wednesday 7:50 PM ET / Thursday 12:50 AM BST The Bank of Japan’s quarterly survey of big manufacturers is forecast around 25 after 22. The Bank’s summary of opinions from the September meeting, which raised rates to 1.25%, publishes in the same minute.
⚡ US Initial Jobless Claims · 8:30 AM ET / 1:30 PM BST Consensus is 199,000 after 197,000 last week, with the 4-week average at 202,250.
⚡ US Challenger Job Cuts (September) · 5:30 AM ET / 10:30 AM BST The outplacement firm Challenger, Gray & Christmas counts announced layoffs every month, and the August total came to 52,881.
⚡ Bank of England Governor Andrew Bailey Speaks · 4:00 AM ET / 9:00 AM BST Bailey opens the Future of Money conference the Bank runs with the London School of Economics. Catherine Mann speaks at a Nomura investor conference at 8:00 AM ET / 1:00 PM BST, and Chief Economist Huw Pill chairs a panel at 8:30 AM ET / 1:30 PM BST.
⚡ 3 More Federal Reserve Speakers · From 10:00 AM ET / 3:00 PM BST Governor Christopher Waller speaks at FRED Con, the St. Louis Fed’s conference on its free public economic database, at 10:00 AM ET / 3:00 PM BST. Vice Chair for Supervision Michelle Bowman speaks on bank capital rules at 3:00 PM ET / 8:00 PM BST, and Governor Lisa Cook joins a central banking discussion at 3:30 PM ET / 8:30 PM BST.
UK and Eurozone Final Manufacturing PMIs · From 4:00 AM ET / 9:00 AM BST The eurozone flash reading was 52.7 and the British one 52.0, with the eurozone final at 4:00 AM ET / 9:00 AM BST and the UK at 4:30 AM ET / 9:30 AM BST.
EARNINGS
⚡⚡ ACN · Accenture · Before Open · ~$110B Watching: the fiscal 2027 revenue guidance, and whether the American federal business returned to growth this quarter as the finance chief said it would. Consensus is $3.18 a share on $18.03 billion against quarterly guidance of $17.75 billion to $18.40 billion, with the shares down about 33% this year. The call is at 8:00 AM ET / 1:00 PM BST.
⚡⚡ NKE · Nike · After Close · ~$55B Watching: the gross margin, which management said would start expanding this quarter. Consensus is $0.44 a share on $11.33 billion, about 3% lower on the year, against $0.49 a year ago, with the shares down 44% this year. Results land around 4:15 PM ET / 9:15 PM BST and the call is at 5:00 PM ET / 10:00 PM BST.
⚡ MKC · McCormick · Before Open · ~$15B Watching: volumes, which fell 0.5% last quarter even as organic sales rose 1.7%. Consensus is $0.76 a share on $1.98 billion, and the call is at 8:00 AM ET / 1:00 PM BST.
Also reporting: Acuity before the open.
FRIDAY, October 2
⚡⚡⚡ US Nonfarm Payrolls (September) · 8:30 AM ET / 1:30 PM BST Consensus is 100,000 jobs after 162,000 in August. A Reuters poll sees the unemployment rate at 4.2% from 4.1%, and average hourly earnings are forecast up 0.3% on the month. Detail in The 3 Events That Matter Most below.
⚡⚡ Eurozone Flash Inflation (September) · 5:00 AM ET / 10:00 AM BST Consensus is 3.5% on the year after 3.2% in August, which would be the highest since September 2023, with core seen at 2.6% after 2.4%. The ECB raised its deposit rate to 2.50% on 10 September.
⚡ Tokyo CPI (September) · Thursday 7:30 PM ET / Friday 12:30 AM BST The capital’s core reading, which excludes fresh food, ran at 1.8% in August, and it is the earliest monthly guide to where national Japanese inflation is heading.
⚡ US Factory Orders (August) · 10:00 AM ET / 3:00 PM BST Consensus is a 0.1% fall after a 0.9% rise in July.
SEC Commissioner Hester Peirce Leaves the Commission · All day Peirce, the commissioner the crypto industry nicknamed Crypto Mom, steps down with effect from Friday, and no replacement has been named.
EARNINGS
No company of any size is scheduled to report.
Tesla has not confirmed a date for its third quarter deliveries, which it published on 2 July last quarter. Consensus is roughly 461,000 against 480,126 in the second quarter and 497,099 a year earlier.